
Some of the greatest businesses in history were not built by inventing something entirely new. They were built by taking something desirable, useful or aspirational that already existed and putting it within reach of millions of people who had previously been excluded.
Sometimes the barrier was price. Sometimes knowledge, complexity, distribution or convention. Often it was simply that the incumbent industry had decided certain people weren’t worth serving.
The great democratisers saw things differently.
Democratisation Is Not Cheapening
Ingvar Kamprad described IKEA as part of a “gigantic project of democratisation.” The company’s purpose was not merely to sell cheaper furniture, but to make the kind of quality products once affordable only to the rich available to everybody else.
Giorgio Armani arrived at much the same idea from the opposite end of the market. He spoke explicitly about the “democratisation” of fashion. After establishing one of the world’s great luxury houses, he deliberately turned towards young people and those who loved fashion but couldn’t afford his main line. The launch of Emporio Armani in 1981 shocked people around him. Casual clothes, denim, lower prices. Critics feared he was diluting the brand, perhaps even destroying the exclusivity that made Armani desirable in the first place.
Armani saw no contradiction.
“I am well aware that style and elegance are everywhere, not only in the upper social classes,” he later wrote.
Lew Frankfort came to a similar conclusion at Coach. Having studied Louis Vuitton, he told his executives he wanted Coach to become a “democratized version of European luxury in America.” Vuitton might appeal to the top one percent of households; Coach could reach the top twenty. Frankfort’s insight was that luxury didn’t have to mean prohibitively expensive.
Frankfort eventually preferred the phrase accessible luxury. It is a useful distinction. Democratisation is not the same thing as cheapening a product. Often the real trick is preserving what makes something desirable while removing the obstacle that keeps most people from enjoying it.
Frankfort was, without necessarily knowing it, describing exactly what Rolex had already built.
Business historian Pierre-Yves Donzé identifies this as one of Rolex’s core competitive advantages: the identification of an entirely new market, what he calls “accessible luxury” — a segment that kept the social signalling of classic luxury while closing the distance that price had always placed between that world and the middle class.
The watches remained expensive. But they were never out of reach: a dream product an ordinary consumer could hope to acquire one day, at a time when Patek Philippe and Vacheron & Constantin were still building small-batch pieces by hand for the “happy few.”
Tadashi Yanai describes Uniqlo’s mission as the “democratisation of clothing.” “We want to sell good clothing to all people, not just the few,” he has said. The objective wasn’t simply cheap clothing, but high-quality clothing at prices almost anyone could afford. IKEA approached furniture much the same way. It kept design and function but changed sourcing, packaging, transport, store format and even who assembled the furniture.
That pattern turns up remarkably often in business history.
The Flywheel of Lower Costs
Almost 200 years ago, Cornelius Vanderbilt became America’s richest man not by serving the richest Americans, but by dramatically lowering the cost of transportation for everyone else. His competitors in the steamboat business largely assumed there was a natural number of passengers travelling between two cities. Cut fares and all you did was fight more aggressively for the same pool of travellers. Vanderbilt believed the pool itself could grow. Make travel cheaper and people who previously stayed home would start travelling.
That sounds obvious now. It wasn’t then.
Vanderbilt could pursue the strategy because he was obsessed with efficiency. “If I could not run a steamship alongside another man and do it as well as he for twenty percent less than it cost him,” he said, “I would leave the ship.”
Lower costs allowed lower fares. Lower fares brought more passengers. More passengers created scale, and scale helped lower costs again. A flywheel, long before anyone called it one.
John D. Rockefeller would eventually build an even greater fortune on much the same principle. Standard Oil’s relentless attack on refining, transportation and distribution costs helped send the price of kerosene dramatically lower, bringing reliable illumination within reach of more households. The attraction was not simply that Rockefeller could produce more cheaply than competitors. It was that he understood the enormous demand that could emerge when a useful product became affordable to ordinary people.
Henry Ford was even more explicit.
“Every time you reduce the price of the car without reducing the quality,” he said, “you increase the possible number of purchasers.”
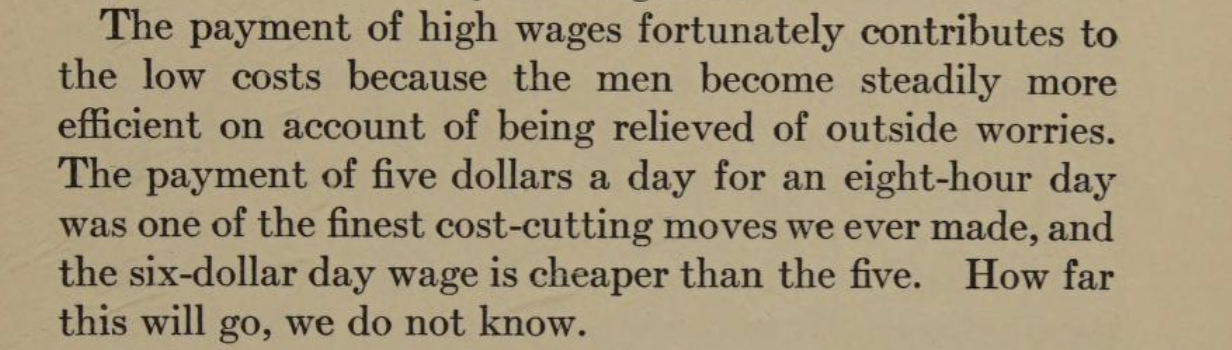
Ford once calculated that cutting the price of a car from $440 to $360 could expand annual demand from roughly 500,000 buyers to perhaps 800,000. Less profit on each car, perhaps, but more cars, more workers, more scale and ultimately more profit.
The automobile industry at the time was still largely organised around wealthy customers. Ford’s ambition was to build a car “for the great multitude.” He understood that the absence of middle-class car buyers did not prove middle-class people didn’t want cars. It proved that cars were too expensive.
“We took what was a luxury and turned it into a necessity,” he later said.
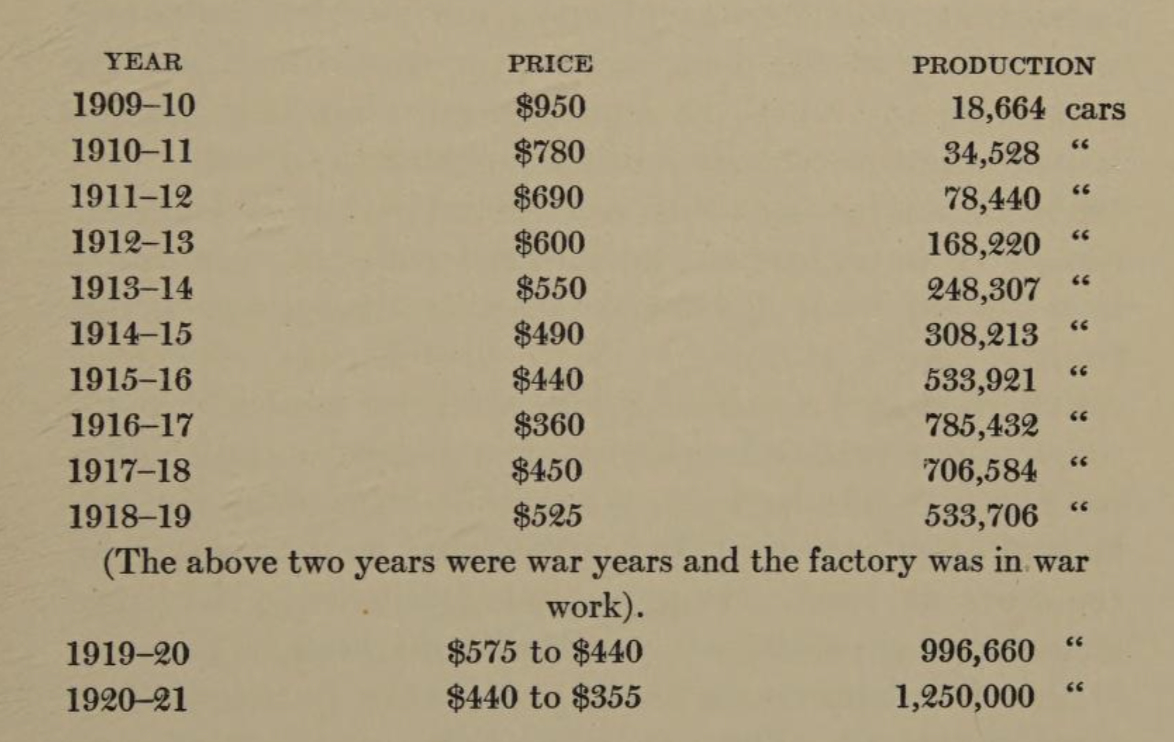
Ford Car Prices & Production 1909 - 1921 [Source: ‘My Life and Work,’ Henry Ford, 1922.]
Seeing Customers Before They Exist
That may be one of the defining characteristics of a great democratiser: they see customers before the customers exist.
A.P. Giannini saw them in banking.
The traditional San Francisco banks largely catered to established businesses and wealthy customers. Giannini’s Bank of Italy - which later became Bank of America - went after immigrants, labourers, shopkeepers and farmers — people who were often intimidated by banks, kept cash at home and sometimes relied on loan sharks. Where established bankers saw deposits too small to matter and loans too small to justify the paperwork, Giannini saw relationships that might last a lifetime.
“The little fellow is the best customer that a bank can have,” he told his people.
It is an extraordinary sentence because the prevailing banking model suggested precisely the opposite. The little fellow looked uneconomic. Giannini changed the economics.
Branching brought the bank closer to customers. Longer hours made it more convenient. Small loans brought people into the financial system who had previously been excluded. The incumbent saw a $25 loan; Giannini saw millions of potential customers.
This pattern repeats. The customers ignored by the incumbent can become the market of the disruptor.
The Humbling of Products
Milton Hershey found them in chocolate. Before Hershey, chocolate remained largely a luxury product. By applying mass-production techniques, he helped turn it into something ordinary families could buy regularly. Frank Woolworth did the same with consumer goods. His stores became famous for offering “articles which were once luxuries” for five and ten cents.
Sears was built on much the same idea. Its history describes the process as the “humbling of products” — the efficient distribution of previously unattainable things to what it wonderfully called the “huge pools of human desire called markets.” The automatic washing machine, once owned only by the rich, was democratised by Sears in 1942: $37.95, with three dollars down and four dollars a month thereafter.
Neither lesson was simply “sell things cheaply.” Woolworth understood that low price without quality was a dead end; the company’s history records his view that it would be fatal to sacrifice quality for price.
When the Barrier Isn’t Price
Home Depot took the idea a step further. Bernie Marcus and Arthur Blank realised that price wasn’t the only thing preventing people from improving their homes. Knowledge was a barrier too. The professional tradesman knew what to buy and how to use it; the ordinary homeowner often didn’t.
“We gave customers the knowledge to do it themselves at the right price,” Blank wrote. He pointed to a striking example: a customer could install a Mills Pride kitchen for $3,000 that twenty years earlier might have cost $25,000 and required a professional.
Home Depot wasn’t simply taking sales from existing hardware stores. By combining lower prices, enormous product choice and knowledgeable staff who taught customers how to do the work themselves, it expanded the population capable of undertaking home-improvement projects in the first place.
That is another form of democratisation: sometimes the barrier isn’t what something costs, but whether the customer has the knowledge or confidence to participate at all.
Reinvest in Lower Prices
IKEA’s Kamprad then did something many businesses find psychologically difficult: he gave much of the efficiencies back. Former IKEA CEO Anders Dahlvig noted that purchasing savings were repeatedly reinvested in lower customer prices rather than simply harvested as higher margins. The objective was to grow the customer base, even when doing so meant sacrificing some short-term profit.
Charlie Munger admired this broader instinct in Costco and GEICO. He said both companies seemed to feel a “holy duty” to provide a wonderful product at a very low price. Plenty of companies claim to offer value; far fewer build the desire to continually push price down and quality up into the “body and soul” of the organisation.
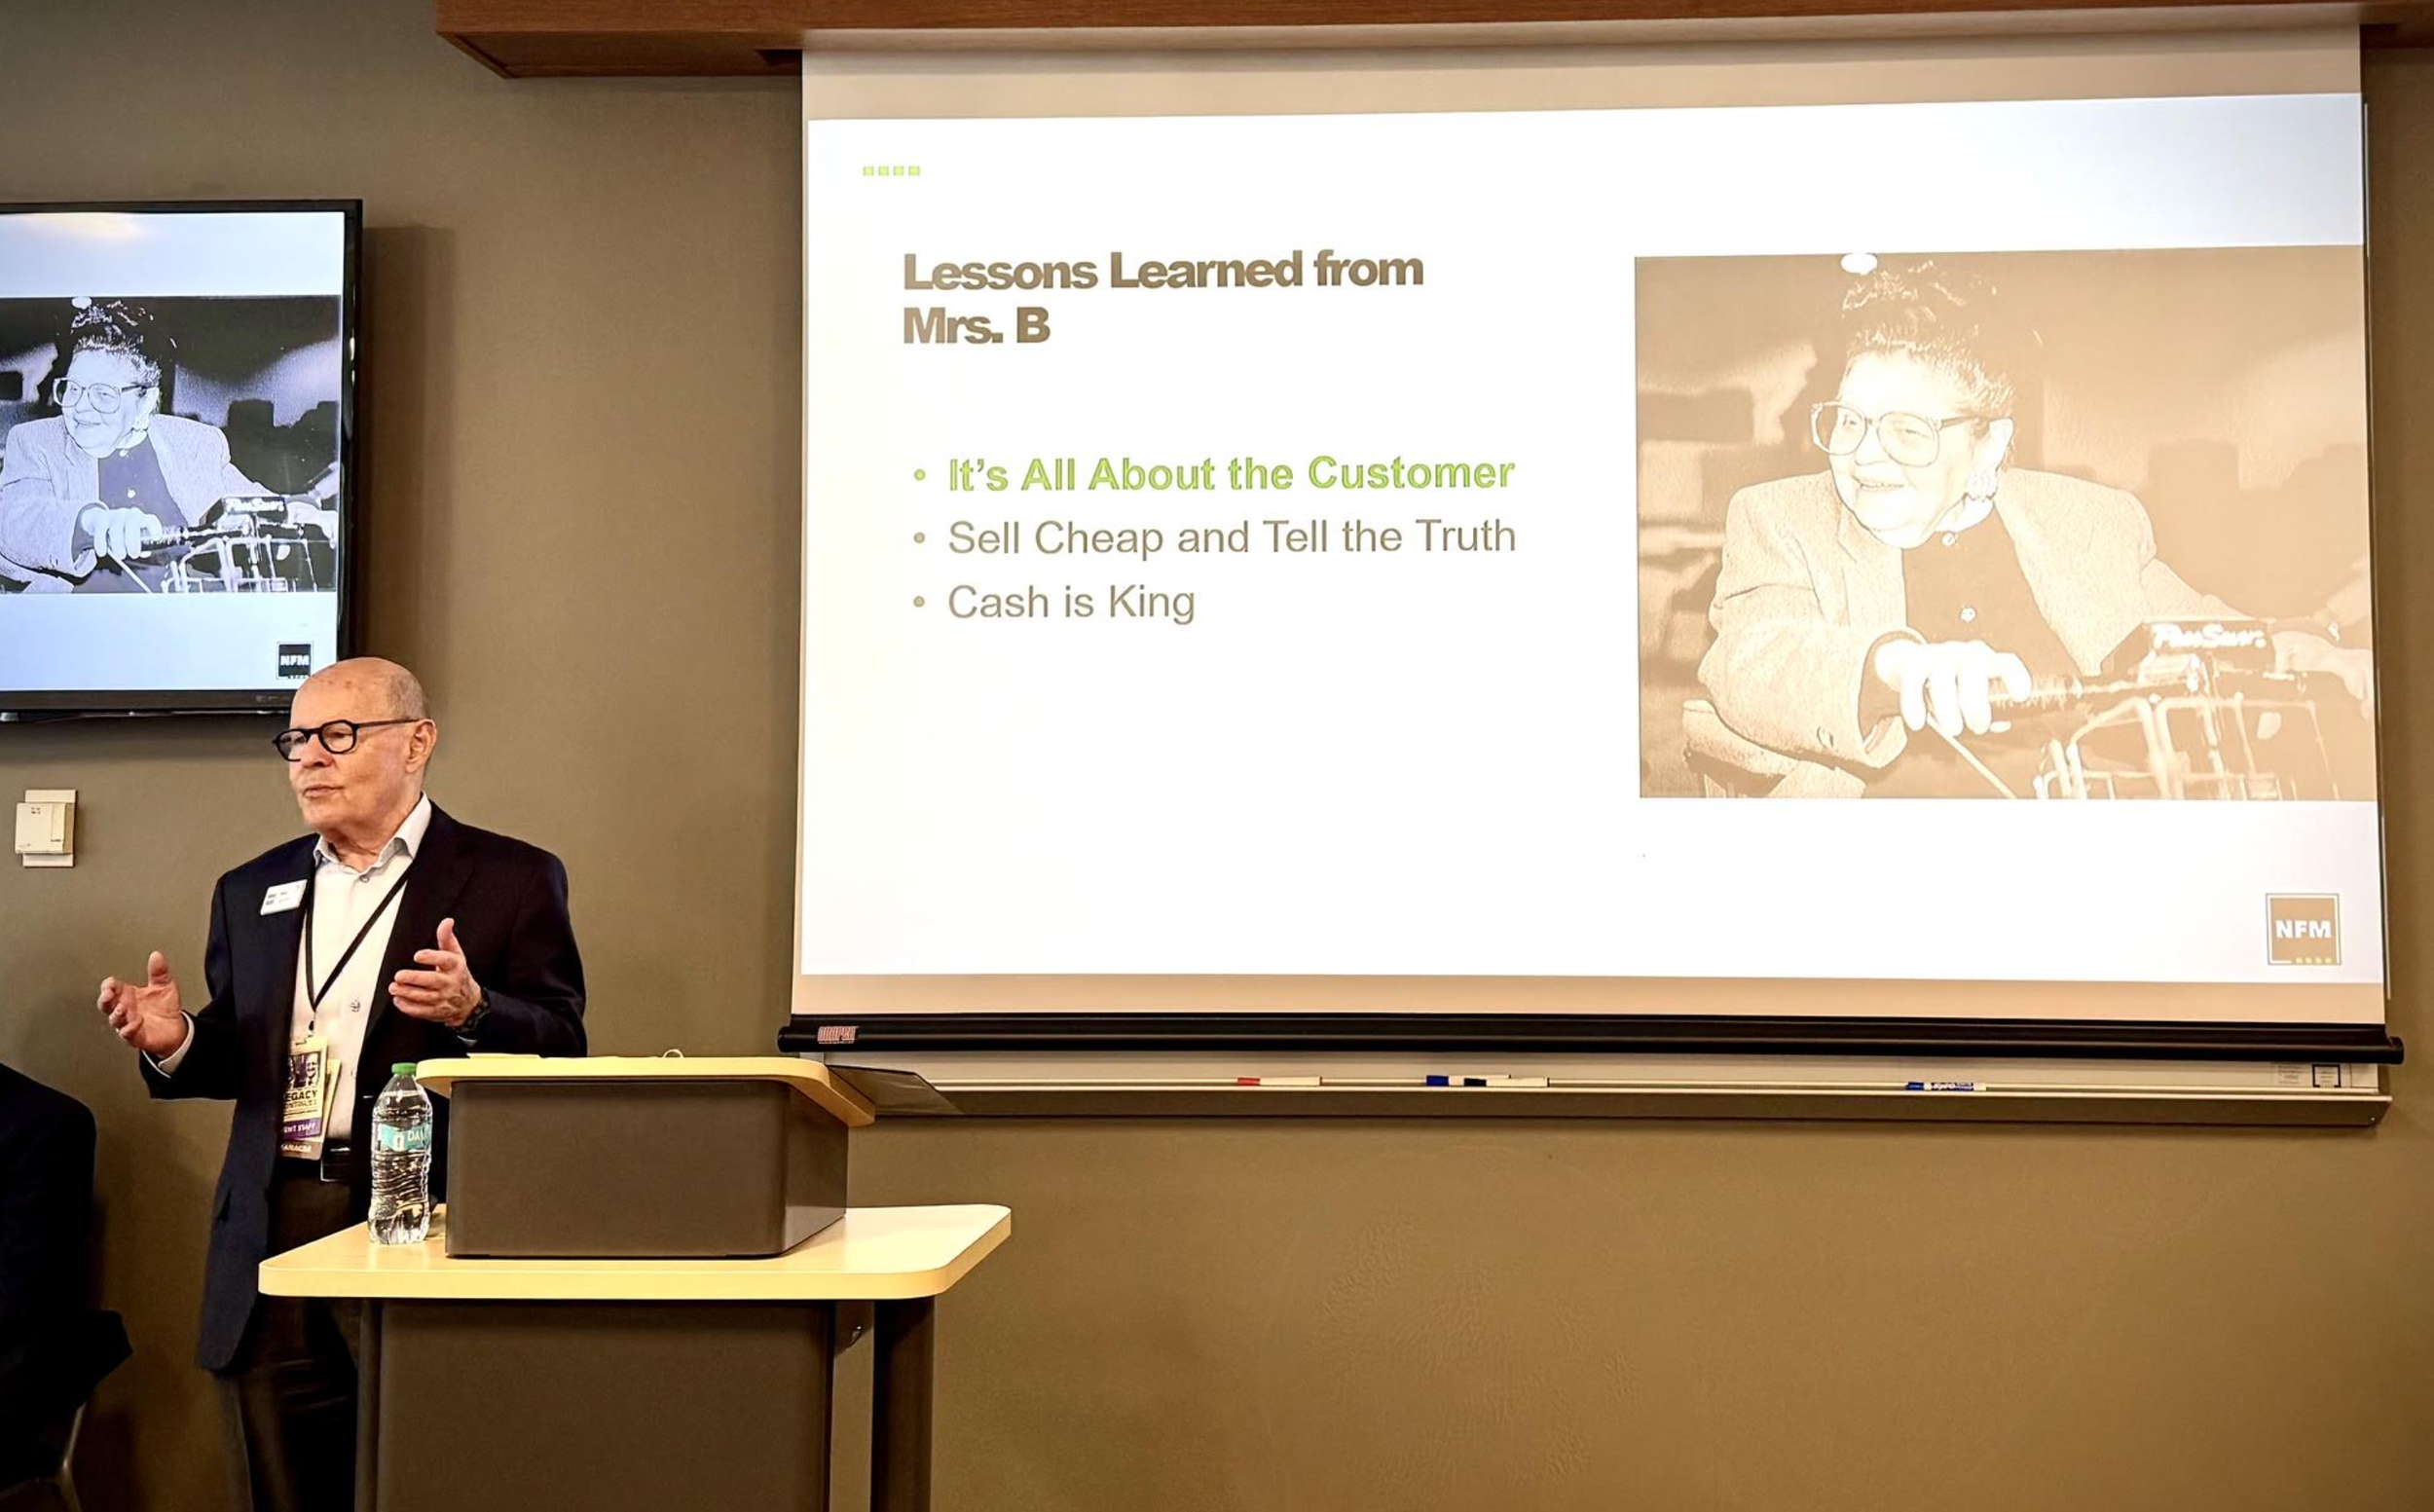
Buffett saw the same thing at Nebraska Furniture Mart. Mrs. B and her family bought brilliantly, operated at expense ratios competitors couldn’t match, and passed much of the saving back to customers. Buffett called it an ideal business: exceptional customer value producing exceptional economics for the owners.
There is a counterintuitive lesson here. If you possess a cost advantage, the obvious temptation is to keep it. Raise the margin. Report the earnings. Enjoy the spread.
The great democratisers often do something else. They reinvest the advantage in the customer.
Lower prices bring more people into the market. More customers increase scale. Scale creates purchasing power, operating efficiencies, brand awareness and distribution density, which can fund another round of lower prices or better service. The margin sacrificed today can become the moat tomorrow.
Liberating the Market
Juan Trippe understood the same principle in aviation. Pan Am became synonymous with glamorous international travel, but Trippe’s ambition was much larger than carrying the wealthy across the Atlantic. He pushed continually for lower fares and greater aircraft capacity because he believed international flying could become a mass-market activity. The Boeing 707 and, later, the enormous 747 were not simply technological achievements; they changed the economics of a seat crossing an ocean.
The same logic Vanderbilt had applied to a steamboat now operated six miles above the earth.
Herb Kelleher later watched it play out at Southwest Airlines. He recalled entering city-pair markets where perhaps 125,000 people flew each year and watching traffic grow towards a million once Southwest introduced low fares, frequent service and convenience. Kelleher didn’t describe this as taking market share. He said Southwest had “liberated” people, allowing them to fly for business and personal reasons far more often than before.
That word is revealing. Liberated. It is the language of removing a constraint.
Aspirational, Not Exclusive
Coach provides another variation. Unlike transportation, banking or household goods, luxury derives some of its appeal from exclusivity itself. Lew Frankfort's insight was that aspiration did not have to disappear simply because the product became more accessible. Coach could remain premium while reaching millions of consumers who could never contemplate traditional European luxury. Frankfort wrote that while traditional luxury was exclusive, Coach could be inviting. A Louis Vuitton handbag might signal that its owner had arrived; Coach could appeal to a woman who was still on her way.
That is democratisation at a subtler level. The challenge isn't simply widening access. It's widening access without destroying the aspiration that made the product desirable in the first place.
Armani did the same with Emporio Armani. Critics imagined luxury as a finite pool of exclusivity: if too many people gained access, prestige would disappear. Armani instead recognised that style was not confined to wealth. There was a vast population of younger consumers who cared deeply about fashion but were excluded by the economics of the traditional luxury house. He didn’t need to persuade them to care. They already cared. He simply needed to let them in.
From Products to Capital
The same idea eventually reached Wall Street. Charles Merrill believed investing should not remain the preserve of wealthy insiders. “We must bring Wall Street to Main Street,” he said, “and we must use the efficient, mass merchandising methods of the chain store to do it.”
Merrill Lynch opened branches across America, advertised aggressively and educated ordinary people about stocks. The objective was not merely cheaper brokerage; it was what Merrill's son later called “demystification” — making Wall Street intelligible and accessible to the small investor.
Charles Schwab would later push the same democratisation further through discount brokerage, while Satya Nadella has described Microsoft's original raison d'être as democratising computing.
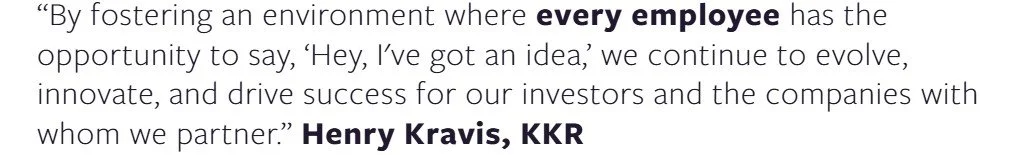
Henry Kravis has used exactly the same language at KKR:
“We spend a lot of time on a new area that we all came up with, and that’s a democratized product, which means that we’re enabling a retail investor to invest in the KKR product just like an institutional investor has been able to do for years.”
Again, the underlying investment capability already existed. The innovation was widening access to it.
Sizing a Market That Doesn’t Exist Yet
And that brings us to something especially relevant for investors.
We spend a great deal of time estimating total addressable markets. We take the number of existing customers, multiply it by some price or penetration assumption and build a spreadsheet around the result.
But what if the existing market is only the market permitted by the existing business model?
Reid Hoffman makes the point directly: when estimating market size, investors need to consider how lower costs and product improvements can expand the market by attracting new customers, not simply taking share from existing ones. Aaron Levie put it even better: sizing a disruptive market from the incumbent market can be like sizing the automobile industry by counting the number of horses in 1910. The current market may tell you very little about the eventual one.
Every business in this essay was assessed twice: once by the incumbent, who saw a customer too poor, too uninformed or too small to bother with — and once by the founder, who saw the same person as the market.
The spread between those two assessments is where the return lived.
A $10,000 product may have one million customers. At $1,000 perhaps it has ten million. But price is only one constraint.
The most valuable customer may be the one who isn’t a customer yet.
That is why I find the democratisers so interesting. They tend to combine several characteristics we often look for separately: relentless efficiency, customer orientation, willingness to sacrifice some current margin, scale economies, intelligent distribution and an unusually expansive view of the market.
More than anything, they refuse to accept the industry’s definition of who the customer is. The great democratiser asks a different question:
Who would become a customer if we removed the thing keeping them out?
Business history understandably celebrates the inventor — the person who creates something the world has never seen before. But another kind of entrepreneur has created just as much value: the one who takes something already wonderful and asks why so few people get to enjoy it.
The breakthrough isn’t always invention. Sometimes the breakthrough is access.
* Visit the Blog Archive *
Learn more with us on Twitter: @mastersinvest
TERMS OF USE: DISCLAIMER