Q.U.A.L.I.T.A.T.I.V.E

At university, I spent the week of study leave before exams cramming a semester into my head. To make it stick, I turned key concepts into odd words built from their first letters. In the first minutes of each exam, I’d scribble them onto the blank pages of the answer booklet before they vanished, then use them to rebuild everything I’d learned. It wasn’t sophisticated, but it worked, and the habit stuck. Years later, Robert Cialdini’s principles of influence, a guide to why people act the way they do, became CLASSROOM in my head. (Consistency, Liking, Authority, Social Proof, Scarcity and Reciprocation. The ‘Classroom’ represents Unity, the seventh principle Cialdini added later.)

Recently, I did it again, this time for the characteristics that set exceptional businesses apart. For as long as I’ve been investing, I’ve studied hundreds of businesses, from Costco, Cintas, Enterprise, Publix, Aldi, Patagonia, Simpson Manufacturing and National Cash Register to companies that faltered or failed altogether. The same traits kept appearing. Different industries, geographies, eras and personalities, yet strikingly similar philosophies. In the failures, those traits were often conspicuously missing. Few of them show up in a spreadsheet.

Financial statements tell us what has happened. They rarely reveal whether employees are proud of what they make, whether customers love the business, whether suppliers are treated as partners, or whether management will sacrifice this year's profits to protect its reputation a decade from now. Yet these are often the very things that determine the numbers of the future.

Two companies can report identical margins, one because of a beloved product and a loyal workforce, the other because it has squeezed suppliers and deferred essential spending. The numbers look the same; the businesses couldn't be more different.

As Buffett observed, “The really big money tends to be made by investors who are right on qualitative decisions.” Munger explained why: “You really have to understand the company and its competitive position, and the reasons why its competitive position is what it is, and that is often not disclosed by the math.” Pat Dorsey put it more bluntly: “Quantitative data is efficiently priced, qualitative insight is not.”

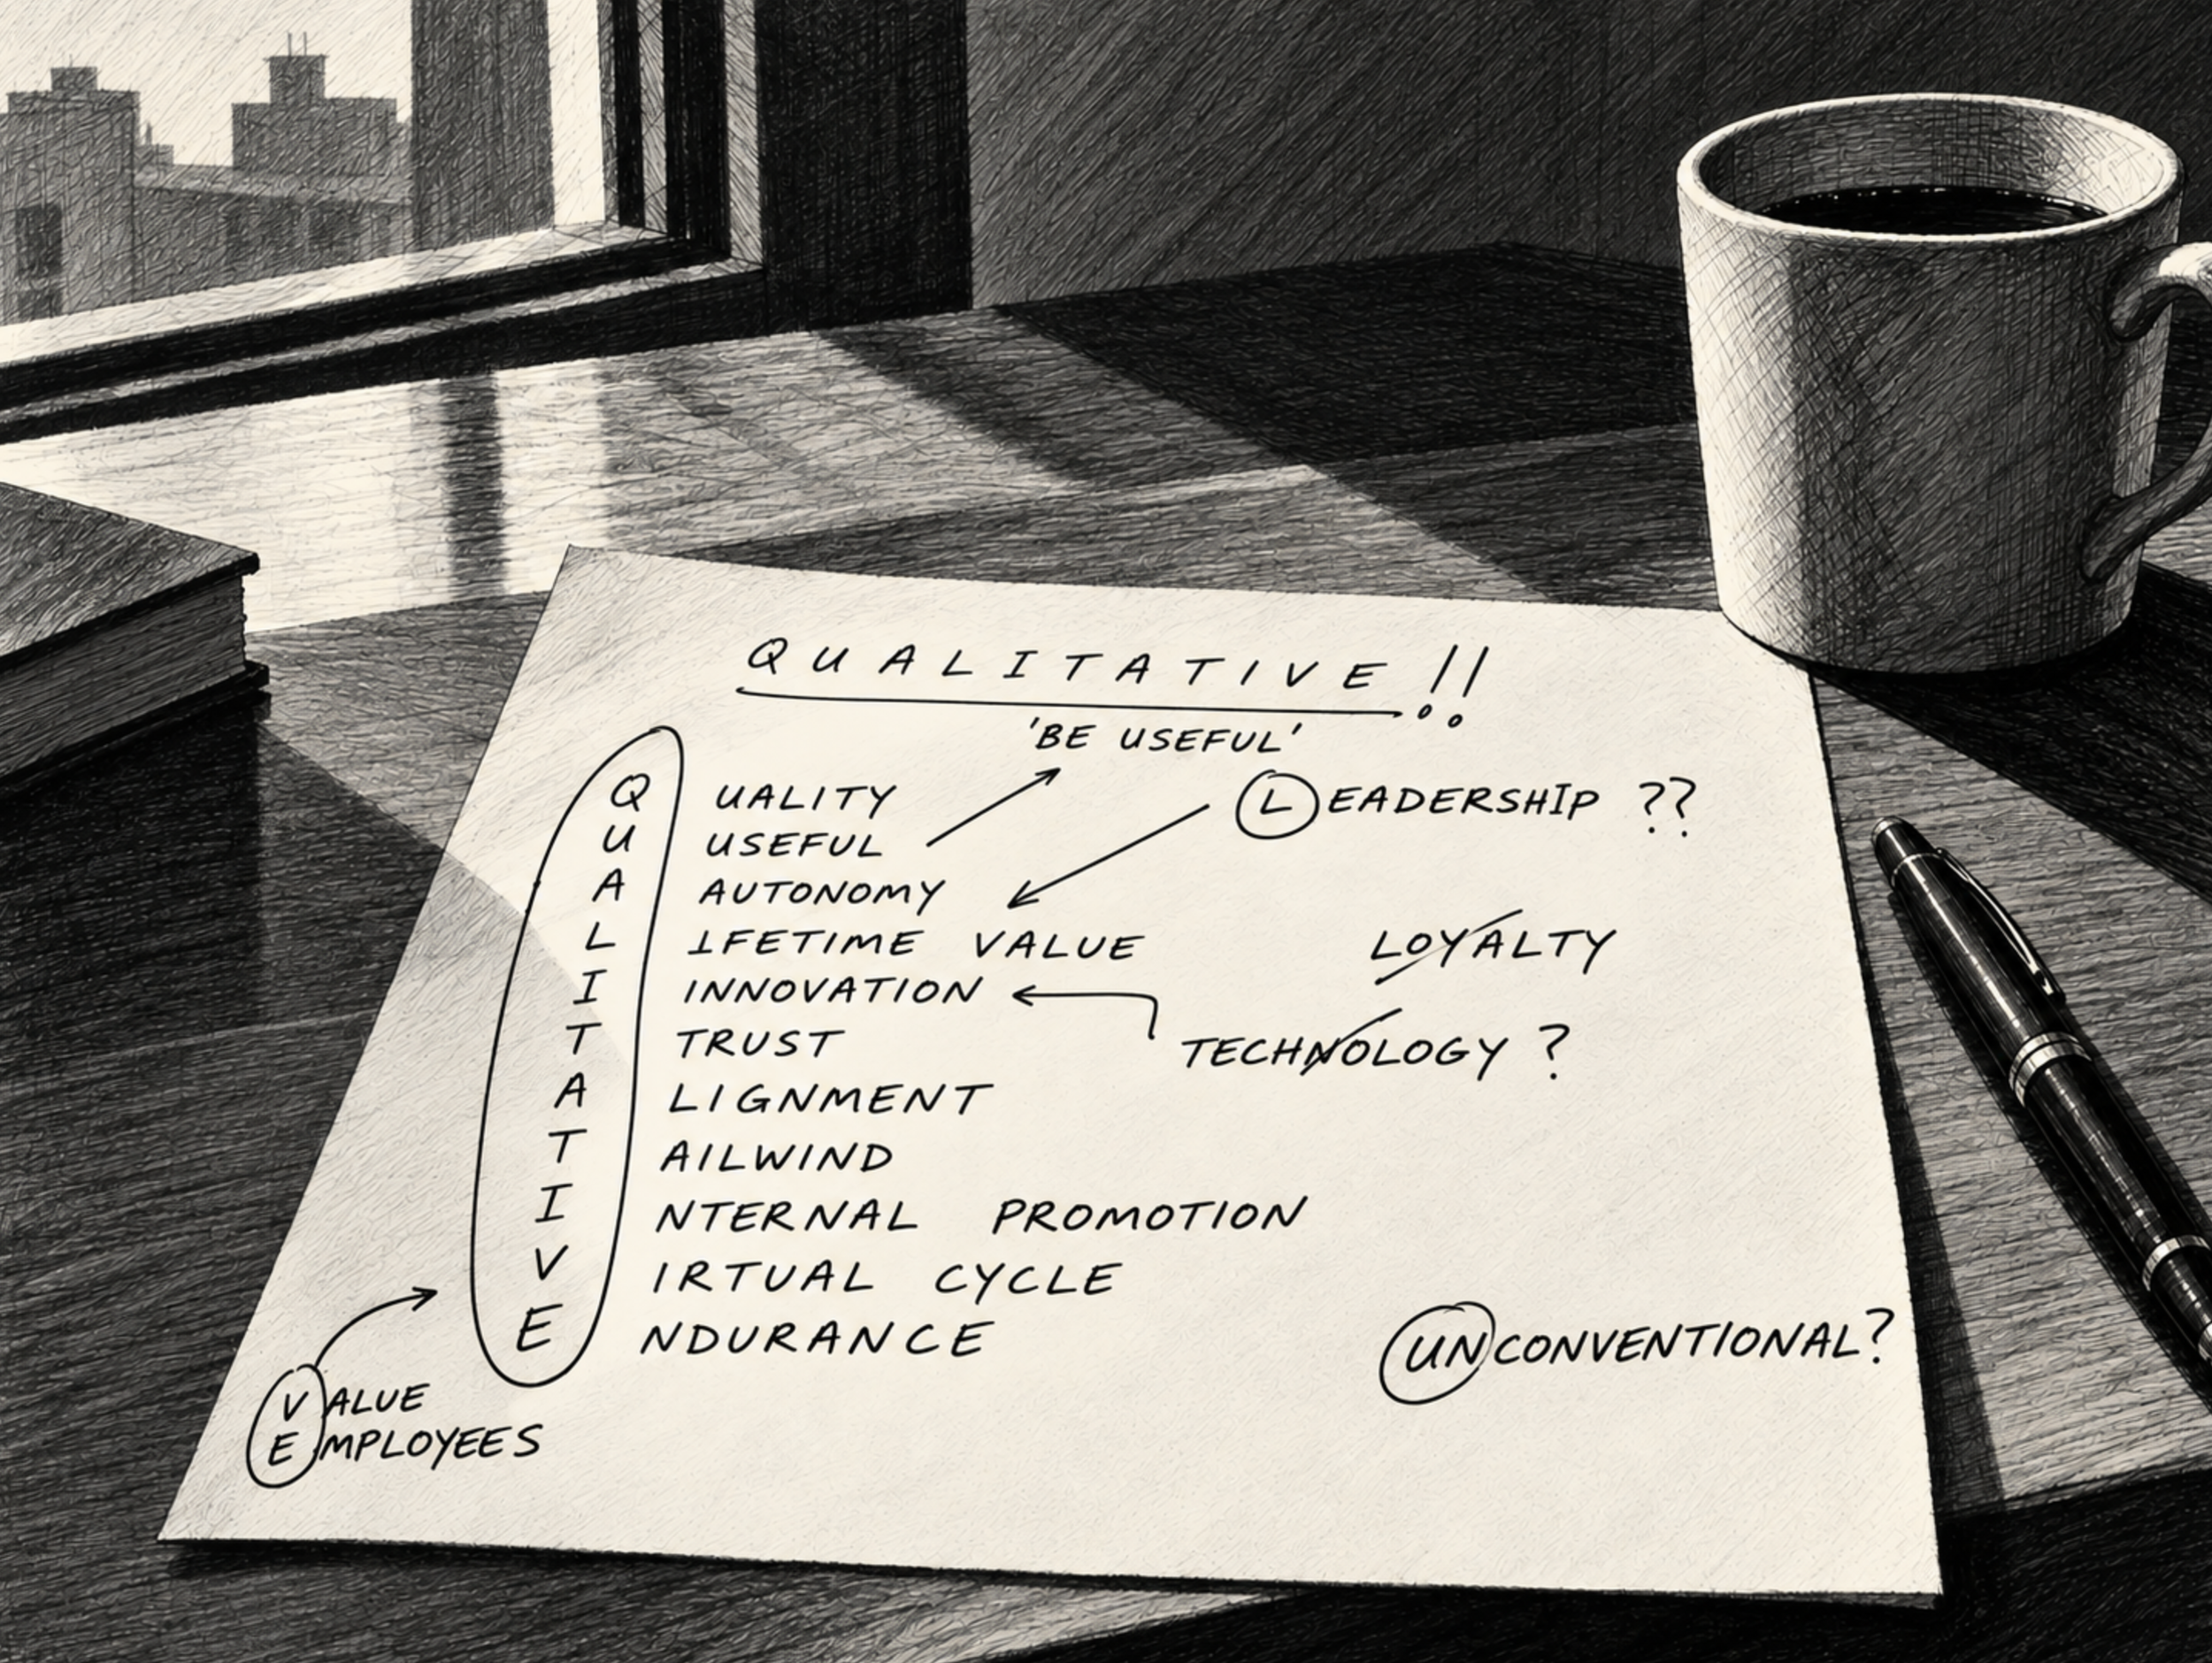
With a little creative licence, the traits I kept finding spelled a fitting word: QUALITATIVE.

  • Quality — an obsession with the product that is never compromised to hit a target.

  • Useful — creating real value that customers would genuinely miss.

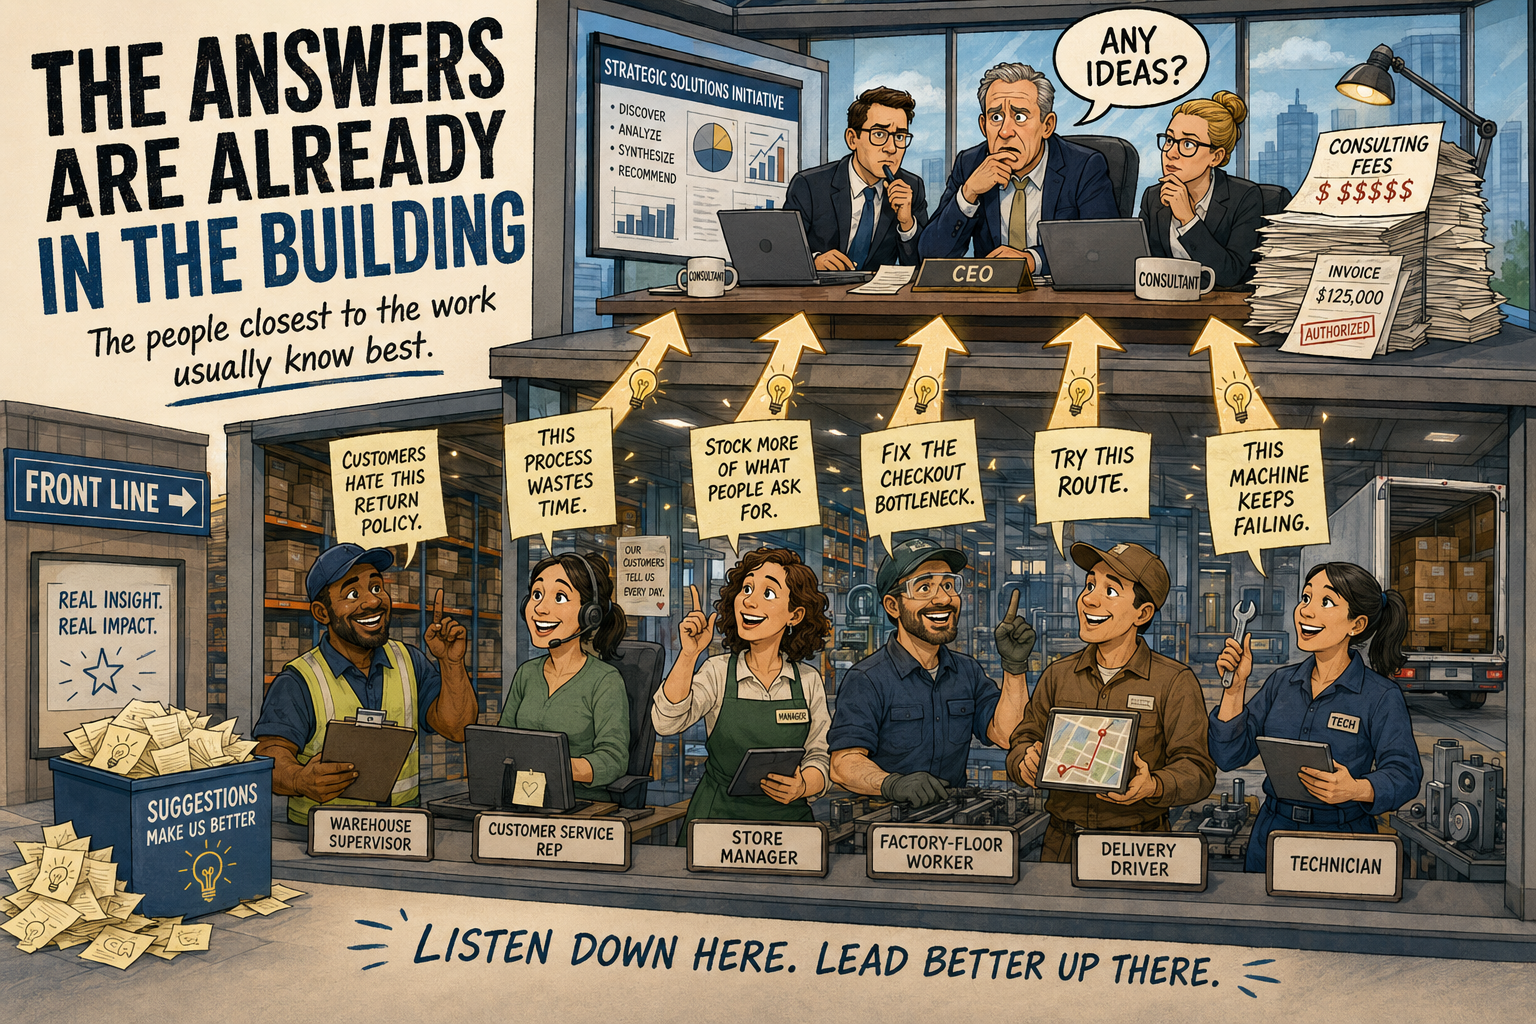
  • Autonomy — pushing decisions to the people closest to the action.

  • Lifetime Customer Value — seeing customers as relationships, not transactions.

  • Innovation — continual reinvention, before it's forced.

  • Trust — earned with employees, customers and partners alike.

  • Alignment — win-win relationships with every stakeholder.

  • Tailwinds — competing in markets that can grow for decades.

  • Internal Promotion — growing leaders from within who already carry the culture.

  • Virtuous Circle — traits that reinforce one another.

  • Endurance — playing the long game.

Eleven letters. Eleven characteristics. A simple reminder of what often separates an ordinary business from an extraordinary compounding machine.

Quality

Quality is one of the most enduring sources of competitive advantage. Not high margins or returns on capital, though those often follow, but an obsession with the product itself, so embedded in the culture that standards are never compromised to save a few dollars or meet a quarterly target. Andrew Carnegie put it best: "The surest foundation of a manufacturing concern is quality. After that, and a long way after, comes cost."
The real test is what a business does when customers won't notice the difference. Steve Jobs described the craftsman who refuses to use cheap plywood on the back of a chest of drawers, even though nobody will see it. He will know it's there. Buffett regarded quality at See's Candies as "sacred," while Costco and Aldi prove that low prices and high quality aren't opposites: strip out unnecessary cost, never quality.
Cutting corners can flatter near-term earnings, but quietly erodes the trust that produces them. By the time the damage shows in the numbers, it's often too late. Businesses that hold the line earn what competitors struggle to copy: reputation, repeat business and pricing power.

As Aldo Gucci observed, "Quality is remembered long after the low price is forgotten." The irony is that companies willing to put quality ahead of short-term profit often end up earning the greatest long-term profits.

Useful

One of the simplest questions to ask of any business is how useful it is. Does it save customers time, reduce their costs, remove headaches or help them succeed? Barclay Simpson, founder of Simpson Manufacturing, urged his people to ask, "How can you help make their jobs easier? How can you improve their lives?"

An equally revealing test is to imagine the business disappeared tomorrow. Would customers genuinely miss it? Would they struggle to replace it?

The best businesses don't merely satisfy customers; they create enormous value for them. Buffett described Nebraska Furniture Mart as "the ideal business – one built upon exceptional value to the customer that in turn translates into exceptional economics for its owners." Ron Blumkin put its purpose more simply: "We improve people's lifestyles." Frederick Reichheld observed that companies which leave plenty of surplus on the table for customers may sacrifice some current profit, but build trust and loyalty that insulates them from competitors.
Costco, Aldi and Amazon continually hand the gains from scale back to customers rather than capturing them all as margin. HEICO built its business making FAA-approved replacement aircraft parts at substantially lower prices than the original manufacturers, saving airlines hundreds of millions of dollars. The most enduring businesses focus less on extracting profit from each transaction and more on increasing the value they deliver.
Usefulness is also the most durable source of pricing power. When a business delivers far more value than it charges, it can raise prices and customers still come out ahead. The distinction matters. Pricing power earned through usefulness tends to endure; pricing power that simply extracts more from captive customers invites resentment, regulation and competition.

Autonomy

Autonomy is one of the most consistent themes I've found in exceptional businesses. At Berkshire Hathaway, Constellation Software, Fastenal, HEICO, Enterprise Rent-A-Car and IKEA, the philosophy is remarkably similar: push decisions down, give people responsibility and trust them to get on with the job. Those closest to the action usually know far more about customers and problems than anyone in head office.
As Captain David Marquet put it, "Don't move information to authority, move authority to the information." Genuine responsibility changes how people feel about their work. They begin to think and act like owners, with pride and initiative replacing compliance. Mark Leonard observed, "Autonomy and responsibility attract and motivate the best managers and employees."
Decentralisation allows large organisations to preserve the responsiveness of smaller ones. Constellation deliberately keeps its business units small, Fastenal's store managers operate like independent shopkeepers, and Ray Kroc wanted the man closest to McDonald's stores to decide without seeking directives from headquarters.
Buffett summed up Berkshire: "We centralize money and — everything else we decentralize, pretty much." Centralised control and layers of approval can slowly extinguish the very initiative that made a business successful.

Lifetime Customer Value

Great businesses understand the lifetime value of a customer. They see not a single transaction but a relationship that can last decades. As Enterprise Rent-A-Car founder Jack Taylor put it, "Repeat customers are the quickest way to build a solid business."
Fred Reichheld tells of a Domino's franchisee who calculated that a regular customer was worth more than $5,000 over ten years, and made sure every employee, from the phones to the delivery drivers, knew it. An unhappy customer was no longer a $20 pizza gone wrong, but thousands of dollars walking out the door.
Loyalty is one of the most valuable, yet least visible, assets a business can own. Loyal customers return, recommend the business and rarely switch for a slightly lower price. Yvon Chouinard estimated a sale to a loyal Patagonia customer was worth six to eight times more to the bottom line than any other. Reichheld found, "In most of the industries we've studied, the companies with the highest customer retention rates also earn the best profits."
The question isn't how many customers a business attracts, but how many it keeps, and for how long. Terry Leahy, who made loyalty the centrepiece of Tesco's rise to Britain's largest retailer, judged every decision by a single question: "Will it make people more loyal to us or not?"

Innovation

Success is no guarantee of survival. Industries change, customers evolve and business models that once seemed unassailable become obsolete. The best businesses preserve their principles while continually adapting how they operate. At 3M, encouraging experimentation created businesses far removed from its original mining operations, and Amazon’s willingness to reinvest and enter new markets reflects a refusal to regard any business model as permanent.
The method is usually humble. Ideas come from anywhere: Sam Walton borrowed freely from competitors, and some of McDonald’s best-known products, including the Big Mac and the Egg McMuffin, came from franchisees rather than head office. New ideas are tested small, in a handful of stores or with a few customers, before they’re rolled out widely. And failure is tolerated, because a company that punishes every miss soon stops trying anything new. Fastenal moved beyond its branch model into onsite inventory management and vending, and Cintas expanded from uniform rental into additional services, using its relationships and distribution network to solve more customer problems.
The danger is confusing consistency with rigidity. Principles may be timeless, but the practices that support them are not. Kodak helped pioneer digital photography yet failed to adapt its business model quickly enough, and Sears, which once transformed American retailing, eventually lost the ability to reinvent itself. Great companies know what should never change and what must continually evolve. They are willing to challenge their own success before somebody else does.
Trust

Trust is the invisible infrastructure of a great business. It reduces friction, eliminates unnecessary costs and allows people to act without endless supervision, contracts and approvals. At Berkshire Hathaway, Buffett gives managers extraordinary freedom because he trusts their judgement and character. At Nordstrom, the legendary employee handbook was distilled into a single instruction: use good judgement in all situations. The assumption was that capable, trusted people would usually do the right thing without being told.

Trust extends well beyond employees. Costco has built a reputation for treating customers fairly, while Enterprise understood that loyalty depended on delivering what had been promised, every time. At Cintas and Fastenal, long-standing customer relationships rest on reliability, responsiveness and consistently doing the right thing. A customer who trusts a company doesn't need to scrutinise every transaction, and a supplier who trusts its partner is more willing to invest in the relationship.
Trust takes years to build and moments to destroy. It accumulates through thousands of small decisions, particularly when doing the right thing is inconvenient or costly. Like a strong balance sheet, it provides resilience when conditions deteriorate. But unlike cash or inventory, it rarely appears in the accounts. Watch closely how management behaves when its interests conflict with those of customers, employees or suppliers. That's often when the true character of a business becomes visible.
Alignment

The best businesses create win-win relationships with everyone they touch. Peter Kaufman argues for seeing through the eyes of six counterparties (customers, suppliers, employees, owners, regulators and communities) and structuring relationships so each benefits.
Yet he notes many businesses are proud of win-lose arrangements, boasting of how hard they squeeze suppliers. Stanley Marcus recalled that “equity” was his father’s favourite word at Neiman Marcus, practised with employees, customers and vendors alike. Munger, a long-time Costco director, put it simply: “Costco is into win-win. That’s what really works.”
Incentives are where alignment is tested. Munger famously observed, “Show me the incentive and I’ll show you the outcome,” and admitted that all his life he had underestimated their power. At Publix, Costco, Southwest Airlines, Fastenal and Enterprise Rent-A-Car, profit-sharing, equity ownership and performance pay have helped create cultures where employees act like owners. Herb Kelleher told of Southwest employees treating even the staplers as their own. As Jack Stack put it, “A company of owners will outperform a company of employees any day of the week.”
The temptation to maximise one party’s share of the pie is understandable. But squeezing a supplier today can mean losing a valuable partner tomorrow, and underpaying employees may lift this year’s margins while increasing turnover, eroding service and driving away customers. Poorly designed incentives do similar damage: pay salespeople purely on commission and they put transactions ahead of relationships, or reward executives for short-term earnings and they sacrifice investment and quality. Look beyond how much people are paid to what they’re paid for. The best businesses don’t merely divide the pie; they find ways to make it bigger.

Tailwinds

Warren Buffett once observed, "One of the lessons your management has learned — and, unfortunately, sometimes re-learned — is the importance of being in businesses where tailwinds prevail rather than headwinds." Peter Keefe noted, "Every mega compounder we've owned had a long secular tailwind behind it," and Dan Davidowitz found his biggest winners had decades-long market opportunities ahead of them. Even the best managers struggle against a shrinking market.
The automobile, suburbs and interstate highways created enormous opportunities for McDonald's. Tailwinds can come from regulation too: Barclay Simpson rode post-war construction and stricter building codes to make Simpson Strong-Tie the industry standard, and Alan McKim of Clean Harbors recalled tougher environmental rules in the late 1980s creating "a gold rush of sorts."

Others come from where people move. Florida's population grew from 1.9 million to 9 million between 1940 and 1979 as Publix expanded across the state, A.P. Giannini built Bank of America as California grew more than sevenfold in the first half of the century, and Discount Tire rode the shift to the Sunbelt, where new residents had no loyalty to established retailers. In South Korea, Hyundai's Chung Ju-yung observed, "Since Hyundai's founding, the company and the country grew in tandem."
A tailwind gives a successful business room to keep growing and reinvesting profits without having to take share from competitors. It is no guarantee of success, but without one, even the most capable management team may spend its energy fighting for scraps in a shrinking pie. Great management matters, but choosing the right industry makes its job considerably easier.

Internal Promotion

The pattern is hard to miss. Danaher, Macquarie Bank, O’Reilly, ABC Supply, Publix, Wegmans, Texas Roadhouse, USAA and Würth all grow their own leaders. More than 95 percent of Fastenal’s branch general managers were promoted from within, and in its first 34 years Les Schwab never hired a manager from outside: every one started out changing tyres. Jim Collins found that ten of eleven good-to-great CEOs came from inside the company. Mark Leonard explained Constellation’s preference simply: “Mutual trust and loyalty take years to build, and conversely, newly hired smart and/or manipulative mercenaries can take years to identify and root out.”

When Monty Moran became co-CEO of Chipotle, the data settled the question for him. Managers who had come up from crew positions ran much better restaurants and were four times less likely to quit than those hired from outside. Within two years, he lifted internal promotion from about 30 percent to 100 percent. The benefits compound. Ambitious people join because they can see a path upward. Existing staff stay motivated, managers know every job beneath them, and they hire more carefully because they’re choosing a future general manager rather than filling a role. The reverse is just as powerful. As Mary Kay Ash warned, when a company too often looks outside, people conclude that no matter how well they perform, an outsider will get the job they want.
For investors, the habit is a useful signal. Culture is carried by people, and an outsider at the top often brings a different one. A steady stream of external executives, especially in the CEO’s chair, deserves a closer look. There are exceptions. Phil Fisher accepted that rapid growth or specialist skills sometimes justify outside hires, but he was clear on the rule: “In general, however, the company with real investment merit is the company that usually promotes from within.”

Virtuous Circle

Perhaps the most important insight is that these characteristics rarely operate in isolation. Like strands in a rope, each is modest on its own; woven together, they become remarkably strong. At Costco, well-paid, fairly treated employees stay longer. Experienced staff deliver better service and run more efficient operations, which support lower prices. Lower prices attract more customers and greater volumes, improving buying power and operating leverage. Those gains are passed back to members, strengthening loyalty and driving the cycle again.
Jack Taylor built a similar system at Enterprise. Give managers responsibility and incentives, focus relentlessly on customer satisfaction, and satisfied customers return and recommend the business. Growth creates opportunities for employees to advance, and their commitment sustains the service that keeps customers loyal. Amazon's flywheel works the same way: better customer experiences attract more traffic, more traffic attracts sellers and selection, and greater scale lowers costs and prices, attracting still more customers.

This is why great businesses are so difficult to compete against. Their advantage isn't a single product, patent or strategy that can be copied, but a system of mutually reinforcing behaviours built over decades. A rival may match Costco's prices, Fastenal's service model or Enterprise's satisfaction measures. Replicating the culture, incentives, relationships and economics that make the whole system work is considerably harder.
The reverse is equally powerful. Cut employee benefits and service may deteriorate. Squeeze suppliers and quality can suffer. Sacrifice product standards and customers lose trust. A small decision to improve margins can set off consequences that weaken the entire business. Pull one strand loose and the whole rope begins to fray. Good businesses build virtuous circles. Poorly managed ones create vicious ones.

Endurance

The final characteristic is a willingness to play the long game. Great businesses make decisions with years and decades in mind, not the next quarter. They invest through downturns, preserve relationships when doing so is costly and resist the temptation to maximise short-term profits at the expense of future opportunities.
At Berkshire Hathaway, Buffett has long emphasised financial strength and allowing exceptional managers to build businesses over decades. At Costco, Jim Sinegal resisted pressure to maximise margins and focused instead on delivering value to members. George Jenkins built Publix around employee ownership and customer service designed to endure beyond any single generation of management.

Privately owned businesses such as Enterprise and In-N-Out Burger have used patient ownership to favour customer experience, employee development and measured growth over short-term targets. At IKEA, Ingvar Kamprad's emphasis on thrift, affordability and independence established a culture intended to outlast its founder.

Long-term thinking is easy to profess and much harder to practise. It may mean turning away a profitable customer, declining an acquisition, forgoing a price increase or investing in something whose payoff won't arrive for years. Those choices may make this year's earnings look worse while leaving the business considerably stronger. The real question is whether management is prepared to make them.

Add an Extra L, If You Like

There's one notable omission from the list. I spent some time wondering whether leadership deserved its own letter. QUALLITATIVE doesn't spell anything, but I'd forgive anyone who wrote it that way.
In the end, I left it out because it's already everywhere. Look closely and much of the list describes great leadership in practice. Great leaders create alignment and earn trust. They push decisions down and give people autonomy. They keep the business focused on the customer, and resist the pull of the next quarter for the sake of the next decade.

It's no coincidence that so many of the businesses I've studied were shaped by founders, or by leaders who think like them: fanatical about the details, with meaningful skin in the game, and casting a long shadow over the culture they built. Tone is set at the top. Employees watch whether a leader's behaviour matches their words, and integrity, or its absence, cascades through every layer of an organisation. Leadership isn't a separate box to tick; it's the thread running through all eleven. When these characteristics are present, it's usually because someone at the top put them there, and has protected them ever since.

Bringing It Together

What strikes me after studying so many businesses is how often the same ideas reappear. The industries change, the products differ and the founders come from different generations and countries. Yet the philosophies barely change. Look after customers. Treat employees well. Share the rewards. Push decisions down. Never compromise quality. Keep innovating. Think long term.

Over decades, small differences in behaviour, and the profits they generate reinvested in the same virtuous circle, can produce enormous differences in outcomes.

The financial statements are the result. The culture, relationships and decisions behind them are often the cause.

At university, those strange acronyms helped me remember the answers. Decades later, QUALITATIVE serves a slightly different purpose.

It helps me remember the questions worth asking.


* Visit the Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
Look at Your Fish

David McCullough was widely regarded as one of America's greatest biographers and historians. He won two Pulitzer Prizes and two National Book Awards, and was awarded the Presidential Medal of Freedom. Above the desk where he wrote those books hung a small card with four words on it: "Look at your fish."

When an interviewer asked about it, McCullough told a story he had told many times to his writing students. It concerns Louis Agassiz, the nineteenth-century Harvard naturalist, and the test he set every new student who came to study under him. It is a story about science, and McCullough used it as a story about writing. It is also one of the best lessons in investing I have come across, and it says nothing about markets at all.

The Ordeal with the Fish

Agassiz would take an odorous old fish from a jar, set it in a tin pan in front of the student and say four words: "Look at your fish." Then he would leave.

When he came back he would ask what the student had seen. "Not very much," was the usual reply. Agassiz would say it again, "Look at your fish," and leave again. This could go on for days. The student was encouraged to draw the fish but was allowed no tools for the examination. No magnifying glass. No scalpel. Just hands and eyes.

Samuel Scudder, who later became a famous entomologist and the leading expert on grasshoppers, left the best account of what he called the ordeal. After several days he still could not see whatever it was Agassiz wanted him to see. But he had noticed something about himself: "I see how little I saw before."

Then Scudder had a brainstorm. He arrived the next morning and announced it: "Paired organs, the same on both sides."

"Of course! Of course!" said Agassiz, very pleased.

So Scudder naturally asked what he should do next.

"Look at your fish."

"I See How Little I Saw Before"

The line in that story I return to most is not the breakthrough. It is the confession that came before it.

Most of us, handed a stock, an annual report or a business, look for as long as it takes to form an opinion, and then we stop looking. The opinion is mistaken for the seeing. Agassiz understood that the first look is mostly a look at our own assumptions. Only once those are exhausted, once boredom sets in and the student is forced to keep looking anyway, does the object itself begin to appear.

"I see how little I saw before" is where the real work starts. It is an admission of ignorance, and it is the precondition for everything that follows.

Marcel Proust put it memorably: "The real voyage of discovery consists, not in seeking new landscapes, but in having new eyes."

Insight Is Usually Already on the Table

McCullough's own reading of the story is the part every investor should pin above their desk: "Insight comes, more often than not, from looking at what's been on the table all along, in front of everybody, rather than from discovering something new."

This runs against much of how our industry works. Most investors look at the same things: the earnings announcement, the quarterly call, the broker reports. But in a market where public information is distributed instantly and universally, the fish is in front of everybody. The annual report is the same document for every reader. The difference is what each reader sees in it.

The great investment insights often look obvious in hindsight. A business that has promoted from within for decades. A founder who has never sold a share. A customer relationship structured so that both sides win. A culture whose stated values match its demonstrated ones. None of this is hidden. It sits in the history, the proxy statements, the founder's letters, the way the company talks about its people and treats its suppliers. It is simply not looked at for long enough, or by people who know what they are looking for.

The Business That Does Things Differently

John Kay once turned Tolstoy's famous opening to Anna Karenina on its head. In business, he argued, unhappy companies tend to resemble one another, while each successful company succeeds in its own way. "Business achievement depends on doing things that others cannot do." The challenge for an investor is to recognise those differences before their significance becomes obvious. Often, what makes an exceptional business exceptional looks, at first glance, like a disadvantage.

The clearest examples are businesses whose model is a deliberate departure from their industry's, where the difference was visible for decades to anyone who cared to look.

Aldi and Tesco. Walk into an Aldi and the difference is right in front of you: a fraction of the products a conventional supermarket carries, almost all of them private label, stock sold from the cartons it arrived in, a small team doing many jobs, smaller stores often in cheaper secondary locations rather than prime sites, and everyday low prices instead of a weekly cycle of specials. Tesco built the opposite: vast range, loyalty schemes, constant promotions, supplier income and relentless expansion. Since 2007, Aldi's UK market share has risen from 3 to 11 per cent; Tesco's has fallen from 31.6 to below 28.

HEICO and the OEMs. The aerospace original equipment manufacturers earn much of their return on spare parts, priced high because airlines have few alternatives, and those margins sat in plain view in their own accounts. HEICO built its business making FAA-approved replacement parts and selling them 30–50 per cent below the OEM price. It has been run on a decentralised model by the Mendelson family since 1990, with employees owning a substantial stake. Airlines save money, HEICO earns an excellent return, and the relationship is win-win rather than extractive. Since 1990, sales have compounded at about 16 per cent a year, from $26 million to $3.86 billion.

Costco and Sam's Club. Costco caps its markups well below what it could charge, pays its staff far above the retail average and earns most of its profit from membership fees. For years some analysts criticised it for being too generous to employees and customers at shareholders' expense. On a spreadsheet, its thin gross margin looked like a weakness. In reality it was the moat. Walmart's Sam's Club opened the same year with the same warehouse format, run on a lower-wage, higher-turnover model. By fiscal 2025, Costco's sales were $270 billion against Sam's $90 billion, and each US Costco warehouse sold roughly twice as much as a Sam's Club.

Nucor and US Steel. Under Ken Iverson, Nucor built mini-mills that melted scrap in electric arc furnaces, kept a tiny head office and only a handful of management layers, and paid workers bonuses tied to their mill's output. In downturns, management took pay cuts before workers lost jobs. US Steel ran integrated mills with layered management and adversarial labour relations. Nucor became the largest steel producer in America; US Steel was eventually sold to Nippon Steel.

Each pairing is the same fish viewed two ways. The conventional observer saw Aldi's narrow range, HEICO's discounts, Costco's thin margins and Nucor's unglamorous scrap and read them as limitations. The investor who kept looking saw the culture and business model, with the stated strategy matching demonstrated behaviour year after year. None of it required a proprietary data set. It required looking at the fish.

The Fish and the Price

There is a twist for investors that the naturalist never faced. Agassiz's student only had to see the fish. An investor has to see the fish and see what everyone else believes the fish to be.

Howard Marks: "What is the most reliable way to make money as an investor? Find situations where perception underestimates reality."

Seth Klarman explains why seeing alone is not enough: "In investing, other people's perception of reality influences price more than any underlying truth; your own assessment, even if correct, is valueless if it is already reflected in the market price."

François Rochon frames it as a matter of degree: "Opportunity arises when the gap between reality and perception becomes significant." A small gap is noise. A wide one is a fish nobody else has looked at properly.

No Tools — Just Hands and Eyes

Agassiz's most interesting rule was the ban on instruments. Tools carry other people's way of seeing. A magnifying glass decides for you where to look; a scalpel decides what is worth cutting into.

Agassiz took away the real scalpel. The investor's scalpel was always imaginary anyway. Álvaro Guzmán de Lázaro describes his firm's work this way: "We dissect reality with an imaginary scalpel to see if things are what they appear to be or not (i.e. what the market says they are!)." The instrument that matters is the one you carry in your head.

The investor's equivalents are everywhere: the stock screen, the consensus model, the sell-side note, the factor exposure report, the preset fields on the terminal. All useful. But each frames the fish before you have looked at it. A screen for low price-to-earnings ratios sees only what a price-to-earnings ratio captures. A model built from last year's numbers extrapolates last year. None of them will tell you that the founder still walks the factory floor, or that the company has never had to hire a chief executive from outside.

Robert Henri, the American painter and teacher whose The Art Spirit is among the finest books ever written on learning to see, distrusted any technique that came between the artist and the subject: "To my mind a fanciful, eccentric technique only hides the matter to be presented, and for that reason is not only out of place, but dangerous, wrong." The investing parallel is the beautifully constructed spreadsheet, discounted to four decimal places, that obscures rather than reveals the one or two things that actually matter about the business.

Note, too, that Agassiz encouraged his students to draw. Drawing forces seeing in a way that glancing never does: you cannot draw what you have not looked at. Betty Edwards built a whole method on this in Drawing on the Right Side of the Brain. She has students copy a picture turned upside down, which stops the mind from naming what it sees ("a nose", "a hand") and forces it to see the actual lines. John Singer Sargent used a similar trick, studying his portraits in progress upside down and through a mirror. Peter Kaufman calls this "getting outside the system," becoming unanchored from the familiar view so that its flaws become visible.

The investor can do the same. Write the thesis out in plain words, without a single valuation multiple. Describe the business as if to someone who has never heard of the ticker. Read the annual report back to front, notes first. Argue the bear case. Each is a way of turning the fish upside down.

Go and Look

For an investor, hands and eyes means going to the business itself. Phil Fisher called it scuttlebutt: talking to the people who see a company from every side, including customers, suppliers, competitors and current and former employees, and piecing together a picture no annual report contains. He found competitors among the most revealing sources of all. Few people understand a business's strengths and weaknesses better than those who have to compete against it.

This is not outsourced thinking. It is the opposite. The broker note is someone else's drawing of the fish. Walk the aisles of an Aldi and the business model is in front of you. Ask a supplier how a company pays its bills and you will learn more about its culture than any values statement will tell you. Ask a competitor whom they fear, and why. Ask a former employee why they left, and why so many of their colleagues stayed. At a trade fair, notice which competitor's stand is busiest, and ask the sales reps who they are losing business to. Arrive early for a meeting and watch people come through the door: do they look glad to be there? Notice how many people have been there ten or twenty years.

One of the most valuable conversations I have had as an investor came while we owned a truck and bus parts distributor. We spoke with an industry executive who had been backed by a dominant industry player to build a competing business, with a budget running to many millions of dollars. He had done the work properly, including gathering detailed feedback from customers. His conclusion was that it could not be done. The time and cost of replicating the parts catalogue were prohibitive, and even then success was unlikely, given the prices and service our company already provided. It was the clearest evidence of a moat we could have asked for, and we would never have reached it through our discussions with the company. Management were unlikely to know that a well-funded rival had studied them closely and walked away. No annual report records the competitor that never arrived.

As with Scudder's drawing, the discipline is in the noticing. The same questions asked of many sources begin to reveal a pattern.

We See What We Expect to See

The old line, "We do not see things as they are. We see things as we are," explains why the fish is so hard to see. We arrive with the answer already in mind, and what we look at mostly confirms it.

Charlie Munger, characteristically, reduced the cure to a single instruction: "Recognize reality even when you don't like it — especially when you don't like it."

The striking thing about markets is how violently perception moves while the fish lies still. Marks again: "In the real world, things generally fluctuate between 'pretty good' and 'not so hot.' But in the world of investing, perception often swings from 'flawless' to 'hopeless'."

The fish in the tin pan did not change between Monday and Thursday. Scudder did.

Don't Run with Crowds

Henri had a sharp line for those who let the group decide where to look: "Many things that come into the world are not looked into. The individual says 'My crowd doesn't run that way.' I say, don't run with crowds."

Crowds look at the same fish from the same angle, at the same moment, through the same instruments. That is precisely why the price reflects their view. Benjamin Graham's intelligent investor is "a realist who sells to optimists and buys from pessimists," which is only possible if the realist is not standing in either crowd.

John Huber puts his finger on why this matters so much: "My observation is that independent thought is extremely rare, which makes it very valuable… outsourced thinking appears to be pervasive." Most of the market is studying someone else's drawing of the fish.

Baillie Gifford makes the practical point: "If we are to see what others don't, and to spot potential, we must welcome different perspectives and steer clear of conventional inputs."

Living with the Fish

Agassiz's method took days. It was slow by design. Our industry, by contrast, rewards the appearance of activity: more meetings, more notes, more trades, more opinions delivered faster.

Henri: "No one can get anywhere without contemplation. Busy people who do not make contemplation part of their business do not do much for all their effort."

Scudder's breakthrough came after days, not minutes. The fish did not change. What changed was the length of the acquaintance. Isaac Newton, one of history's greatest scientific minds, described his method of discovery in much the same way: “I keep the subject constantly before me, and wait ’till the first dawnings open slowly, by little and little, into a full and clear light.”

In investing the equivalent is measured in years, and the best investors treat that time not as waiting but as looking.

Nick Sleep saw the long holding period as a gift of exactly this kind: "There is a lot to be said for gentle contemplation. And of course, a long investment holding period allows one time between decisions to 'retreat and simmer' a little."

Li Lu makes the same point: "Most of the time, we grow with the company through thick-and-thin over many years, even decades. We gain unique insights this way, which in turn helps to improve our decision making over time."

That is Scudder's week, stretched across a decade. Day one is "not very much". Year three is paired organs.

Conviction Is a Relationship

Phil Fisher compared getting to know a management team to marriage: "You never really know the girl until you live with her. Until you've lived with a management, you don't really know them to that same degree."

Ian Cassel puts it in terms of trust: "It's impossible to have the same conviction at the beginning of a new investment that you had/have after 2-5-10 years in a successful investment. Conviction is like building trust in any relationship. It takes time. It can't be rushed. Every new investment is a new relationship."

Which is why many of the investors I most admire are in no hurry to start. Stephen Arnold allows "at least a year to feel like we know and understand a business well enough to even contemplate owning it." David Abrams keeps a running list of businesses and people, noting that research sometimes runs "more than a decade before we first look at something to buying it."

And Munib Islam describes where it leads when the seeing is right: "Some of our largest long-term winners are businesses where our conviction has increased over time. That conviction compounds alongside the business itself."

Our industry tends to treat a long holding as inactivity. In fact it is the longest look at the fish anyone in the market has had. Every annual report, every management meeting, every downturn lived through is another morning in front of the tin pan.

Educate Yourself

The most important thing Agassiz did was refuse to give Scudder the answer. He could have pointed to the paired organs on day one and saved everyone a week. But a fact handed over is not the same as a fact seen. Scudder never forgot what he found himself.

Henri said the same to his own students: "The best advice I have ever given to students who have studied under me has been just this: 'Educate yourself, do not let me educate you — use me, do not be used by me.'"

This is the paradox of learning from the masters, and it sits at the heart of why I write this site. Henri's advice was to go to kindred spirits, "others who have wanted to do that thing and study their ways and means, learn from their successes and failures and add your quota." Study Buffett, Marks, Klarman and the rest by all means. But no master, broker, newsletter or blog can see your fish for you. Their value is in teaching you how to look, not in telling you what is there.

The other teacher is your own past work. For investors, that is the investment journal: the theses written down at the time, before the outcome was known. Philip Tetlock's prescription: "Forecast, measure, revise; it is the surest path to seeing better."

The Master Is Never Finished

There is a final detail in the story that is easy to miss. When Scudder succeeded, Agassiz did not congratulate him and move on. He told him to keep looking. The reward for seeing something is more looking.

Henri: "It's a wrong idea that a master is a finished person. Masters are very faulty, they haven't learned everything and they know it. Finished persons are very common people who are closed up, quite satisfied that there is little or nothing more to learn."

The best investors I have met share this quality. They hold strong views and remain genuinely curious about where those views are wrong. Many of them are still working well past most people's retirement age, still looking, and still finding something new on the same old fish.

Make Me See

McCullough closed his answer by invoking what he called Dickens' great admonition to all writers: "Make me see." Seeing, he said, is as much the job of a historian as it is of a poet or a painter.

It is the investor's job too. The difference is that the investor must first make themselves see. The fish is on the table, in front of everybody. The annual report is public. The history is written. The culture is visible to anyone who visits, listens and pays attention.

What is scarce is not information. It is the patience to keep looking after you think you have seen it all, the humility to say "I see how little I saw before", and the discipline to begin again.

So pick up the next annual report, the next business, the position you have held for a decade and think you know completely.

Look at your fish.

* Visit the Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
The Technology of Foolishness

In early 1995, Don Gooding, a telecom analyst at the venture firm Accel, kept returning to a useful guide to the internet with a peculiar name. He thought it might make an interesting investment. Then, at a board meeting, the name came up.

"Yahoo?"

People around the table laughed. Gooding got cold feet and never made the pitch. Within weeks, Sequoia was tracking down the founders.

Some of the best ideas in business look ridiculous at the start. That is almost the point. If everybody immediately understands an idea, agrees it will work and can model it neatly in Excel, there is a fair chance the opportunity is already obvious. The interesting ideas arrive differently: too expensive, too cheap, too big, too small. Nobody will pay for it. The maths doesn't work. And occasionally, simply, that's stupid.

Tom Peters and Robert Waterman, in In Search of Excellence, had a phrase for the organisational capacity to entertain ideas like these: “the technology of foolishness.” It isn’t foolishness for its own sake, and it isn’t recklessness. It is a way of giving apparently foolish ideas enough room to survive until reality can decide whether they actually are.

The New Always Looks Odd

Reid Hoffman has observed that great businesses often look like bad ideas at first because business-model innovations, by definition, cannot point to an existing successful model to show why they will work. Chip Wilson, the founder of Lululemon, likes Peter Diamandis's line that "the day before something is a breakthrough, it's a crazy idea." If an idea could be quantified, Wilson adds, it would have been done already.

Arthur Blank remembers competitors walking through the early Home Depot stores and telling him precisely what was wrong. The stores were too big. Prices were too low. There was too much inventory and too many services. "The math isn't going to work."

Dollar Tree met an even simpler objection. Macon Brock recalled mall developers listening to the concept and laughing in their faces. "You're going to sell stuff for a lousy dollar?" The customers turned out to be less sceptical than the landlords.

FedEx's hub-and-spoke network was ridiculed as impractical. Howard Schultz heard that rolling out coffee stores was crazy. Sam Walton ignored the prevailing wisdom that discount retailing belonged in large population centres and went after small-town America instead. "If we listened to that sort of stuff," he said, "we never would have gone into small-town discounting in the first place."

Rory Sutherland has a nice way of framing it. Imagine pitching investors on a very expensive vacuum cleaner, a premium-priced drink that failed in taste tests, or coffee costing many times what people could make it for at home. Dyson. Red Bull. Starbucks. Described before the fact, some of the world's great businesses sound like terrible ideas.

Henry Ford understood this more than a century ago: "The new is always thought odd."

A Niche. A Laughingstock.

When ESPN went on air in 1979, cable television was still being wired into American towns and people were arguing about whether the medium had any future. A twenty-four-hour sports network was considered ridiculous. George Bodenheimer recalls the top brass at the three major New York networks watching ESPN's first broadcasts and shaking their heads. Nothing to worry about. A niche. A laughingstock.

Frank Perdue ran into a different orthodoxy. Conventional wisdom held that you never advertise a commodity, and pouring money into the thin-margin chicken business seemed dumb. Prudent men thought Frank had flipped. He advertised his chickens anyway and built one of the best-known brands in the country.

The pattern goes back further. S.C. Allyn remembered joining NCR when its founder, John H. Patterson, was roundly ridiculed, just as his product, "the cash register that nobody wanted," had been before him. Allyn's own father shook his head sadly when his son turned down Price Waterhouse to join NCR at $20 a week.

When Birkenstock introduced its new sandal, shoe manufacturers "heaped us with insults." Retailers thought the wide, beak-like sandal was behind the times, even indecent. In 2008, when Brian Chesky and his co-founders tried to raise $150,000 for 10% of Airbnb, most of the angel investors they were introduced to didn't even reply.

Sometimes even the founders aren't convinced. When the Crocs founders first saw the clog, they laughed at how ugly it was. Then they wore them. The first reaction to something new is often a verdict on its unfamiliarity rather than its merit.

The Wrong Measuring Stick

Part of the problem is that new things are judged by the standards of what they are replacing, and on those standards they often are worse. Rory Sutherland points out that early cars were in most respects worse than horses, early aircraft were insanely dangerous and early washing machines unreliable. Geoffrey Parker makes the same point about platforms: YouTube, Airbnb and Wikipedia were criticised at launch because they couldn't match the quality and reliability of their traditional competitors.

Carlota Perez takes the argument further. The possibilities of a radical innovation can be so difficult to picture before the new paradigm arrives that even the people creating it underestimate them. Edison thought the phonograph might be useful for recording the wills of dying people. In the 1950s, the boss of IBM thought a handful of computers would satisfy the world's total demand. Alexander Graham Bell struggled to be understood with his primitive telephone in a world that already had an efficient telegraph.

Contrast that with innovations inside the prevailing paradigm. Everybody understands them. Engineers, investors and consumers know what the product is for and how it might be improved. In a kitchen already full of electrical appliances, even an electric can-opener seems worth making.

That asymmetry sits at the heart of this essay. The incremental idea is legible, so it gets funded. The radical idea is illegible, so it gets laughed at.

Scott Cook lived it at Intuit. The big home runs, he says, are often totally new paradigms, and the problem with a new paradigm is that nobody believes it because everyone is locked in the old one. Venture capitalists all turned Intuit down. The bigger the eventual opportunity, the harder it can be to see at the start, because the world that will make it valuable doesn't exist yet.

Why Not?

Eli Broad built a philosophy around questioning the obvious. The first conventional wisdom he and Don Kaufman encountered in homebuilding was that nobody in Detroit would buy a house without a basement. They asked, "Why not?"

Basements had historically stored coal for winter heating. Gas heating had made that unnecessary, and builders elsewhere were already selling basement-less homes. Skipping the basement meant building faster and being able to sell $2,000 below the nearest competitor, low enough that a monthly mortgage payment could undercut rent for first-time buyers.

Broad's view was blunt: reasonable people treat conventional wisdom with respect; unreasonable people regard it as an expression of the herd instinct. The restaurateur Sean Feeney puts it more simply: when someone says "that's just the way it is," there's money to be made. Tom Monaghan of Domino's refused to reject an idea merely because it didn't make sense yet. If you wait for something to make sense before exploring it, he said, you'll never get anywhere.

A Computer Under Your Arm

One of my favourite examples comes from Xerox PARC. In the early 1970s Alan Kay described a machine he called the Dynabook, a notebook-shaped computer with a screen and keyboard that an individual could carry around and use to create, edit and store their writing, music and art. Today it sounds mundane. At the time it sounded ridiculous. One colleague remembered Kay painting a picture of people walking around with computers under their arms: "We all thought [it] was completely ridiculous."

Today you might be reading this on one.

PARC became one of the extraordinary concentrations of technological creativity in business history. The Alto personal computer, graphical interfaces, the mouse, Ethernet, the laser printer, object-oriented programming and other technologies that shaped modern computing emerged from an environment that gave unusually talented people considerable freedom. Much of it had little obvious relevance to Xerox's copier business. PARC gave people room to explore before somebody in finance demanded the three-year return on investment. Room, in other words, to look foolish.

Xerox famously failed to capture anything close to the economic value of everything invented at PARC. The ability to invent is different from the ability to commercialise. But before an idea can be commercialised, it has to be allowed to exist.

Peters and Waterman's "technology of foolishness" was an argument for mechanisms that permit this: small teams, experimentation, product champions, bootlegging, skunk works. They shield an idea from the immune system of the established organisation while it is still too weak to defend itself.

Fragile Things

Ideas are asymmetric. Once established, a great idea can become enormously powerful, but at birth it has very little going for it: no history, customers, earnings record, five-year CAGR or institutional supporters. Sometimes it has just one person saying I think there might be something here, opposite a room explaining why there isn't.

Bob Propst of Herman Miller described innovation in its early stages as toddling around. It doesn't know how to stand up or explain itself. The words aren't right and the facts aren't apparent. What are the test results? There are none. His colleague Hugh De Pree added the uncomfortable corollary: innovation is threatening, while organisations are built precisely so they won't be threatened.

Charles Brower put it beautifully: "A new idea is delicate. It can be killed by a sneer or a yawn." Ed Catmull at Pixar saw his job as protecting ideas from being judged too quickly. James Dyson called them "fragile things." Jony Ive said Steve Jobs understood better than anyone that ideas begin as "fragile, barely formed thoughts, so easily missed, so easily compromised, so easily just squished."

Baillie Gifford has written the same belief into its investment discussions. Ideas are fragile, so conversation focuses on building them up rather than knocking them down. Challenge is welcome, but with a view to strengthening the case.

This is where culture matters, because a bad reaction doesn't just kill the idea on the table. It changes what everyone else is willing to bring to the next meeting.

Killed by a Giggle

The Yahoo story comes from Sebastian Mallaby's The Power Law, and the detail that makes it is how close Accel came. Gooding wasn't idly browsing. He had been exploring the nascent internet while building the firm's first website, and he was preparing to propose Yahoo as an investment. One laugh around the boardroom table was enough to end that. There seemed little point pitching something that would be greeted with giggles.

Jason Fried observes that dismissing an idea takes no skill. The hard part is protecting it, letting it marinate, riffing on it and trying it. David Ogilvy recalled Albert Lasker being asked the best asset a man could have. His answer: "Humility in the presence of a good idea."

Michael Ovitz had a simple rule at staff meetings: "No idea is too stupid." George Mecherle, founder of State Farm, operated similarly. People could disagree, but nobody's opinion was ridiculed because workable plans had often emerged from the wildest ideas.

Mecherle knew the other side. A former farmer turned insurance salesman, he noticed that farmers were paying the same auto insurance rates as everybody else despite having fewer accidents. Charging less to those less likely to crash sounds obvious now, but it was new. His employer wouldn't entertain it and reportedly told him that if he didn't like the way things were run, he should start his own company. So he did.

Peters and Waterman found the same instinct at 3M. Among its values was an "eleventh commandment": "Thou shalt not kill a new product idea." The company might slow an idea down or decline to fund a venture team, but it didn't shoot its pioneers. Pioneers get shot at, so they need support. No support systems, no champions. No champions, no innovation.

Herb Kelleher understood that the real danger wasn't rejecting a bad idea. It was discouraging the next one. At Southwest Airlines, employees could submit ideas to anyone and expect a response within a week. A simple no was unacceptable; rejections came with explanations. "If you consistently turn down ideas, you won't get any more," he explained. The objective wasn't to approve every suggestion. It was to ensure that the person whose idea failed today would still bring forward the one that might succeed tomorrow.

The important distinction isn't between criticism and no criticism. It is between challenging the idea and humiliating the person. "What would have to be true for this to work?" is very different from "that's stupid." One invites another thought. The other ensures the next thought stays silent.

The Contrarian's Signal

Some founders came to read ridicule almost as a compass. Mallaby's The Infinity Machine describes Demis Hassabis testing his vision for an AI start-up on Patrick Winston, the revered head of MIT's Computer Science and AI Lab. Hassabis explained he was going to do reinforcement learning and deep learning. Winston said it was nonsense.

Hassabis thought this was kind of fantastic. If the establishment had embraced the idea, it might have signalled a lack of originality and rival entrepreneurs would soon be circling. When he founded DeepMind in 2010, fellow scientists rolled their eyes and almost every investor turned him away.

Others found the same signal. Bill Ackman was told it was a stupid idea to start a hedge fund straight out of business school, which, he says, is how he knew it was a good one. Brian Chesky noticed that big ideas can sound so stupid at the beginning that you can share them freely because people dismiss them. Alex Karp describes Palantir's early years simply: "We were the freak show."

But ridicule proves nothing. Plenty of ideas are laughed at because they deserve to be. Mallaby supplies the necessary caveat: "A contrarian with no following is merely an oddball." Mockery doesn't validate an idea. It tells you almost nothing about it either way.

Somebody Has to Believe

Jared Diamond tells a story about Columbus that is really about how many doors an idea needs. Columbus wanted a fleet to sail west across the Atlantic. His backers at home thought it stupid. So did the French. So did the king of Portugal. So did one Spanish duke, then another. The king and queen of Spain said no. On the seventh attempt they relented and gave him three small ships.

Diamond's point is that Europe was fragmented, so Columbus had many chances. In a single unified kingdom, one no might have been the end of it.

Organisations and capital markets work the same way. The more places an unusual idea can be heard, the more chances it has to find the one person willing to fund three small ships. It is the single door, the one committee, the one boss who sneers, that makes fragile ideas easy to lose.

Phil Knight's advice to founders was to let everyone else call your idea crazy and keep going. Henry Ford thought it no bad thing to be a fool for righteousness' sake: such fools usually live long enough to prove they were not fools, or their work does.

Seeing What Others Can't

This may explain why a small group of investors keep backing pioneers when everyone else passes. They aren't necessarily braver or more reckless. They are using a different measuring stick. Most investors judge a new business against the paradigm it is trying to replace, and on that measure it often looks worse. The pioneer investor asks: if the new paradigm arrives, what does this become?

Elon Musk is an obvious example. In 2003, by his own account, electric cars were regarded as the stupidest thing ever, little more than golf carts. Musk first came to Tesla as an investor, leading its early funding round when judging the company by the existing automotive industry made it look absurd. He wasn't underwriting the car Tesla could build that year. He was underwriting a world where the car itself had changed.

Hassabis found his believer too: when almost every investor turned DeepMind away, Peter Thiel was among the few who didn't. Baillie Gifford and Baron Capital built a large Tesla position years before the rest of the market came around.

The other side of the ledger matters. For every pioneer who reshapes an industry, many more are simply wrong, and imagination without discipline is expensive optimism. The lesson isn't that foolish-looking ideas are unusually likely to succeed. It is that appearance is a poor screening mechanism.

The investors who capture truly large outcomes can hold a new paradigm in their heads before it is visible to everybody else. If even Edison couldn't see what the phonograph would become, the investor who sees further than the market doesn't need to be right every time.

Crazy Ideas, Small Bets

Michael Bloomberg understood the organisational side of this extraordinarily well. When he started a business making financial information accessible by computer, everyone thought he was crazy. That's not the way the industry works, he was told.

He didn't want employees believing their jobs were at risk because something they worked on failed. He wanted as many new ideas as possible, including crazy ones: "If a concept is flawed, the blame and pain rest with me. The credit for whatever's right goes to them."

Think about the incentive that creates. You can take a shot or try something unconventional without attaching your career to the result.

Bloomberg wasn't advocating betting the company on every crazy idea. He has noted that his company's significant advances were mostly evolutionary, small earned steps rather than giant lucky hits. The two ideas fit beautifully. Think unconventionally. Experiment conservatively.

Most crazy ideas are not Yahoo. Most experiments fail, and most weird products don't become Red Bull. The answer isn't to fund every dream with unlimited capital. It is to create cheap ways to find out.

Marc Randolph, the co-founder of Netflix, describes entrepreneurship in almost exactly these terms: take the apparently bad idea, find a quick and inexpensive way to test it, watch what happens, adjust and try again. He can't think of a successful company that succeeded with its original idea. Netflix spent more than eighteen months and hundreds of failed experiments before settling on a model that worked.

It is very different from the traditional corporate approach. One asks a committee to decide whether something will work. The other asks reality.

Let Reality Vote

That may be the real secret. Instead of endless debate, create an experiment.

George Bodenheimer was often asked to describe ESPN's business strategy, the same ESPN the networks had dismissed as a laughingstock. His answer was disarmingly simple. We try a lot of things. The things that don't work, we stop doing. The things that do work, we keep improving. "That's our strategy."

Peters and Waterman thought this was the most important expression of the bias for action in the successful companies they studied. "There is absolutely no magic in the experiment," they wrote. "It is simply a tiny completed action, a manageable test that helps you learn something, just as in high school chemistry."

What struck them was how many large institutions had forgotten how to do it. They preferred analysis and debate and were paralysed by fear of failure. In the excellent companies, experimentation was cheap learning, often less costly and more useful than sophisticated market research or careful staff planning.

Jim Sinegal used this philosophy at Costco. If Costco wanted to try a product but didn't yet have the volume to buy it on the economics it ultimately expected, it might price the item as though it had bought it properly, put it in two or three locations, and see whether customers responded. The downside was tiny and the information valuable.

The question wasn't can we prove this idea is correct?

It was can we cheaply learn whether we're wrong?

Ingvar Kamprad hoped IKEA would never have two identical stores. The latest was bound to have several things wrong with it, but it would still be the best yet. "Why," he said, would remain an important key word.

Lots of Tries

The deeper lesson is about numbers. Peters and Waterman put it plainly: no matter how small the odds of any one thing working, the probability of something succeeding becomes high if you try lots of things.

3M didn't make a few big bets; its people made hundreds of little ones in specialised markets. McDonald's ran more experimental menu items, store formats and pricing plans than its competitors. Scott Cook made it an Intuit tenet: "Try more things than you know are going to work." Wait until you're sure and it's too late.

Against this stands what Peters and Waterman called the "home-run only" mentality: a misplaced faith in planning and large scale and an inability to manage organised chaos and lots of base hits. The adaptive company works in a Darwinian way. It fosters mutations, kills dumb ones quickly and invests heavily in what works. Jim Collins reached much the same conclusion: much of what looks retrospectively like brilliant foresight was really "Let's just try a lot of stuff and keep what works."

Jeff Bezos has said Amazon's success is a function of how many experiments it runs. In his 2018 letter he went further: as a company grows, the size of its failed experiments has to grow too. Amazon would be experimenting at the right scale if it occasionally had multibillion-dollar failures, because one large winning bet can cover many losers.

Experiments only work if failure is survivable for people too. Tim Cook describes Apple trying to fail internally rather than externally, developing things and deciding not to ship them. Kent Taylor went further. On his office wall at Texas Roadhouse he displayed artifacts from each of three stores he opened in 1994 and later closed. In cultures that punish risk-takers, failures get hidden. Taylor put his on the wall.

If It Ain't Broke

Foolishness isn't only needed at the beginning. Success creates its own conventional wisdom, and the loudest objections to the next idea can come from inside the company that proved the last one right.

John H. Patterson, once ridiculed for selling "the cash register nobody wanted," later warned his own company: "The business that is satisfied with itself … is dead." C. William Pollard of ServiceMaster called it the arrogance of success: believing what you did yesterday will be sufficient tomorrow.

When Ford's production reached one hundred cars a day, some stockholders were seriously alarmed. When he said he hoped soon to make a thousand a day, they were "inexpressibly shocked" and considered court action. The temptation to stop and hang on to what one has, Ford observed, is natural.

Bezos wrote in 2014 that Marketplace, Prime and AWS were each bold bets at first, and sensible people worried they couldn't work.

Eli Broad called innovation a permanent revolution. If Kaufman and Broad had remained simply the company that built homes without basements, someone would eventually have done it better. The best place to look for the next move, he argued, was the industry's most basic assumptions, precisely because they had gone unexamined for so long.

When Foolish Becomes Obvious

Once something works, we rewrite history.

The Walkman seems inevitable now, but it wasn't. Akio Morita recalled that Sony's own engineers and marketing people were dubious. He couldn't convince his own project team and was embarrassed to be so excited about a product others thought would be a dud. Morita took personal responsibility for pushing ahead.

The existing framework produced the wrong question: Why would anyone buy a cassette recorder that doesn't record?

The better question was: Would people value portable music?

Millions had already bought car stereos that couldn't record.

John Bogle encountered the same problem in investing. His great innovation was a mutual fund whose objective wasn't to beat the market. It would simply own it. The original First Index Investment Trust raised only $11 million and became known as "Bogle's Folly," derided for years and not copied for nearly a decade. Today index investing sits at the heart of global asset management.

William Osler captured it beautifully: "The foolishness of yesterday has become the wisdom of tomorrow."

Success removes the uncertainty that preceded it, and for investors that is dangerous. We study great businesses after their models have been validated and assume the attractive features were always visible. Usually they weren't.

The early investor had to hold two competing possibilities in mind at once:

This might be stupid.

And this might be enormous.

That is a much harder place to stand.

The Investor's Problem

Investing naturally pulls us toward certainty. We build forecasts, study comparable companies, calculate market sizes, analyse historical margins and construct valuation frameworks. All useful, but they can become anchors.

A genuinely new business may have no comparable company. The addressable market may not yet exist. Current margins may tell you little about mature economics, and the product may create behaviour rather than merely serve an existing one.

There is a psychological trap too. Howard Marks has written about Mistakes Were Made (but Not by Me) and cognitive dissonance: when new evidence challenges a position we already hold, unconscious mechanisms help us preserve it. Once an investor has decided an idea is silly, every stumble confirms it and every sign of traction becomes easy to explain away.

None of this means abandoning discipline. Plenty of unusual ideas are terrible ideas. The harder task is not confusing unfamiliarity with impossibility.

For an investor, perhaps a better starting question than does this fit the existing model? is:

What would have to be true for this to work?

Then look for evidence. Are customers responding? Are unit economics improving? Is management learning? Does the founder change the tactics while remaining stubborn about the core insight? Can the opportunity be tested without risking the company? Is the market really too small, or does today's market simply reflect the limitations of today's business model?

There is another implication. Markets tend to reward legibility. A company with a known market, known margins, comparable companies and predictable economics is easy to underwrite — which also means lots of investors can underwrite it.

A genuinely new model has a wider range of possible outcomes. Most may be poor. But where the downside is bounded and one branch of the distribution is enormous, certainty isn't necessarily required. You don't need high confidence when the payoff is sufficiently asymmetric and the cost of finding out sufficiently small.

That is as true for an investor as it is for the company making the experiment.

What I Take From It

The more I read these stories, the more a handful of ideas keep resurfacing.

New ideas are fragile. The status quo arrives with history, evidence, budgets and supporters, while the new idea often arrives with little more than a hunch and looks worse than what it hopes to replace. The biggest ideas are hardest to see because the world that will make them valuable doesn't exist yet.

Ridicule is more dangerous than disagreement. Strong organisations can debate fiercely without making people afraid to bring forward the next unconventional thought. And an idea needs more than one door; the single gatekeeper loses ideas that a more plural culture would keep.

The absence of precedent cuts both ways. Sometimes nobody has done something because it is a terrible idea. Sometimes nobody has done it because nobody has done it yet.

Experimentation is how you find out which.

Try lots of things. Keep the bets cheap relative to what you can afford to lose. Stop what fails. Keep improving what works. Failure should be survivable, for the company and for the person.

The technology of foolishness isn't the ability to know which crazy idea is right. It is the ability to remain uncertain long enough, and cheaply enough, to find out.

George Leonard tells the story of Jigoro Kano, the founder of judo, asking near the end of his life to be buried in his white belt, the emblem of the beginner. Leonard first read it as humility, then came to see it as realism: life makes beginners of us again and again.

His conclusion is one of my favourite lines on the subject:

"To be a learner, you've got to be willing to be a fool."

The same is true of organisations.

* Visit the Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER

The Business of Access

Some of the greatest businesses in history were not built by inventing something entirely new. They were built by taking something desirable, useful or aspirational that already existed and putting it within reach of millions of people who had previously been excluded.

Sometimes the barrier was price. Sometimes knowledge, complexity, distribution or convention. Often it was simply that the incumbent industry had decided certain people weren’t worth serving.

The great democratisers saw things differently.

Democratisation Is Not Cheapening

Ingvar Kamprad described IKEA as part of a “gigantic project of democratisation.” The company’s purpose was not merely to sell cheaper furniture, but to make the kind of quality products once affordable only to the rich available to everybody else.

Giorgio Armani arrived at much the same idea from the opposite end of the market. He spoke explicitly about the “democratisation” of fashion. After establishing one of the world’s great luxury houses, he deliberately turned towards young people and those who loved fashion but couldn’t afford his main line. The launch of Emporio Armani in 1981 shocked people around him. Casual clothes, denim, lower prices. Critics feared he was diluting the brand, perhaps even destroying the exclusivity that made Armani desirable in the first place.

Armani saw no contradiction.

“I am well aware that style and elegance are everywhere, not only in the upper social classes,” he later wrote.

Lew Frankfort came to a similar conclusion at Coach. Having studied Louis Vuitton, he told his executives he wanted Coach to become a “democratized version of European luxury in America.” Vuitton might appeal to the top one percent of households; Coach could reach the top twenty. Frankfort’s insight was that luxury didn’t have to mean prohibitively expensive.

Frankfort eventually preferred the phrase accessible luxury. It is a useful distinction. Democratisation is not the same thing as cheapening a product. Often the real trick is preserving what makes something desirable while removing the obstacle that keeps most people from enjoying it.

Frankfort was, without necessarily knowing it, describing exactly what Rolex had already built.

Business historian Pierre-Yves Donzé identifies this as one of Rolex’s core competitive advantages: the identification of an entirely new market, what he calls “accessible luxury” — a segment that kept the social signalling of classic luxury while closing the distance that price had always placed between that world and the middle class.

The watches remained expensive. But they were never out of reach: a dream product an ordinary consumer could hope to acquire one day, at a time when Patek Philippe and Vacheron & Constantin were still building small-batch pieces by hand for the “happy few.”

Tadashi Yanai describes Uniqlo’s mission as the “democratisation of clothing.” “We want to sell good clothing to all people, not just the few,” he has said. The objective wasn’t simply cheap clothing, but high-quality clothing at prices almost anyone could afford. IKEA approached furniture much the same way. It kept design and function but changed sourcing, packaging, transport, store format and even who assembled the furniture.

That pattern turns up remarkably often in business history.

The Flywheel of Lower Costs

Almost 200 years ago, Cornelius Vanderbilt became America’s richest man not by serving the richest Americans, but by dramatically lowering the cost of transportation for everyone else. His competitors in the steamboat business largely assumed there was a natural number of passengers travelling between two cities. Cut fares and all you did was fight more aggressively for the same pool of travellers. Vanderbilt believed the pool itself could grow. Make travel cheaper and people who previously stayed home would start travelling.

That sounds obvious now. It wasn’t then.

Vanderbilt could pursue the strategy because he was obsessed with efficiency. “If I could not run a steamship alongside another man and do it as well as he for twenty percent less than it cost him,” he said, “I would leave the ship.”

Lower costs allowed lower fares. Lower fares brought more passengers. More passengers created scale, and scale helped lower costs again. A flywheel, long before anyone called it one.

John D. Rockefeller would eventually build an even greater fortune on much the same principle. Standard Oil’s relentless attack on refining, transportation and distribution costs helped send the price of kerosene dramatically lower, bringing reliable illumination within reach of more households. The attraction was not simply that Rockefeller could produce more cheaply than competitors. It was that he understood the enormous demand that could emerge when a useful product became affordable to ordinary people.

Henry Ford was even more explicit.

“Every time you reduce the price of the car without reducing the quality,” he said, “you increase the possible number of purchasers.”

Ford once calculated that cutting the price of a car from $440 to $360 could expand annual demand from roughly 500,000 buyers to perhaps 800,000. Less profit on each car, perhaps, but more cars, more workers, more scale and ultimately more profit.

The automobile industry at the time was still largely organised around wealthy customers. Ford’s ambition was to build a car “for the great multitude.” He understood that the absence of middle-class car buyers did not prove middle-class people didn’t want cars. It proved that cars were too expensive.

“We took what was a luxury and turned it into a necessity,” he later said.

Ford Car Prices & Production 1909 - 1921 [Source: ‘My Life and Work,’ Henry Ford, 1922.]

Seeing Customers Before They Exist

That may be one of the defining characteristics of a great democratiser: they see customers before the customers exist.

A.P. Giannini saw them in banking.

The traditional San Francisco banks largely catered to established businesses and wealthy customers. Giannini’s Bank of Italy - which later became Bank of America - went after immigrants, labourers, shopkeepers and farmers — people who were often intimidated by banks, kept cash at home and sometimes relied on loan sharks. Where established bankers saw deposits too small to matter and loans too small to justify the paperwork, Giannini saw relationships that might last a lifetime.

“The little fellow is the best customer that a bank can have,” he told his people.

It is an extraordinary sentence because the prevailing banking model suggested precisely the opposite. The little fellow looked uneconomic. Giannini changed the economics.

Branching brought the bank closer to customers. Longer hours made it more convenient. Small loans brought people into the financial system who had previously been excluded. The incumbent saw a $25 loan; Giannini saw millions of potential customers.

This pattern repeats. The customers ignored by the incumbent can become the market of the disruptor.

The Humbling of Products

Milton Hershey found them in chocolate. Before Hershey, chocolate remained largely a luxury product. By applying mass-production techniques, he helped turn it into something ordinary families could buy regularly. Frank Woolworth did the same with consumer goods. His stores became famous for offering “articles which were once luxuries” for five and ten cents.

Sears was built on much the same idea. Its history describes the process as the “humbling of products” — the efficient distribution of previously unattainable things to what it wonderfully called the “huge pools of human desire called markets.” The automatic washing machine, once owned only by the rich, was democratised by Sears in 1942: $37.95, with three dollars down and four dollars a month thereafter.

Neither lesson was simply “sell things cheaply.” Woolworth understood that low price without quality was a dead end; the company’s history records his view that it would be fatal to sacrifice quality for price.

When the Barrier Isn’t Price

Home Depot took the idea a step further. Bernie Marcus and Arthur Blank realised that price wasn’t the only thing preventing people from improving their homes. Knowledge was a barrier too. The professional tradesman knew what to buy and how to use it; the ordinary homeowner often didn’t.

“We gave customers the knowledge to do it themselves at the right price,” Blank wrote. He pointed to a striking example: a customer could install a Mills Pride kitchen for $3,000 that twenty years earlier might have cost $25,000 and required a professional.

Home Depot wasn’t simply taking sales from existing hardware stores. By combining lower prices, enormous product choice and knowledgeable staff who taught customers how to do the work themselves, it expanded the population capable of undertaking home-improvement projects in the first place.

That is another form of democratisation: sometimes the barrier isn’t what something costs, but whether the customer has the knowledge or confidence to participate at all.

Reinvest in Lower Prices

IKEA’s Kamprad then did something many businesses find psychologically difficult: he gave much of the efficiencies back. Former IKEA CEO Anders Dahlvig noted that purchasing savings were repeatedly reinvested in lower customer prices rather than simply harvested as higher margins. The objective was to grow the customer base, even when doing so meant sacrificing some short-term profit.

Charlie Munger admired this broader instinct in Costco and GEICO. He said both companies seemed to feel a “holy duty” to provide a wonderful product at a very low price. Plenty of companies claim to offer value; far fewer build the desire to continually push price down and quality up into the “body and soul” of the organisation.

Buffett saw the same thing at Nebraska Furniture Mart. Mrs. B and her family bought brilliantly, operated at expense ratios competitors couldn’t match, and passed much of the saving back to customers. Buffett called it an ideal business: exceptional customer value producing exceptional economics for the owners.

There is a counterintuitive lesson here. If you possess a cost advantage, the obvious temptation is to keep it. Raise the margin. Report the earnings. Enjoy the spread.

The great democratisers often do something else. They reinvest the advantage in the customer.

Lower prices bring more people into the market. More customers increase scale. Scale creates purchasing power, operating efficiencies, brand awareness and distribution density, which can fund another round of lower prices or better service. The margin sacrificed today can become the moat tomorrow.

Liberating the Market

Juan Trippe understood the same principle in aviation. Pan Am became synonymous with glamorous international travel, but Trippe’s ambition was much larger than carrying the wealthy across the Atlantic. He pushed continually for lower fares and greater aircraft capacity because he believed international flying could become a mass-market activity. The Boeing 707 and, later, the enormous 747 were not simply technological achievements; they changed the economics of a seat crossing an ocean.

The same logic Vanderbilt had applied to a steamboat now operated six miles above the earth.

Herb Kelleher later watched it play out at Southwest Airlines. He recalled entering city-pair markets where perhaps 125,000 people flew each year and watching traffic grow towards a million once Southwest introduced low fares, frequent service and convenience. Kelleher didn’t describe this as taking market share. He said Southwest had “liberated” people, allowing them to fly for business and personal reasons far more often than before.

That word is revealing. Liberated. It is the language of removing a constraint.

Aspirational, Not Exclusive

Coach provides another variation. Unlike transportation, banking or household goods, luxury derives some of its appeal from exclusivity itself. Lew Frankfort's insight was that aspiration did not have to disappear simply because the product became more accessible. Coach could remain premium while reaching millions of consumers who could never contemplate traditional European luxury. Frankfort wrote that while traditional luxury was exclusive, Coach could be inviting. A Louis Vuitton handbag might signal that its owner had arrived; Coach could appeal to a woman who was still on her way.

That is democratisation at a subtler level. The challenge isn't simply widening access. It's widening access without destroying the aspiration that made the product desirable in the first place.

Armani did the same with Emporio Armani. Critics imagined luxury as a finite pool of exclusivity: if too many people gained access, prestige would disappear. Armani instead recognised that style was not confined to wealth. There was a vast population of younger consumers who cared deeply about fashion but were excluded by the economics of the traditional luxury house. He didn’t need to persuade them to care. They already cared. He simply needed to let them in.

From Products to Capital

The same idea eventually reached Wall Street. Charles Merrill believed investing should not remain the preserve of wealthy insiders. “We must bring Wall Street to Main Street,” he said, “and we must use the efficient, mass merchandising methods of the chain store to do it.”

Merrill Lynch opened branches across America, advertised aggressively and educated ordinary people about stocks. The objective was not merely cheaper brokerage; it was what Merrill's son later called “demystification” — making Wall Street intelligible and accessible to the small investor.

Charles Schwab would later push the same democratisation further through discount brokerage, while Satya Nadella has described Microsoft's original raison d'être as democratising computing.

Henry Kravis has used exactly the same language at KKR:

“We spend a lot of time on a new area that we all came up with, and that’s a democratized product, which means that we’re enabling a retail investor to invest in the KKR product just like an institutional investor has been able to do for years.”

Again, the underlying investment capability already existed. The innovation was widening access to it.

Sizing a Market That Doesn’t Exist Yet

And that brings us to something especially relevant for investors.

We spend a great deal of time estimating total addressable markets. We take the number of existing customers, multiply it by some price or penetration assumption and build a spreadsheet around the result.

But what if the existing market is only the market permitted by the existing business model?

Reid Hoffman makes the point directly: when estimating market size, investors need to consider how lower costs and product improvements can expand the market by attracting new customers, not simply taking share from existing ones. Aaron Levie put it even better: sizing a disruptive market from the incumbent market can be like sizing the automobile industry by counting the number of horses in 1910. The current market may tell you very little about the eventual one.

Every business in this essay was assessed twice: once by the incumbent, who saw a customer too poor, too uninformed or too small to bother with — and once by the founder, who saw the same person as the market.

The spread between those two assessments is where the return lived.

A $10,000 product may have one million customers. At $1,000 perhaps it has ten million. But price is only one constraint.

The most valuable customer may be the one who isn’t a customer yet.

That is why I find the democratisers so interesting. They tend to combine several characteristics we often look for separately: relentless efficiency, customer orientation, willingness to sacrifice some current margin, scale economies, intelligent distribution and an unusually expansive view of the market.

More than anything, they refuse to accept the industry’s definition of who the customer is. The great democratiser asks a different question:

Who would become a customer if we removed the thing keeping them out?

Business history understandably celebrates the inventor — the person who creates something the world has never seen before. But another kind of entrepreneur has created just as much value: the one who takes something already wonderful and asks why so few people get to enjoy it.

The breakthrough isn’t always invention. Sometimes the breakthrough is access.


* Visit the Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER


The Barnacles on the Hull

Richard Farmer had a favourite way of explaining costs at Cintas. He told his people to imagine a new ship entering the water.

“When a new ship is put into the water, it has a clean hull,” Farmer explained. “It moves fast and is highly manoeuvrable. Nothing is holding it back.”

Leave it in port for a year, though, and things change. “Barnacles accumulate on the hull. They slow the ship down, require more power to run, and reduce manoeuvrability because of the drag.”

“Whether we know it or not, we’ve got barnacles,” Farmer told his people. “Your job is to find those barnacles and scrape them off.” He would give examples: “buying things that you decided you needed 10 years ago and you don’t need them anymore. Or having somebody prepare a report that was very important to you five years ago, but now you no longer need it. But they’re still preparing it for you. That’s a barnacle. People we’ve outgrown or are occupying positions that are no longer needed—they’re barnacles too.”

None of these things is likely to sink the ship. That’s precisely the problem. They accumulate slowly. A report becomes a process, the process requires a person, the person eventually becomes a department, and the department creates meetings, budgets and reports of its own.

Before long, yesterday’s nimble company needs far more people, money and effort just to hold its speed.

Watching the Pennies

Warren Buffett once said that “a good manager must be a demon on costs.” Costco’s Jim Sinegal described the job as continual: “You have to continually find ways to reduce expense and to improve productivity.”

Some of the world’s great businesses have taken that idea to almost comical extremes.

François Michelin understood the signalling effect of small costs. Michelin famously turned envelopes inside out so they could be used again. “To save a million envelopes a year is important,” he insisted. But his real point was cultural: how could Michelin ask factory workers to save a gram of rubber per tyre if office workers weren’t also being asked to save a gram of paper?

That was why Michelin’s own frugality mattered. He reused defective road maps for internal memos and lived simply — wearing frayed suits, flying economy and taking the Paris Métro — “personifying the virtues he wished to apply to his managers and workers.”

Ingvar Kamprad took much the same approach at IKEA. Despite becoming a billionaire, he continued to travel standard class and lived with what biographer Bertil Torekull described as a “total lack of external finery” — no grand clothes, smart watches or luxury cars.

“Low price is written into our business idea as an essential condition for our success,” he wrote. Delivering low prices was impossible without low costs.

Hyundai founder Chung Ju-yung made frugality equally explicit. “Our company motto is ‘diligence, frugality, affection,’” he said. Like Michelin, Chung insisted employees use both sides of a sheet of paper, but his deeper concern was the example set at the top: “I’ve never come across a company that thrives under a luxury-loving, wasteful owner.”

Fastenal founder Bob Kierlin was similarly obsessive. He drove an Oldsmobile, furnished his office with used furniture, typed his own correspondence and had no personal secretary. Even his suits were second-hand. “Luckily, we’re the same size,” Kierlin told a reporter after buying six used suits from the manager of a clothing store for $60 apiece. “Either you do a good job of cost control in all aspects of your business, or you start losing it.” Eventually, Kierlin said, frugality became so ingrained that he didn’t even have to think about it. It became an attitude.

John D. Rockefeller carried the instinct throughout his life. “The world’s richest man never lost the thrifty boyhood habits that had made him the nonpareil of American business,” Ron Chernow wrote. Rockefeller could spend a ridiculous amount of time protesting bills both large and small, but his philosophy was captured in a much simpler instruction: “Save when you can and not when you have to.”

It’s easy to be frugal when circumstances leave no alternative. The more revealing test is whether the habit survives when the necessity disappears.

What Does the Customer Get?

The point of all this penny-pinching isn’t simply to accumulate more pennies.

J.C. Penney understood that from the beginning. “Our first customers were people who took the saving of so much as a penny seriously,” he recalled. “To save pennies for them I had to save them for myself.” He meant it literally: wrapping paper and string were reused, bent nails were straightened, and envelopes were opened carefully so their blank sides could serve as scratch paper.

But the savings weren’t intended simply to fatten the bottom line. “Savings — far from being used to line our own pockets — were passed on to our customers, in the real Golden Rule way.”

Don Keough found a broader version of the same test at Coca-Cola. To combat bureaucracy, he tried to reduce every expense, department and project to one basic question: “Will this help to create and serve customers?” If the answer wasn’t a ringing yes, whatever Coca-Cola was spending or undertaking had to go.

Keough’s explanation of what happened otherwise is even better: “Once you decide you have fifty things to do that are unrelated to your customer, soon you have fifty bureaucracies composed of individuals doing things extremely well that they shouldn’t have been doing because it didn’t serve the customers in any way.”

That’s the danger: the people may be talented, the department well run and the work performed exceptionally well. It just shouldn’t exist.

Buffett has made essentially the same point about Berkshire. Its managers don’t submit budgets to him, Berkshire doesn’t spend time producing consolidated monthly figures simply because large companies traditionally do, and Buffett’s explanation is wonderfully straightforward: “We don’t do unnecessary things around Berkshire. And a lot of stuff that’s done at big companies is unnecessary.”

Michael Moritz recalled Don Valentine applying a similarly brutal test to young companies. Valentine would clamp onto burn rates and circle G&A on the income statement in green. Moritz wrote that Valentine believed “anything not closely associated with either directly making, building, marketing or selling a product was a waste of money.” He would latch onto any function or person he thought impeded the rapid advance of the business and reserved particular scorn for bureaucracy and the people who created it.

Keough’s test forces the business back to first principles: Does it help create or serve a customer?

Never Add the Unneeded

People may be the most difficult barnacle of all, which is why the best companies seem particularly careful about adding them in the first place.

Buffett has long rejected the familiar corporate cycle of hiring enthusiastically when business is good, only to slash headcount when conditions turn. “We neither understand the adding of unneeded people or activities because profits are booming, nor the cutting of essential people or activities because profitability is shrinking.” Berkshire’s goal, he said, was simple: “Never to add the unneeded.”

Elsewhere he put it even more plainly: “I don’t think you can ever find a statement that Charlie and I have ever made, in terms of Berkshire’s companies or anybody else’s, where we said that there should be more people working than are needed in a company.”

Tom Murphy built much the same philosophy into Capital Cities: “In terms of culture, we told our employees that we hire the smartest people we can find and that we have no more of them around than necessary.” Sam Walton was blunter still: “We always ran a real tight organization. We had no excess people.”

Tom Peters and Robert Waterman captured part of the reason in In Search of Excellence: “As the number of people in a company goes up arithmetically, the number of possible interactions among them goes up geometrically.” More people bring more complexity. Beyond a surprisingly small size, they warned, “diseconomies of scale seem to set in with a vengeance.”

There’s a humane logic underneath the financial one. ServiceMaster’s Bill Pollard used to say the company would “rather buy a baby grand piano than hire or assign one unnecessary person.” If the piano was no longer needed, it could be chopped up. “But we cannot do that with people.”

The easiest time to accumulate unnecessary people is when profits are booming and nobody is particularly interested in questioning another salary.

Percy Barnevik had a wonderfully simple way of fighting this at ABB: don’t assume that someone leaving creates a vacancy that needs filling. “The replacement of employees who resign should always be examined closely, during financial boom times and recessions alike.” Each departure was an opportunity to ask whether the position would be created today if it didn’t already exist. If managers disagreed, Barnevik suggested leaving the job vacant for six months and seeing what happened.

If this position didn’t already exist, would we create it today?

Don’t add the unneeded in the first place.

Frugal Isn’t Cheap

But there’s another side to the argument. Some expenses deserve more money, not less.

Leonard Lauder was famously frugal. His wife liked telling stories about him complaining that she took taxis to visit Estée Lauder stores in Brooklyn. “Why can’t you take the subway?” he’d gripe. But the next part of Lauder’s explanation is what matters: “Because our overhead was so low, we could afford to use — in fact, we could insist on using — expensive ingredients.”

That’s the distinction. Cheap companies minimise expenditure. Great frugal companies spend as little as possible on things the customer doesn’t value so they can spend generously on the things they do.

Labour provides perhaps the most counterintuitive example. Bain & Company’s Fred Reichheld, creator of the Net Promoter System, observed,“It sounds like a good idea to minimise labour cost, but in order to maximise the potential for value creation, a business must find ways to pay its best people more than the competition.” He went further: “one of the best ways to cut costs (as a percentage of revenues) is very often to increase compensation opportunities, counterintuitive as that may sound.”

Phil Fisher had made much the same observation back in 1958. He suggested investors pay close attention to wage scales. A company earning above-average profits while paying above-average wages was likely to have good labour relations. But when “a significant part of earnings comes from paying below-standard wages,” Fisher warned, the investor “may in time have serious trouble on his hands.”

James Lincoln had demonstrated the economics decades earlier at Lincoln Electric. His workers earned enormous performance bonuses, yet because they were so much more productive, Lincoln Electric spent proportionally less on total labour than its major competitors — even after bonuses that could exceed 100 percent.

Aldi discovered much the same thing. Karl Albrecht relentlessly preached two things: control costs and hire the best people. A former Aldi UK CEO recalled Albrecht’s instruction to “turn the penny three times before you part with it.” There was “no cost too small not to concentrate on,” but that didn’t mean avoiding investment.

Aldi deliberately paid higher salaries because better people required less supervision, exercised greater autonomy and produced more. “Investing in really good people was not a way to save money; reducing the salaries of people was never a way to save money.” Despite paying some of the industry’s highest salaries, labour consumed roughly 3 percent of sales against 7 to 8 percent at a typical supermarket.

Source: ‘My Life and Work,’ Henry Ford 1922.

Joe Coulombe reduced the whole idea to a sentence at Trader Joe’s: “Good people pay by their extra productivity. You can’t afford to have cheap employees.”

Les Schwab reached the same conclusion when lower-priced competitors appeared. He considered cutting benefits and salaries and pulling the savings back to headquarters. “Sounds good, but it doesn’t work that way.”

Schwab went the other direction. “We increased wages, we changed and improved our medical, dental and insurance programs. We increased our cash bonus.” The result was better people, better service and greater productivity. “I don’t think our percentage wage cost was any higher than our competition because our people just plain ‘put out more.’”

The important number isn’t what an employee costs. It’s what the business gets in return.

Good Costs, Bad Costs

Accounting doesn’t make that distinction particularly well. An unnecessary corporate meeting is an expense, but so is employee training. A private jet is an expense, but so is research and development. Another management layer is an expense, but so is advertising that strengthens a brand for decades.

Buffett has pointed to Coca-Cola as an example. Some of the enormous sums it spends on marketing and advertising are treated as current expenses, but economically part of that spending is creating a long-term asset, much as capital expenditure creates a factory.

David Packard understood the same distinction at Hewlett-Packard. “One of our most important management tasks is maintaining the proper balance between short-term profit performance and investment for future strength and growth.” HP routinely spent 8 to 10 percent of sales on R&D, sometimes more, because “good new products are the lifeblood of technical companies such as ours.”

The opposite mistake can be equally damaging. Panera’s founder, Ron Shaich, has described what happens when restaurants facing falling sales try to protect the P&L by “ripping out labor hours and cutting food cost.” He calls those savings “a tax on the customer.”

“Longer waits, dirty tables, slower service, and more frazzled team members all add up to a negative customer experience that will undoubtedly undermine already falling sales and intensify a cycle of decline.”

Fred Reichheld makes the broader point: “Managers should be skeptical of any cost reduction scheme that doesn’t include a credible strategy for the enhancement of customer retention — which means a credible strategy for improving customer value.”

The income statement calls all these dollars expenses. The customer knows the difference.

The Expensive Trappings of Success

Frugality is easiest when there’s no money. The harder test comes after success.

Tom Murphy said Capital Cities developed its bare-bones culture because the company nearly went bankrupt twice in its early years. “We had to go back to the original stockholders twice for additional money. As a result, we always ran the operation with a very limited number of people. We never had any more people than we absolutely needed. I think we had fewer people than we really needed.”

The remarkable part was that when the financial pressure disappeared, the behaviour didn’t. “Over time, that barebones culture stayed with us.”

Barclay Simpson carried much the same instinct into Simpson Manufacturing. Like many of the generation that came of age during the Depression, Simpson had internalised what his biographer described as a “stern frugality.” The shabby plant and office facilities in San Leandro reflected “his deep and continuing preference for substance over show,” while his battered, dusty cars and refusal to allow himself special luxuries became a source of amusement — and respect — among employees.

But there was a principle underneath it. As one colleague put it, “Barclay hates to waste a nickel of shareholder money.” Simpson was the sort of man who would take the bus from JFK into downtown rather than pay for a cab, and “that applies to all aspects of his leadership style.”

That’s an important way of thinking about corporate frugality. The money being spent isn’t really management’s money. It belongs to the owners of the business, and treating a corporate expense account differently from your own wallet is itself a small agency problem.

Kamprad understood the signalling problem too. He attacked luxurious company cars, first-class flights, separate executive dining rooms and other privileges not because eliminating them would transform IKEA’s economics, but because management couldn’t credibly preach cost consciousness while exempting itself. “No, this is a question of our credibility.”

Success normally works in the opposite direction. Profits rise, headquarters expands, travel improves, assistants acquire assistants and things previously considered luxuries slowly become necessities. The business hasn’t necessarily become badly managed; it has simply accumulated barnacles.

There is a deeper force at work here. Max DePree, the longtime head of Herman Miller, once described one of management’s hardest jobs as “the interception of entropy.” By entropy, he meant simply that “everything has a tendency to deteriorate.”

David Cote saw the same force at Honeywell: “Over time all organised systems evolve towards chaos. Unless you pursue change relentlessly, your efforts will eventually wither away.”

Farmer’s barnacles were another way of describing the same phenomenon. Left alone, organisations don’t naturally become simpler. They accumulate.

A Permanent Revolution

The worst time to develop a cost culture is when you suddenly need one.

Buffett put it beautifully: “Whenever I read about some company undertaking a cost-cutting program, I know it’s not a company that really knows what costs are all about. Spurts don’t work in this area. The really good manager does not wake up in the morning and say, ‘This is the day I’m going to cut costs,’ any more than he wakes up and decides to practice breathing.”

David Cote made the same point at Honeywell. His goal was not periodic cost cutting, but to keep fixed costs under control as the company grew. “Constant, sustained process improvement is vital for any company seeking to win today and tomorrow,” he wrote. The gains rarely came from one dramatic action. “It’s the habit of process change — the undertaking of numerous, sustained changes over time — that counts.”

Cote understood the compounding involved. A business improving productivity by 3 percent a year rather than 1 percent may not look dramatically different after twelve months, but over a decade the gap becomes enormous. At Honeywell, that meant hundreds of small changes to processes, repeated year after year, allowing more revenue to pass through an increasingly efficient cost base.

Costs compound quietly. So do improvements.

Marathon Asset Management expressed much the same idea: “Almost every firm engages in bouts of cost cutting. Exceptional firms, however are involved in a permanent revolution against unnecessary expenses.”

When cost cutting becomes urgent, the danger is that management cuts what can be cut rather than what should be cut — people, training, maintenance, R&D, customer service or marketing. Things that looked expensive on yesterday’s income statement but may have been creating tomorrow’s revenue.

Charles Schwab’s observation is worth remembering: “You can’t cut a company to greatness.”

The objective isn’t to periodically slash expenditure. It’s to prevent unnecessary expenditure becoming part of the organisation in the first place.

Necessity, the Mother of Invention

There is another benefit to keeping a business lean: constraints can make it better.

“Starting when you don’t have a lot of breathing room can breed a great culture of discipline,” Chris Davis observed. Sam Walton saw exactly that at Walmart. “Many of our best opportunities were created out of necessity,” he wrote. “The things that we were forced to learn and do because we started out under financed and undercapitalized in these remote, small communities.”

Dame Stephanie Shirley reached much the same conclusion building her software company. “Our lack of financial muscle was, on the whole, an advantage.” With little access to capital and next to no fixed assets, the company couldn’t afford to get ahead of itself. “We grew only when our market grew. I hired people only as I needed them.”

What looks like a disadvantage can impose a useful discipline. Abundant capital allows a company to hire ahead of demand, subsidise uneconomic products, add layers of management or solve problems by throwing money at them. Scarcity forces a different question: is there a better way?

Jeff Bezos has argued that this is precisely why frugality can drive innovation: “One of the only ways to get out of a tight box is to invent your way out.” Or, as William Walsh put it more simply in The Great A&P, “Necessity has always been the mother of invention.”

The objective isn’t deprivation for its own sake. A business starved of necessary investment eventually damages itself, just as one flooded with capital can lose its discipline. The advantage lies in having enough constraint that people are forced to think before they spend.

Sometimes the tight box produces the better answer.

The Investor’s Takeaway

Frugality doesn’t show up neatly in a discounted cash flow model. Margins offer clues, but sometimes the most frugal company deliberately passes its savings to customers. Headcount ratios help, but businesses differ. Corporate overhead can be compared, yet even that captures only part of the story.

The evidence is often qualitative. What does headquarters look like? How does management travel? Does headcount automatically rise with revenue? Does the company pay highly productive people more or simply search for cheaper people? Does management talk about costs only when earnings disappoint, or is cost consciousness simply part of how the place operates?

Most revealingly, what happens to the money saved?

At J.C. Penney, saving pennies inside the business meant saving pennies for customers. At Estée Lauder, low overhead paid for better ingredients. At Aldi, thrift elsewhere helped pay for better people. At Hewlett-Packard, today’s expense funded tomorrow’s products. And at Simpson Manufacturing, the nickel not wasted was understood to belong to the shareholder in the first place.

These companies weren’t simply minimising costs. They were trying to distinguish between expenditure that strengthened the business and expenditure that merely made the organisation larger, more comfortable or more complicated.

Which brings us back to Farmer’s ship.

Barnacles don’t arrive all at once. No captain wakes one morning to discover that a clean hull has suddenly become covered in them. They accumulate slowly beneath the waterline while the ship keeps moving. At first nobody notices the drag.

Businesses are much the same. Success creates resources, resources create comfort, comfort creates complexity, and complexity quietly attaches itself to the organisation until yesterday’s nimble company requires steadily more people, money and effort to keep moving at the same pace.

Farmer understood that the answer wasn’t an occasional voyage into dry dock. DePree understood it as the interception of entropy. Rockefeller understood it when he said to save when you can rather than when you have to.

The best businesses keep asking whether the people, projects, expenses and processes accumulated along the journey are still helping the ship get where it needs to go.

You don’t scrape the hull just once.

The Dolphin and the Anchor

In 80 CE, the Roman emperor Titus minted a coin with a strange little emblem on the reverse: a dolphin coiled around an anchor. It was already an old visual pun for balancing speed and restraint — one Augustus, a century earlier, had prized so highly he'd made festina lente, "hasten slowly," his personal motto, warning his generals that nothing wrecked a campaign faster than an impatient commander. The dolphin was speed. The anchor was what kept that speed in check.

It's an odd thing to put on money, until you realise money is exactly where the lesson gets ignored most often. Growth is the dolphin — fast, visible, the thing everyone wants more of. Discipline is the anchor — unglamorous, easy to resent, and the counterweight that keeps speed from becoming recklessness. Business history is largely a record of companies that struck the balance and companies that cut the anchor loose.

Why Growth Matters

Start with the case for the dolphin, because it’s real. Warren Buffett has made the point plainly: assemble a portfolio of businesses whose earnings march upward year after year, and the portfolio’s market value will follow. Phil Fisher said much the same in 1958 — the companies worth a long-term investor’s attention are the ones that keep growing. Chuck Akre puts a number on it: compounding an owner’s capital at 20% a year simply requires a hefty level of growth underneath it. Even Benjamin Graham, the field’s most famously conservative voice, conceded that a growing company’s stock, bought at a fair price, is obviously preferable to the alternative. Buffett himself has drawn the line more bluntly still: “If you really think a business is declining, most of the time you should avoid it. The real money is going to be made by being in growing businesses, and that’s where the focus should be.”

The reason is almost mathematical. Compounding is one of the most powerful forces available to an investor, and it’s inseparable from growth: without earnings that are actually expanding, there’s nothing to compound. Buffett has stated the ceiling on that relationship bluntly: “the inescapable fact is that the value of an asset, whatever its character, cannot over the long term grow faster than its earnings do.”

Words Chosen Carefully

Charles Schwab has never been shy about the objective.

“I believe it is incumbent on every leader of a company that the number one thing on their mind is growth. You don’t prosper without it.”

He’s right. Growth matters. Businesses that stop growing eventually run out of opportunities to reinvest, attract talented people and create value for their owners. But the best operators almost never stop at the word growth. They qualify it.

Publix calls it “controlled growth.” Howard Jenkins framed it as the direct result of pleasing customers, never a target chased for its own sake. Brunello Cucinelli calls it “gracious growth” — 8 to 10 percent, by design, with investors warned off before they’d even bought a share if they wanted more. Discount Tire’s mandate is to “grow responsibly” — eighty to a hundred stores a year are within reach, but only forty to fifty are actually opened, the gap maintained deliberately. Lynsi Snyder describes In-N-Out as growing “at a calculated pace” — no restaurant opens until the leaders needed to run it properly already exist.

None of these operators are arguing against growth. They’re arguing against the version of the word that arrives without an adjective attached to it.

A company can grow by buying revenue, slashing prices or stretching its balance sheet. It can also grow by delighting customers, reinvesting at high rates of return and expanding only when its culture and people are ready. The headline number may be identical. The longer-term outcome rarely is.

That’s the difference between the dolphin and the anchor. The dolphin provides the speed. The anchor ensures that speed is taking the business somewhere worth going.

Tailwinds: The First Test

The best growth doesn’t fight the market it’s in — it finds the one already moving, and lets the wind do the work.

It rides a genuine tailwind. Even Warren Buffett took decades to fully absorb this one. Writing to shareholders in 1977, he admitted that one of the lessons his own management had learned — and, in his words, "unfortunately, sometimes re-learned" — was the importance of being in businesses where tailwinds prevail rather than headwinds.

Dan Davidowitz at Polen has noted that the firm's biggest winners all had decades-long opportunities in front of them — the job was never to time the wave, just to judge how long it would keep rolling. Lone Pine'sDavid Craver ties the moat and the tailwind together into a single test: a business worth owning needs a moat around it and a secular tailwind behind it.

And sometimes tailwind alone isn't enough — the market still has to be big enough to matter. Netflix founder, Reed Hastings applies his own test here: go after the smallest market that can still hold five to ten years of growth ambition. Too narrow — his example is the left-handed scissors market — and there's no runway at all, however strong the trend. Disney’s Bob Iger got the same warning early in his career, scrawled on a note from a colleague: avoid the business of manufacturing trombone oil. You could become the greatest manufacturer in the world, the note read, and it still wouldn't matter — the world only consumes a few quarts of it a year. Iger kept the note in his desk for decades, pulling it out whenever a team at Disney pitched a project that was more craft than opportunity.

Peter Keefe of Rockbridge Capital treats it as a rule with no exceptions in his own experience: every mega compounder he's owned had a long secular tailwind behind it. Paul Black of WCM Investment Management frames the acknowledgment itself as a matter of honesty — wanting a tailwind is simply how life works, and anyone who pretends otherwise about its importance to success isn't being straight with themselves. Chris Begg of East Coast Asset Management puts the alternative in blunt, practical terms: a business facing secular headwinds becomes what he calls a three-decision company — you have to get the buy right, the sell right, and then work out where to redeploy the capital — and he'd rather not sign up for the extra decisions.

Ian Cassel has a physical image for why this matters so much. A tailwind, he points out, behaves like the jet stream for a commercial flight — a westerly wind above 30,000 feet, sometimes over 100 mph, that can turn a six-hour crossing into four and a half without the aircraft working any harder or burning any more fuel. Investing without a tailwind is possible, in the same way flying without one is possible. It's just a great deal more effort for the same destination.

The Anchor: What Restrains Healthy Growth

Pride in the Wrong Thing.

Jeff Bezos put it as plainly as anyone has: he didn't want Amazon taking pride in being big — he wanted it taking pride in servicing customers, on the logic that doing that well is what drives the growth in the first place.

That instinct runs against a deep current in the psychology of the job. William Thorndike has noted the pull working against every CEO: bigger companies draw more press, their executives earn more, and they're more likely to be invited onto prestigious boards. Bigness feeds the ego in ways that discipline never does — which is exactly why a company proactively choosing to stay smaller than it could be is so rare.

Peter Kiewit made this the founding rule of his own contracting firm decades earlier: the aim was to be the best, he told his people in 1961, "but not necessarily the biggest." Dinosaurs, he liked to point out, were the biggest land animals that ever lived, and being biggest didn't save them — smaller, more effective competitors outlasted them by tens of millions of years.

Sol Price, who founded Price Club, the direct precursor to Costco, put the same instinct more bluntly: "Bigness is a serious danger. Pretty soon one is trying to control the animal instead of keeping the stores exciting."

Chasing size directly tends to produce sprawl. Pursuing quality and discipline, with a real tailwind behind you, tends to produce size as a by-product.

When the Dolphin Runs Without the Anchor

Cut the anchor loose and the pattern is depressingly consistent, across completely unrelated industries. Jim Collins' research into companies that fell from greatness found the same root cause again and again. Almost none of them failed from complacency, he concluded — they failed from overreaching, "the undisciplined pursuit of more." Success bred a kind of hunger: now we just need to have more, and we need to be bigger.

In his later work on 10x companies, Collins found the same pattern in reverse — the winners routinely "left growth on the table, always assuming that something bad lurked just around the corner," while their less successful peers pressed for maximum growth in good times and got caught overextended the moment conditions turned.

Starbucks is the textbook case. From 425 stores in 1994 to a new opening every ninety minutes by 2007, same-store sales collapsed under the weight of its own expansion. Six hundred stores closed. Twelve thousand jobs went with them. Howard Schultz's own verdict, written to his team afterward, was unambiguous: "growth, we now know all too well, is not a strategy. It is a tactic. And when undisciplined growth became a strategy, we lost our way."

Patagonia found itself in a milder version of the same trap. Yvon Chouinard admitted his company had "exceeded its resources and limitations," becoming dependent — like the broader economy it operated in — "on growth we could not sustain."

Financial companies show the failure mode in a more dangerous form. Charlie Munger put the paradox bluntly: financial institutions tend to make Berkshire nervous precisely when they're trying to do well — which sounds backwards until you watch it happen. As the RBA's Chris Kent has put it, wherever something is growing fast is one of the first places to look for financial stability risk.

Behind the Balance Sheet has observed that the fastest growers in finance are frequently the ones whose sudden stumble later reveals a fraud or a collapse in underwriting standards. The reason is almost mechanical: Buffett has pointed out that National Indemnity could write a billion dollars of business in a single month whenever it wanted — all it would take is offering silly prices, and brokers would find the company in the middle of the ocean at four in the morning.

Chris Davis, whose own fund is built entirely around financials, names the payoff of that trick plainly: underprice risk and "money will find you," letting you produce almost any growth rate you like for a while — a strategy that "typically leads to disaster."

GEICO lived that disaster in the 1970s: underwriting standards deteriorated as the company chased policy count, and losses eventually reached $124 million, nearly sinking it. J.P. Morgan’s Jamie Dimon puts the same mechanism in plainer terms — growth "can force you to take on bad customers/clients, excess risk, or excess leverage."

Dunkin' Donuts ran a version of the same play with real estate instead of underwriting. Robert Rosenberg later admitted the pressure to open stores pulled the company away from its discipline of building the brand market by market — "it was pure numbers, pure growth. Quality suffered." Tom Monaghan's account of building Domino's is more candid still: the company forced rapid growth deliberately, he said, "so we could impress the financial community" ahead of taking it public.

Enterprise Rent-A-Car offers a third example of the same failure: service quality quietly breaking under the weight of speed. Andy Taylor has been direct about the mechanism: expanding too fast damages customer satisfaction, and that damage "spreads everywhere and causes reputation problems." He's admitted the company lived this firsthand in the early 1980s, when confidence tipped into overreach — revenues grew more than 30 percent a year, and the company, in his own words, "got a little ahead of" itself, putting people into roles they weren't ready for and opening branches in the wrong places.

The trap deepens once growth stops being a by-product and becomes the operation itself. Rick Vanzura, formerly of Panera, has warned that growth should be the by-product of delivering great products and services that drive demand — and when growth for its own sake becomes the primary focus, that's a red flag. The machine has to be fed: the store roll-out has to hit its numbers, the loan book has to keep expanding, the next acquisition has to close, all to keep Wall Street satisfied.

David Rolfe of Wedgewood Partners has pointed out that growth by acquisition is often the most common route companies take to hit those numbers — and, not coincidentally, the one most fraught with abuse, citing Enron, Tyco, and WorldCom as the cautionary extremes. What started as a business built on real fundamentals ends up run for the sake of the growth rate itself, with the fundamentals an afterthought.

Growth outpaces Culture.

The businesses that resist this trap tend to share one instinct: they let people, not ambition, set the pace. Truett Cathy built Chick-fil-A by deliberately capping how many new stores opened each year, refusing to let strong financials override his insistence on developing operators who actually shared his values first. Lynsi Snyder at In-N-Out describes the same discipline as growing "only as fast as we can develop quality leaders" — expansion as a byproduct of people, never the goal itself.

Bernard Arnault runs one of the largest luxury conglomerates on earth at a growth rate most public-company boards would consider modest — 8 to 10 percent a year — and has said plainly that the goal was never growth for its own sake, but desirability. Costco'sJim Sinegal put the constraint in almost identical terms: the company built every one of its warehouse managers internally over a decade or more, and simply refused to open faster than that bench could support.

David Packard, co-founder of Hewlett-Packard, had a rule that holds up remarkably well: no company can grow revenue faster, over the long run, than it can grow its bench of good managers. Percy Barnevik said almost the same thing about running ABB's factories across fifteen countries — talent, not markets or capital, was always the real constraint.

Reid Hoffman has a sharper way of naming what happens when this discipline slips: medicine has a word for growth that outruns its own structure. It's called cancer.

When Growth Is the Right Bet

None of this is an argument against growth — quite the opposite.

The distinction the best investors draw isn't growth versus no growth — it's earned growth versus manufactured growth. Baillie Gifford's own research across nearly three decades of global markets found a persistent pattern: companies in the top quintile for earnings growth outperformed the broader market by a wider margin than every quintile below them, in a fairly clean, monotonic relationship.

What Investors Should Look For

Is growth outrunning the culture and the infrastructure behind it? Does management ever say no to growth? Do they seed new locations with veterans, or throw newly hired outsiders at the problem? Is the bench of leaders growing at least as fast as the store count, the branch count, the loan book?

How is the growth being funded? Internally, through disciplined reinvestment of cash the business already earns — or externally, by stretching the balance sheet, loosening underwriting, or issuing stock to paper over the gap?

Is management chasing size, or letting size follow? The best operators talk about market share, store count, or assets under management as a result, not a target. The moment "biggest" becomes the stated ambition — rather than "best," or "most trusted," or "highest quality" — is usually the moment the anchor gets cut loose.

Growth should be the by-product of doing the right things well — never a target imposed from outside, and never something to chase merely because the market rewards the dolphin and rarely asks about the anchor.

Two thousand years later, investors still celebrate the dolphin and overlook the anchor. Markets reward speed quarter by quarter; compounding rewards discipline decade by decade. Titus put both on the same coin because neither was meant to exist without the other. The great businesses understood that too. They hastened slowly.

Waiter or Owner

Picture two people standing in the same restaurant, watching the same rival open across the street.

In the first version, you own the place. A competitor selling the same food has just set up shop across the road, and it feels personal — a threat to your money, your reputation, your family's future. You notice whether its tables are full. You study its menu. You watch its prices. You wonder what it's doing better, because your livelihood is tied to what happens inside your restaurant.

In the second version, you're the waiter working the same tables. The new restaurant barely registers. If anything, it's good news: one more employer bidding for your time.

An executive at AB InBev once used that contrast to explain how the company thinks about management, as recounted in Ian Cassel's Intelligent Fanatics Project: "Many companies inadvertently create waiters," he said. "We work tirelessly to create restaurant owners."

It's a simple story, but it captures something real about the businesses that keep outperforming for decades rather than years. Most companies say they want employees to think like owners — to care about waste, protect the brand, serve customers well, control costs, work together and make decisions for the long term. Then they pay them like hired hands, withhold the information owners would receive and deny them the authority to change anything.

The best companies see that contradiction and refuse to live with it. They don't merely tell people to act like owners. They give them a piece of the economics, a clear view of how the business works and enough authority to influence the result.

They create owners.

A Piece of the Action

The idea is not new.

In 1927, UPS founder Jim Casey offered shares in the company to key employees. At the time, employee ownership was unusual. Many large businesses were still run through rigid hierarchies, with capital at the top and labour at the bottom.

Casey saw something different.

"There is no bigger incentive than for someone to work for himself," he said when presenting the shares.

Employee ownership became one of the defining features of UPS. Drivers, managers and executives accumulated stakes in the company. The shares encouraged frugality, loyalty and attention to detail because each improvement belonged, at least partly, to the people making it.

Casey later described employee ownership as the principle that had contributed more than any other to building UPS. By the time the company prepared to go public in 1999, employees and retirees still owned roughly two-thirds of its outstanding shares. Every executive officer had more than twenty-five years of service and had accumulated a meaningful ownership position.

The ownership and the tenure reinforced each other. People stayed because they shared in the value being created. The longer they stayed, the more knowledge and ownership they accumulated. That knowledge helped create more value, which made staying more attractive still.

Publix developed a similar model. George Jenkins opened his first Florida grocery store in 1930 and built it into the largest employee-owned company in America — today more than 1,400 supermarkets and roughly 250,000 staff, with no public market in the stock. Jenkins wanted the people running the stores to participate in the profits they generated and in the value of the wider company. Full-time store employees share directly in the profits of their location, and Publix contributes a substantial portion of company profits to a retirement trust for eligible associates.

The arrangement did more than supplement wages. It gave employees a direct interest in whether shelves were stocked, customers returned, waste was controlled and the store prospered. As former Publix CEO Ed Crenshaw put it:

"When people have ownership of something, they do what it takes to improve the value of that ownership."

Publix doesn't call the people who work there employees. It calls them associates — or, as the company puts it, co-owners. That mindset sharpens under pressure. Crenshaw described what happens when a competitor opens nearby: sales take a hit, and because associates share directly in store profits, they feel that hit as well — which is exactly why they work harder to keep the customer in front of them.

Every thirteen weeks, Publix also pays out a fifth of each store's profits in cash directly to the people who work there, on top of the company-wide retirement trust. The incentive reaches all the way to the register, not just the boardroom. The result shows up in a number most retailers never get close to: Publix's annual voluntary turnover runs around 5 per cent, against an industry average nearer 65 per cent.

The pattern appears repeatedly across many of the world's best businesses. O'Reilly Automotive makes every employee a shareholder after six months. Wawa, Brown & Brown and Kiewit have each built their own versions of the same philosophy.

At Walmart, Sam Walton gave employees a financial stake in the company. By the time he wrote his autobiography, more than 80 per cent of Walmart associates owned shares directly or through profit sharing. Walton called it "the single smartest move we ever made." Not a new store format, not a distribution centre, not a purchasing system, but sharing the economics.

When the Factory Worker Becomes a Millionaire

One of the clearest modern examples is HEICO. For decades, the Mendelson family has used company stock in HEICO's retirement plan to spread ownership throughout the organisation. The opportunity is not confined to senior executives. It reaches factory workers, shipping clerks, technicians and administrative employees.

Laurans Mendelson spoke proudly about employees who became millionaires — and in some cases multimillionaires — because of the HEICO shares they accumulated. That result matters for reasons beyond personal wealth.

A factory worker who owns meaningful stock does not experience a quality problem in quite the same way as someone collecting only an hourly wage. A shipping clerk who participates in the company's long-term success has another reason to care whether an order arrives correctly and on time.

"They take a personal pride in being a HEICO team member," Mendelson explained.

The ownership tells employees something important: you are not merely a cost appearing in someone else's income statement. You helped create this value, and you deserve to participate in it.

Howard Schultz made the same point at Starbucks. Giving employees shares, he said, demonstrated that the company respected its people enough to share its success with them. That may be the deepest effect of broad ownership. It changes not only incentives but relationships. There is a difference between being told that people are the company's most important asset and being invited to share in the wealth they help create.

Share the Profits

Ownership does not always require publicly traded shares or a formal employee stock ownership plan. Sometimes the most powerful incentive is a direct share of the profits employees can personally influence.

Enterprise Rent-A-Car was built around that principle. Founder Jack Taylor believed managers should participate directly in the economics of the branch they operated. The logic was straightforward. Suppose an employee creates $100,000 of additional value and receives ten per cent, or $10,000. Suppose instead that the employee creates $1 million and receives $100,000. Which outcome should the owner prefer? Obviously the second.

"The more you make, the more the business makes," Taylor explained. "Why wouldn't I want that to happen?"

Yet many companies resist precisely that outcome. They worry about employees earning too much rather than asking how much value had to be created for those earnings to become possible. Taylor understood that a large employee bonus can be excellent news for shareholders when the underlying incentive is designed properly.

Barclay Simpson used a similar system at Simpson Manufacturing. Salaries were relatively ordinary, but employees could earn substantial bonuses when their branch performed well.

"If they have a really good quarter, they can get a ton of money," Simpson said.

He regarded that as a feature, not a problem. Employees became highly focused on branch profitability because their own compensation moved with it. The company also discovered that the arrangement created loyalty. Even when the financial crisis reduced sales and profits, most of Simpson's people stayed.

Les Schwab approached profit sharing with characteristic simplicity: "My thinking has always been, if I give away half the profits, I still have half left," he wrote. "If I share $10 million with people, I still have $10 million left." The point was not charity. Schwab believed sharing profits helped produce the profits available to be shared.

Lincoln Electric has applied the same philosophy for generations. A large portion of pretax earnings is placed into a bonus pool for employees. The system has survived recessions, industrial disruption and technological change because the reward is tied to productivity and long-term company performance. At Johnson Wax, S.C. Johnson reached the same conclusion: "I truly believe we are a high-performing company because of profit sharing. Our earnings are better because of it."

Keep the Incentive Close to the Work

Not every ownership plan works. A tiny amount of stock buried in a distant retirement account may have little influence on the decision an employee makes this afternoon. A company-wide bonus can feel equally remote when an individual has no idea how their work affects the final result. The strongest systems create a clear line between action and outcome.

Expeditors International does this through district-level incentives. Employees are rewarded according to the success or failure of the local district in which they work.

That proximity changes behaviour. Every shipment matters. Every customer interaction matters. Every unnecessary expense matters. Employees know their actions can influence the result and that the result can influence their compensation.

"How are we different?" former CEO Jeffrey Musser asked. "The employees of Expeditors treat the business as if it were their own."

The district structure makes ownership understandable. People are not being asked to improve the abstract earnings per share of a global corporation. They are being asked to improve a business they can see, serving customers they know, alongside colleagues whose work affects the same pool.

The old J.C. Penney partnership model worked in much the same way. Penney would first place a potential manager in a trial store. If the person demonstrated the ability and character to operate it successfully, they could become a partner with a one-third ownership interest. Before being permitted to finance an interest in another store, however, the manager had to train someone capable of replacing them. The system combined ownership, accountability and people development.

A manager could prosper, but only by building a store that prospered and developing another person capable of carrying it forward. The reward sat close to the result.

Ownership Without Shares

Literal equity is powerful, but some companies create an owner mentality even where employees do not own significant stock.

Vicki Tenhaken found the same pattern studying companies that had survived for a century or more. In Lessons from the Century Club Companies, she put it plainly: "Many of the Century Club companies engage in some type of profit-sharing, employee ownership, or participatory management practices. Even without any type of formal ownership, employees in these companies develop an ownership attitude – it's their company."

At Walgreens, Charles Walgreen encouraged store managers to think of themselves as independent retailers supported by a large organisation — not employees controlled by one. Store managers were close to customers, knew their local markets and had room to exercise judgment. The result was an unusually strong sense of ownership and remarkably low turnover among managers.

In-N-Out asks store managers to run each restaurant as though it were their own. Home Depot historically encouraged store leaders to tailor parts of the product range to local conditions. TopBuild tells field leaders to "Be the Owner." Amazon has made ownership one of its foundational leadership principles. Andy Jassy describes an owner as someone who asks: What would I do if this were my own money?

That behaviour cannot be produced by equity alone. It comes from authority — being trusted with real decisions — which managers tend to repay with the same pride, care and accountability an owner brings to something that is genuinely theirs.

A Stock Certificate Is Not Enough

Herman Miller understood that ownership had to be supported by something deeper. The company described three values attached to ownership: business literacy, equity and spirit.

Business literacy meant employees had both a responsibility and a right to understand the company. They needed access to the real situation — not vague encouragement or carefully managed corporate messaging. Equity meant sharing the positive and negative consequences of collective performance. Spirit meant commitment to the company, its goals and one another.

Herman Miller summarised the model in six words: "Innovation and excellence through participative ownership." The important word is participative. Ownership without information leaves people guessing. Ownership without authority creates frustration. Ownership without a meaningful economic stake becomes symbolic. Ownership without shared purpose can become individual greed.

Jack Stack discovered the same thing at SRC Holdings. After helping employees acquire an ownership stake, Stack taught them how the business actually worked. Workers learned to read financial statements, understand cash flow and see how inventory, pricing, productivity and collections affected the value of the company. The shares were only part of the system. People also needed to understand how that wealth was created.

"A company of owners will outperform a company of employees any day of the week," Stack said. Not because owners possess a certificate. Because ownership changes the way people notice, decide and act.

The Responsibility of Ownership

Ownership is often described as a reward, but it also creates responsibility. Max DePree of Herman Miller argued that owners cannot simply walk away from problems. Ownership increases accountability and demands maturity. It requires people to become more informed about the whole business rather than only their small part of it. That distinction matters.

Poorly designed incentives can produce the opposite of ownership. A sales commission may encourage someone to book a bad customer. A branch bonus may encourage underinvestment. Stock options can reward a rising market rather than genuine value creation. A distant company-wide target may encourage employees to assume someone else will carry the load.

The best systems balance reward with responsibility. They give people enough authority to act, enough information to judge and enough exposure to consequences to care. This is why employee ownership appears so frequently beside decentralisation, internal promotion and long tenure. The mechanisms reinforce one another.

A company promotes someone who understands the operation. It gives them responsibility for a branch, store or division. It lets them participate in the profits they create. The employee stays, develops judgment and accumulates ownership. Eventually, they teach the next person to do the same. The organisation compounds human capability alongside financial capital.

Ownership Polices Itself

There is a further benefit that rarely shows up on an income statement, though it quietly shapes one.

Brian Chesky has argued that the stronger a company's culture, the less corporate process it needs, because a strong culture means you can trust people to do the right thing without a rulebook standing over them. Herb Kelleher made the same point about Southwest Airlines: create an environment where people genuinely participate, and control becomes unnecessary, because they already know what needs to be done. The more people commit willingly, the fewer hierarchies and control mechanisms the business requires.

The effect is not only top-down trust. It is lateral pressure. Writing in the 1970s, the investor Phil Fisher observed that the pressure a peer group places on a tardy or lazy colleague dwarfs anything a manager could impose from above. John Mackey built Whole Foods around small, self-managing teams for the same reason: when every person's contribution is visible and everyone shares in the outcome, there is nowhere for a free rider to hide, because the team polices itself. Les Schwab saw it on his own shop floor — when pay was tied to shared results, a man dragging his feet heard about it from his own colleagues long before a manager had to step in.

Fred Reichheld described this as the underlying mechanics of partnership: a system in which everyone is motivated to create value together tends toward self-governance and self-correction. Partners do not need to be told what to do, because protecting the pool of value they all share is already their job.

For a public company, this shows up as leaner overhead — fewer layers of supervision, less need for process, lower cost of running the business — not because standards slip, but because the workforce is already keeping itself honest.

Private Equity Discovers the Same Thing

It is one thing to see this pattern in family businesses and founder-led companies that have practised it for a century. It is another to see a private equity firm — an industry not historically associated with generosity toward the workforce — arrive at the identical conclusion through hard data.

I've long admired Pete Stavros, Co-Head of Global Private Equity at KKR, for founding Ownership Works, a nonprofit dedicated to broadening equity ownership among employees and equipping them with the tools, data and transparency needed to understand and drive business success.

"Sharing stock ownership with workers and building 'ownership cultures' has proven time and again to be a win-win initiative," Stavros has said. "Ownership cultures work. Happier, more engaged employees lead to stronger businesses with more cohesive cultures and better returns."

KKR now has more than fifty portfolio companies applying the Ownership Works model. The early results are striking. KKR has reported roughly 4x returns in companies that adopted the model, compared with roughly 2.5x for its typical investments. Equity ownership is not a zero-sum game. Private equity earned its reputation in the 1980s through leverage and in the 1990s through roll-ups and conglomeration. Today, one of the most overlooked sources of value creation may simply be giving the people doing the work a meaningful stake in the value they create.

The Investor's Takeaway

For investors, the question is not simply whether executives own shares. That information is easy to find and already widely studied.

The more revealing questions sit further down the organisation. Do store managers participate in store performance? Do branch leaders understand the capital employed in their operation? Do frontline employees share in the wealth they help create? Is ownership broad or confined to the executive suite? Can employees see how their decisions affect customers, costs and cash? Are they trusted with enough authority to make those decisions matter? And when management says it wants people to act like owners, has it given them any reason to do so?

The answers may help explain why some companies retain exceptional people, control costs without bureaucracy, serve customers with unusual care and continue improving long after a charismatic founder has left.

Once again, none of this fits neatly into a discounted cash flow model. Employee ownership can create dilution. Profit sharing appears as an expense. Decentralised authority can look untidy. Paying an employee an unexpectedly large bonus may even trouble investors focused on next quarter's margin. But the best owners understand the trade. They are willing to divide the value more broadly when doing so enlarges the value available to divide. They know the difference between giving wealth away and sharing wealth with the people who helped create it.

Most companies already have plenty of employees. The exceptional ones build something more powerful.

A company of owners, not waiters.


* Visit the
Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
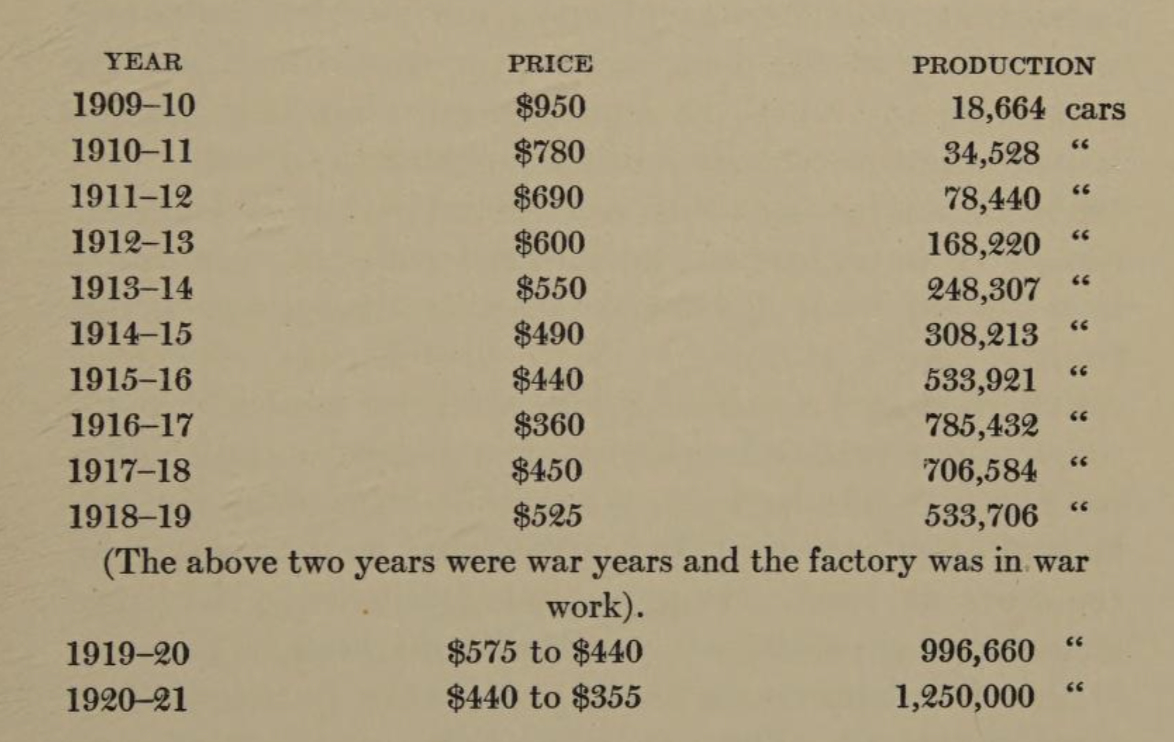
The Floor to the Boardroom

Ron Vachris started at Costco forty years ago as a forklift driver. He unloaded pallets, worked the floor, learned the business one job at a time — merchandising, operations, real estate — for four decades, before eventually becoming the company's CEO. There was no shortcut through the middle. He walked the whole path.

It's tempting to read that as a nice story about one particular warehouse, one particular career. It isn't. Pull on that thread and you find the same walk — floor to office to boardroom — repeating itself in company after company, industry after industry, country after country, decade after decade. Not as an inspirational exception. As a well-worn path that the world's best-run businesses seem to build on purpose.

Not One Factory. A Pattern.

Collect enough examples and a remarkable pattern emerges. The companies are different, the industries unrelated, the decades far apart—but the same leadership path keeps appearing. It shows up in American retail (Costco, Publix, Wegmans), in industrial manufacturing (Illinois Tool Works, Sherwin-Williams, Simpson Manufacturing, US Steel under Elbert Gary), in logistics spanning three continents (FedEx and UPS in the US, DHL International out of Hong Kong, Mainfreight out of New Zealand), in Scandinavian and German manufacturing (IKEA, Hästens, and Würth), in Australian finance (Macquarie Bank), and in businesses a century apart in age — from Henry Ford's early auto plants and Endicott Johnson's shoe factories in the 1910s, to modern compounders like Constellation Software, Danaher, and O’Reilly Automotive today.

USAA, Lincoln Electric, Kiewit, Fastenal, Enterprise Rent-A-Car, Discount Tire, Les Schwab, Bloomberg, Wawa, QuikTrip, Mars, Patagonia, Tractor Supply, Old Dominion, Marriott, Four Seasons, Stew Leonard's, Procter & Gamble, Panda Express, In-N-Out, ALDI, Texas Roadhouse, Svenska Handelsbanken, A.J. Gallagher, Greggs, ABC Supply, Toyota, Jack Henry & Associates — and, as I found sitting down with its leadership recently, Cintas.

Even Berkshire Hathaway fits the pattern. Robert Miles, in The Warren Buffett CEOs, found that all but one of Berkshire's subsidiary CEOs had been promoted from inside the business.

That's not a random assortment of "nice culture" companies loosely sharing a value statement. It's a genuine cross-section of some of the best long-term compounders in business history, and the thing they keep independently arriving at is this: the walk from the floor to the top isn't incidental to how they got great. It may be the mechanism itself.

Why it Works

1. It preserves what actually makes the company good.

Phil Fisher made this case as far back as 1958, in Common Stocks and Uncommon Profits, writing that "the company with real investment merit is the company that usually promotes from within." He returned to the idea nearly two decades later in Conservative Investors Sleep Well (1975): companies of the highest investment order develop policies and ways of doing things peculiar to their own needs, and if those ways are truly worthwhile, it is "always difficult and frequently impossible" to retrain someone long accustomed to doing things differently. The higher up the newcomer sits, he noted, the more costly that indoctrination becomes — which is why, in his observation, "a surprising number of executives brought in close to the top tend to disappear after a few years." He went further: bringing in outsiders near the top is frequently a "damning sign" that something is already broken, no matter how clean the recent earnings look.

Jim Collins found the same pattern empirically in Built to Last and Good to Great: across seventeen hundred combined years of company history in his visionary companies, he found only a handful of instances of hiring a CEO from outside. Comparison companies went external roughly six times more often — and underperformed accordingly.

2. It's the ultimate incentive system.

Nearly every operator quoted here says some version of the same thing: people stay, work harder, and take more ownership when they can see a real path to who they could become. It's one thing to be told the company values you. It's another to watch the person running the warehouse today, knowing they once pushed the same cart you're pushing now — that's proof, not a promise. Chester Cadieux of QuikTrip framed it sharply — you can train competence, but you can't train commitment, which is exactly why promotion from within matters more than raw skill.

Discount Tire is now one of America's largest independent tire retailers, with well over a thousand stores, and it built that scale on a single unbroken rule: nobody, at any level, gets the keys to a store without starting out busting tires. Founder Bruce Halle held himself to the same standard. "If I were to bring someone in at a high level without having worked in the stores," he said, "I may as well get in my car, drive around to the stores, and slap every one of the guys in the face."

Les Schwab Tire ran the same experiment for thirty-four straight years and never once broke the rule: not a single manager or assistant manager was hired from outside. Every one of its 250-plus managers earned the job the same way — starting at the bottom, changing tires.

Fastenal put it plainly in a 2022 company statement: "More than 95 percent of our current branch General Managers have been promoted from within, and that trend continues all the way to the top. In fact, nearly all of our senior leaders worked their way up from entry-level positions." Founder Robert Kierlin has said it's the thing he's proudest of building at the company — the opportunity it gives ordinary people to excel, most of them starting with little expertise in the product line before working their way up.

3. It compounds knowledge and culture

Every new outside hire at a senior level is, in effect, a double write-off — years of institutional knowledge walking out the door, replaced by someone who has to relearn not just the business but the culture, often imperfectly. O'Reilly Automotive is perhaps the starkest example of this (more on that below). Jim Sinegal made the same point about Costco: every warehouse manager running the company's stores had spent ten, twelve, fifteen years inside the business before getting there. The pattern held all the way to the top — Craig Jelinek started as a Costco warehouse manager in 1984 and rose through operations for two decades before becoming CEO, and his successor, Ron Vachris, began as a forklift driver forty years before taking the job, working through nearly every operating role in between. It's the same logic as compounding capital, just applied to people instead of dollars.

Patagonia founder Yvon Chouinard captured the logic in a single sentence: "As much as possible we hire from within, to keep the company culture strong." The point isn't simply to retain talented employees; it's to preserve the habits, judgement and standards that have compounded inside the business for decades.

4. It develops better operators.

Danaher's internal data (via an HBR case study) found roughly three of every four senior promotions were filled internally, with about a fifth of senior managers promoted every year — a deliberate, almost mechanical pipeline rather than a policy applied occasionally. Vicki Tenhaken's research into "Century Club" companies — firms that have survived over a hundred years — found the same thing: leadership development from within wasn't incidental to their longevity, it was one of the core mechanisms behind it.

Henry Ford described his own leadership team in the same spirit, and it reads almost like a roll call from the factory floor: the head of the whole operation started as a machinist, the man running the giant River Rouge plant began as a patternmaker, another senior department head started as a sweeper. "There is not a single man anywhere in the factory who did not simply come in off the street," Ford said. National Cash Register's early history offers the cautionary flip side — founder John Patterson tried repeatedly to hire star talent from outside, and by the company's own account, every one of those hires failed. The people who actually built the business were the ones who came up through the ranks.

Tom Peters found essentially the same pattern decades later studying America's top-performing companies for In Search of Excellence: "value-infused top-performing companies are led by those who grew up with the core of the business — electrical engineering at HP or Maytag, mechanical engineering at Fluor or Bechtel. The star performers are seldom led by accountants or lawyers."

George F. Johnson, of Endicott Johnson, framed the logic almost as a matter of dignity: "Why should I hire a manager of a plant who is a stranger to the workers — a man who comes from outside to take a job at the top and talk down to them from a height?" It's worth noting what that philosophy actually built: under Johnson, Endicott-Johnson grew into the largest shoe manufacturer in the world during the 1910s and into the early twentieth century, run top to bottom by people who'd worked the bench and the vats themselves.

Po Chung, who built DHL International, made essentially the same point with a sharper edge — the operational staff were always hired from within, he said, because "have you ever heard of an army anywhere on the planet that hired a general from another country?" David Ogilvy went further still, framing outside hiring almost as a failure of leadership: "We detest having to go outside to fill important jobs, and I look forward to the day when that will never be necessary."

5. It puts leaders in the shoes they used to fill.

A manager who has never done the job is guessing at what it feels like. A manager who has done the job knows. Lynsi Snyder at In-N-Out makes this the center of the company's operating philosophy: "every operations leader has done the exact jobs as the associates they're leading. They understand each one of those tasks, hands on, all the way up the line. They earned their way into their roles." It changes what gets asked of frontline employees, what gets forgiven, and what gets fixed — because the person making those calls has personally stood where the complaint is coming from.

6. It treats building people as the job itself.

Everything above describes what promotion from within produces — the incentive, the compounding knowledge, the empathy. But talk to the leaders who actually run these companies, and a different explanation surfaces: they don't describe developing people as a means to an end. They describe it as the actual job.

Les Schwab put this in capital letters in his own writing, as if the emphasis mattered. Asked what his company should do to keep succeeding, "the answer is, as it has always been … BUILD PEOPLE." Andy Taylor at Enterprise Rent-A-Car drew the distinction against competitors explicitly: "their business is cars and ours is people. They focus on building their fleet of cars; we focus on building our employees' careers." Howard Stoeckel said something similar about Wawa — the products and service matter, but "even more, it's about building people with the ability and drive to make their dreams come true."

Lynsi Snyder frames it as a genuinely long-run bet at In-N-Out: "We want to build success into every person who works for our company … We want them to learn how to make good or even extraordinary decisions right from the start, then stay with our company for the long-term."

The Cintas Case in Miniature

I got to see a live version of this recently, sitting down with Cintas CEO Todd Schneider and COO Jim Rozarkis. Cintas turned a uniform-and-workplace-supply business into a roughly 750-bagger, and it's tempting to hunt for some hidden breakthrough behind a number like that. There isn't one.

Both Schneider and Rozarkis started at the bottom of the business and worked their way through every layer of it. It shows. When I asked what new hires notice first, the answer was blunt: "You people are crazy." Cintas is intensely competitive, and everything gets measured, which shakes plenty of people out early. That's why it recruits straight out of college and builds leaders internally—shaping them before anywhere else gets the chance. The people who thrive in that environment tend to stay, rise through the ranks, and eventually lead the company.

O'Reilly: The Case for the Whole Thesis

If any company treats promotion from within as the entire explanation for its success rather than one factor among several, it's O'Reilly Automotive. CEO Brad Beckham doesn't hedge on this: "At the heart of our culture is promote from within." He didn't go to college. He grew up in the company's stores, ran districts and regions, and now runs the whole thing — and he's explicit that this wasn't an unusual path at O'Reilly, it was the standard one. "I immediately knew that I had a career path with our 'promote from within' philosophy," he's said of his own early days there.

The scale of it is what makes O'Reilly's case so striking. Beckham points to Doug Bragg, the company's EVP of stores and professional sales, who's on his thirty-first year at O'Reilly — starting out loading trucks in a distribution center before working through stores, districts, and regions. Beckham's three regional SVPs of store operations average, by his count, roughly twenty-two years each, either at O'Reilly directly or at a company O'Reilly acquired. He connects that tenure directly to how well the company understands its own customers: "that's incredibly important to us when it comes to really understanding what our installers, what our professional shops are going through every day." And it isn't just the top of the org chart: O'Reilly runs thirteen divisions across the US, and every single divisional vice president ran an O'Reilly store first, then a district, then a region, before taking responsibility for groups of five hundred to seven hundred stores.

The company's own filings back up the anecdotes. As of December 31, 2025, O'Reilly's 264 senior managers averaged 20 years of service, its 377 corporate managers averaged 13 years, and its 649 district managers averaged 14 years — a leadership bench built almost entirely through internal tenure rather than external hiring. It's a case that goes further than most of the companies here: O'Reilly doesn't present promotion from within as one input into its culture. It presents it as the culture, full stop.

A Few More Scenes From the Shop Floor

The pattern shows up in some genuinely vivid places if you go looking. At Wegmans, half of all store managers started working for the company as teenagers — meaning a meaningful share of the leadership team spent their formative working years, not just their careers, inside the same stores they now run. Barclay Simpson at Simpson Manufacturing put the whole philosophy in a single line that's hard to forget: "when people join our company, they don't come for a bus stop; this is a career."

And that brings the story back to where it started. Endicott Johnson's own company history, describing the same walk from the floor to the boardroom that built the world's largest shoe manufacturer, likened the effect to an old line about Napoleon's soldiers — each one supposedly marching with a field marshal's baton tucked in his knapsack. The point was never that every soldier would use it. It was that every soldier knew there was a real pathway to the top, and that knowledge alone was enough to change his effort, his discipline, his sense of what he was fighting for.

When Going Outside Makes Sense

This isn't a blanket rule, and the best practitioners are explicit about the exceptions. Phil Fisher himself noted that a company growing very fast, or one that needs a genuinely rare specialized skill — a particular legal specialty, a scientific discipline far outside the core business — may have no choice but to hire outside, and that doing so occasionally can even inject useful fresh thinking. Isadore Sharp at Four Seasons put it simply: promotion comes from within, "except when we need talent we don't yet have."

The companies on this list mostly reserve external hiring for specialist roles — legal, some technical functions, occasionally finance — while treating the operating core, and especially the CEO seat, as something earned from the inside. Macquarie Bank hasn't hired a CEO from outside its own ranks in over fifty years. O'Reilly hasn't hired outside the company for field leadership in decades. It's policy, defended deliberately, year after year — not an accident of history.

The Investor's Takeaway

None of this shows up cleanly in a discounted cash flow model. But it shows up everywhere else: in employee tenure numbers, in the near-total absence of the “new CEO reset” that so often destroys value, in the depth of a leadership bench that can survive a downturn without a costly external search, and in a workforce that believes — correctly — that the person running the warehouse today could be running the division in fifteen years.

It’s a quiet variable. It’s also, across a remarkable number of the best long-term compounders, a remarkably consistent one. The path from the forklift to the boardroom does more than reward loyalty. In many of the world's best businesses, it's how knowledge, trust and culture compound — and how the company ensures that the person making decisions at the top still remembers what the work felt like at the bottom.

The best companies do not merely build products, stores or factories. They build people capable of carrying the business forward.


* Visit the
Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
The Secret of Weak Competition

Warren Buffett once said, half-joking, that the secret of life is weak competition. It's a strange thing for the world's most famous investor to admit — we're taught that competition is healthy, that rivalry sharpens products and disciplines prices. Buffett has spent sixty years looking for businesses that face as little competition as possible.

He's not alone. Charlie Munger put it more bluntly — he'd seen a single competitor be enough to ruin a business. Sam Zell argued there's no substitute for limited competition: you can be a genius, but if the field is crowded, genius won't save you. Peter Thiel turned it into a slogan: competition is for losers.

Chris Hohn makes the investor's case for why, stripped of the aphorisms. Moats aren't static, he argues — they're something you have to keep re-underwriting. "We used to love consumer staples, but they became richly priced and offered low returns. We used to like media content companies, but streaming severely weakened their moats. Disruption can happen — you've just got to stay alert to it." His fund's response is to spend almost all its time on barriers to entry precisely because most investors underestimate how quickly they erode.

The purest version of the ideal is the business with no competitors at all. Howard Stoeckel of Wawa liked to say the company didn't want to be McDonald's fighting Burger King — it wanted to be Cirque du Soleil, competing against no one, occupying a category so distinct that rivalry simply doesn't apply.

It's a beautiful position to be in. It's also rare, and it comes with a hidden risk. Chung Ju-yung, who built Hyundai, made the opposite case: a company without rivals eventually turns stagnant, the way state-run monopolies do — running alone in a marathon feels comfortable right up until the day it isn't. Markets move. Technology changes. A regulator shifts the rules, or a new entrant arrives with a better way of doing things. Comfort breeds blindness, and the business that has never had to look over its shoulder is often the last to notice the ground shifting beneath it.

And yet, set against Buffett’s crowd is an equally impressive group of builders who argue that competition made their businesses better, not worse. That is the paradox. The ideal business faces weak competition but behaves as though a formidable rival is always approaching.

Avoiding Competition

Some of the best operators didn't wait for weak competition — they engineered it, by staying invisible for as long as possible. Jeff Bezos has been explicit about this with AWS: "we got about two years of runway before competitors copy your idea," and in AWS's case, the head start ran to seven. Sam Walton said much the same about Walmart's early years, admitting the misconception that Walmart was a fly-by-night outfit "worked to our advantage," letting the company grow largely unnoticed until it was too far along to catch. Ingvar Kamprad built the same invisibility into IKEA's structure without ever naming it as strategy: stores went up out of town rather than in furniture retailers' traditional turf, tables were made by door manufacturers instead of furniture factories, and customers assembled the products themselves. None of it looked like competition to the incumbents — until IKEA was one of the most recognized furniture brands in the world.

The pattern shows up again and again in a company's choice of ground. Truett Cathy built Chick-fil-A inside shopping malls, a category fast food had ignored, and had it largely to himself for a decade. Enterprise Rent-A-Car avoided airports entirely, setting up next to Laundromats and strip malls while the majors fought over business travellers. Michael Dell built a direct-sales computer business that IBM and Compaq dismissed as "just a mail-order company" — until it wasn't. In each case, the competition wasn't absent by luck. It simply hadn't noticed yet.

Eventually, though, every successful business gets discovered. Then the question changes from how to avoid competition to how to use it.

Compete, Don't Retreat

In 1963, a Coca-Cola executive was asked what he thought of Pepsi. Robert Goizueta's answer became one of the more famous lines in American business: if Pepsi-Cola didn't exist, he said, he would try to invent it. It kept Coke — and Pepsi — lean, and on their toes. It's an odd thing to say about the company trying hardest to put you out of business. But wander through enough founders' letters and biographies, and you find the same instinct again and again: the best operators don't just tolerate their rivals. They study them, chase them, and sometimes seem almost grateful for them.

There's a cost to never facing a real rival, too. "Lack of competition is the equivalent of no peer review process," Michael Bloomberg argued — when a better competitor eventually shows up, an organization with no prior need to improve has usually grown too lazy to react in time. Charles Koch reached a similar conclusion from the builder's side of the equation: competition isn't something to survive, it's something to accelerate, and he's blunt about the tempting alternative — businesses that try to protect themselves through tariffs, permitting and subsidies end up trading away the very progress competition was supposed to produce.

The sharpest version of this idea belongs to A.P. Giannini, who built the Bank of America from a single branch into the largest bank in America. "If my opponents hadn't forced me time after time," he said, "there would have been no driving, sustained effort to top the field." Toward the end of his life, he went further, framing the debt as gratitude rather than grudging respect: "For whatever success I have attained, I give the bulk of the credit to my enemies. They stimulated me. They kept me going. I am thankful to them." It's the same instinct Ovid captured two thousand years earlier — a horse never runs so fast as when it has other horses to catch up to and outpace.

Your Competitor Is a Free Consultant

If the first instinct is to face competition rather than avoid it, the second is to actually learn from it. Nobody made the case better than Terry Leahy, who ran Tesco through two decades of brutal UK grocery competition:

"Years spent in the hurly-burly of retailing made me realise that competitors — and the act of competition itself — are great teachers. I don't like waiting for my competitors to come over the horizon. I prefer to seek them out. Nor am I interested in looking for their faults or spotting their weaknesses — that is not only easy to do, but a sign of complacency. I want to know about them so that I can learn from them. My strongest competitors are the best management consultants there are: I look at their operations, their products or simply visit their website to find out about their thinking, research and planning — for free."

Leahy named Aldi and Walmart as the two toughest competitors he faced at Tesco. When Walmart entered the UK, Tesco was genuinely worried — Walmart's buying power was formidable, and Tesco's non-food operation was still in its infancy. So Tesco studied them closely: "We crawled all over their business." What emerged was that Tesco's lean supply-chain expertise, built for fresh food, could offset the higher prices it paid manufacturers due to lower purchasing volumes. Tesco responded by increasing store size, launching new formats, broadening its product range, adding services and cutting prices. It also sourced more strategically, concentrating purchases with selected suppliers to recreate some of the scale advantages Walmart enjoyed through its enormous global buying power. The business didn't just survive the onslaught: Tesco grew market share and profits more in the five years after Walmart entered the UK than in the five years before. As Leahy put it, "Walmart drew the best out of us."

Henry Ford approached competition from the opposite direction. Whenever a new car appeared, he bought one, tore it down, and studied every improvement he could find. "Scattered about Dearborn," he said, "there is probably one of nearly every make of car on earth." Xerox, under David Kearns, benchmarked L.L. Bean's warehouse picking speed, American Hospital Supply's small-item logistics, and American Express's call resolution rate, pushing its own first-call resolution from near zero to 85 percent.

Sitting in the Car

Some of the best learning didn't come from formal benchmarking teams at all — it came from simply watching.

Tom Monaghan would sometimes drive to a competitor's pizza store and sit in the car for hours, estimating how much business they were doing and thinking through what might make them more successful — and, by extension, what might make Domino's more successful. He did the same outside his own stores. "The numbers weren't the important thing," he said. "What was important was the intellectual exercise." Over the course of building Domino's, he visited roughly three hundred pizzerias, purely to look for methods worth stealing.

Carl Sewell ran the reverse experiment on his chain of auto-dealerships, hiring mystery shoppers to buy cars from his own dealerships twice a year, so he could see his business the way a customer — or a competitor — would see it.

The Competitor You Don't Know You Have

The harder problem isn't the rival you can see. It's the one you can't.

Leahy borrowed an insight from the Cold War strategist Sir Michael Quinlan: expected threats are usually the ones everyone prepares for. The danger comes from what nobody thought to expect. Applied to business, Leahy's conclusion was that the more conventionally you define competition — the way analysts and industry experts define it — the less likely you are to spot the hidden competitor. "This is the greatest threat of all: the competition you don't know you have." Finding it requires ditching the analyst's frame and thinking like a consumer instead — someone with a need, a wish, a demand — and following instinct rather than convention.

Leahy learned this the hard way inside Tesco. The company built a non-food home-delivery service — washing machines, bikes — explicitly to beat Argos, a catalogue retailer. It eventually struck him that the assumption was entirely wrong. The real competitor wasn't Argos. It was Amazon, then mostly known for books, music and film, but clearly capable of expanding into new categories. Once he saw it, Tesco had to overhaul its processes, build new categories, and invest heavily in online capability and logistics to confront a competitor it hadn't originally been watching at all.

His broader observation was that the unexpected threat rarely comes from a competitor's deliberate move. It comes from a new piece of technology creating an entirely new sector that didn't exist when the original competitive map was drawn.

Cable had a version of the same blind spot, playing out on a much bigger stage. For decades the industry's competitive map was drawn against other cable operators and satellite. Netflix skipped that fight entirely — selling video straight to the consumer and delivering it over the very pipes cable had spent hundreds of billions of dollars building, without paying for the privilege. Within a few years it was consuming roughly a third of all North American internet traffic at peak hours, largely on content the cable networks had licensed to it themselves. Media veteran John Malone's verdict was blunt: the industry had funded its own demise. Cable had beaten every competitor it was watching for — it simply wasn't watching for this one.

Creative Destruction

Joseph Schumpeter gave this idea its theoretical name back in 1942, describing what he called creative destruction. His sharper point, echoed almost exactly by Leahy seventy years later, was about where the real danger comes from: "It is not... competition which counts, but competition from the new commodity, the new technology, the new source of supply [and distribution], the new type of organization... which strikes not at the margins of the profits and the outputs of the existing firms but at their foundations and their very lives."

Charles Koch built this thinking directly into how he runs his business. Creative destruction, he argues, is always with us — cars and trains replacing horses and buggies, smartphones and the internet replacing older forms of communication — and however good a business may be, "at some point, probably sooner than later, it will no longer be good enough." His stated aim is to "drive it faster than our best competitor" — treating the four sources of disruptive innovation Schumpeter identified (new products and services, new technologies, new sources of supply and distribution, new types of organization) as a menu to pursue rather than a threat to defend against.

The Dodo Problem

There's a reason facing no real competitor at all is more dangerous than it looks.

Aoris Investment Management made the point using the dodo. The bird evolved on Mauritius, an island with no natural predators. With nothing to compete against, it lost the ability to fly and lost its fear instinct. It thrived for millions of years — right up until Dutch sailors arrived in 1598 with rats, pigs and monkeys that had been sharpened by real competition on the mainland. The dodo had no defences left, because it had never needed any.

Businesses that go unchallenged for long enough tend to lose the same instincts. Taxi companies are the more recent version of the same story. For decades, the incumbents faced limited competitive pressure and had correspondingly little incentive to invest in the product itself. Uber changed the category not by operating a better taxi fleet, but by introducing a technology layer the incumbents had never been forced to build: visibility, accountability and frictionless payment. It was Schumpeter’s warning made literal — a threat aimed not at the margins of the existing model, but at its foundations.

What Investors Should Look For

Most competitive-advantage analysis asks how far a business stands from its rivals: its scale, brand, switching costs, network effects or cost advantage. It is worth asking the opposite question too. How closely does management study its competitors? Does it know which competitor actually matters? And has it retained the instincts of a business that could still be challenged?

Weak competition is a wonderful economic advantage. But as Buffett put it just this month, "if you have a wonderful business, you are going to be subject to attacks. So it's not a question of whether it was wonderful yesterday — the question is, how long is it going to be wonderful?" Moats erode, technologies shift and competitors emerge from outside the categories analysts have learned to watch.

For investors, the tell is often in how management talks about its rivals. Is competition merely a risk-factor paragraph in the annual report, or does management understand how competitors operate, where they are improving and why customers might choose them instead? Has the definition of “competitor” been revisited recently, or is it frozen in the shape of the industry as it existed a decade ago?

The ideal business faces little competition but studies it relentlessly. It enjoys the economics of a monopoly without developing the instincts of one. Goizueta said he would invent Pepsi if it did not exist. Giannini simply thanked his enemies by name.

The secret may be weak competition. The trick is never believing it will stay that way.

Further Reading:
‘Iron Sharpens Iron: The Underappreciated Upside of Competition,’ Matthew Berry, Aoris Asset Management, March 2026.


* Visit the
Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
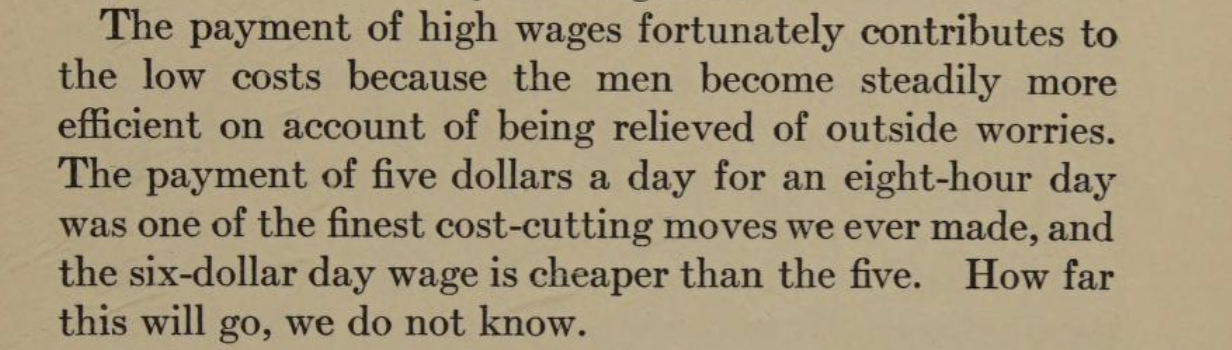
The Chalk on the Floor

There’s a story from the early days of Charles Schwab — the steel man, not the brokerage founder — that tells you almost everything you need to know about internal competition.

Schwab, running a mill for Andrew Carnegie, walked into one of his worst-performing plants and asked the day shift foreman a simple question: how many “heats” — furnace runs — had they completed that day. Six, came the answer. Schwab didn’t lecture anyone. He took a piece of chalk, wrote a giant “6” on the floor, and walked out without another word.

The night shift came in, saw the number, and asked what it meant. When they found out the boss himself had chalked up their production count, they didn’t need to be told what to do. They rubbed out the six and wrote a seven. The next morning, the day shift saw the seven and erased it for a ten. Back and forth it went, chalk mark by chalk mark, until — in Schwab’s own words —

“this mill, formerly the poorest producer, was turning out more than any other mill in the plant.”

No bonus was announced. No memo went out. Just a number on a floor and two shifts who refused to be shown up by each other.

People Aren’t Just Motivated by Money

Schwab understood something that a lot of management theory still underrates: make a number visible and people will move heaven and earth to change it — often for reasons that have nothing to do with a paycheck. As Schwab himself explained it, he’d come to believe there was an innate competitiveness in most people that could be stirred to remarkable output, given the right kind of challenge.

Jack Stack, who spent decades running Springfield Remanufacturing Corp. on exactly this principle, gets at the root of it. Work, he argues, is boring — but people love the idea of playing a game or competing, and that instinct is one of the most powerful tools a manager has. People only get beyond the baseline of work when the motivation is coming from inside them. You can set any goal you like — building the best company, hitting a production record — but if people don’t want it for themselves, it isn’t going to happen. Real management, in his view, is about instilling the desire to win —

“Instilling self-esteem and pride, that special glow you get when you know you’re a winner. Nobody has to tell you. You just feel it. You know it.”

It’s an old truth, not a new one. Napoleon Bonaparte, of all people, understood it as well as anyone. Aboard the ship carrying him into exile after Waterloo, he told his British captor as much — that a soldier will fight long and hard not for money, but for —

“a bit of colored ribbon.”

It’s why he’d created the Legion of Honor over a decade earlier: a system of medals and recognition costing the state almost nothing, yet capable of driving men to risk everything. The same principle runs through nearly every story in this piece — the reward isn’t the point. Being seen to win is.

Carl Sewell built an entire philosophy of auto-dealership management on the same instinct. He liked to point out that people are naturally competitive — they’ll try to beat whatever target is put in front of them whether or not there’s extra money attached. His go-to comparison was racquetball: nobody’s paying you to play, but you’re still diving across the court trying to win. Sewell’s practical application was to post results everywhere — delivery times, receivables, customer satisfaction scores — all personalized, so “everybody understands how the game is played and who’s doing the best.”

The Research Backs It Up

This isn’t just a collection of good anecdotes. When Tom Peters and Bob Waterman researched In Search of Excellence over four decades ago, they found the same pattern surfacing again and again in America’s best-run companies. As they put it, “there is little place in the rationalist world for internal competition” — a company isn’t supposed to compete with itself. And yet, they wrote, “throughout the excellent companies research, we saw example after example of that phenomenon.”

The mechanism, in their words, was “the use of social comparison” — “regular peer reviews,” performance data “made widely available,” and internal rivalry “purposefully induced” rather than accidentally tolerated. The costs are real — duplication, cannibalization, wasted development spend. But the payoff, harder to put a number on, shows up in commitment, innovation, and a relentless focus on the top line.

You Can’t Compete Without Data — And You Can’t Have Data Without Transparency

None of this works without one non-negotiable ingredient: the numbers have to be visible. Schwab’s chalk mark was the entire intervention — it wasn’t a threat, it wasn’t a target handed down from above, it was information, made public.

Jack Stack built his entire management philosophy — open-book management — around this idea, and he came to it the hard way. Early in his career, he decided that secrecy was, in his words, baloney — and resolved that from then on he would give his people everything he had. That decision eventually grew into a whole system for teaching employees how a business actually makes money. His broader principle was this —

“The more people know about a company, the better that company will perform. This is an iron-clad rule.”

Stack also made the case for why you measure things in the first place — not simply to rank people, but because nothing matters more than an environment where people feel they’re making a difference. You can’t feel good about your work, he argued, unless you can see the difference it makes — which means measurement isn’t a control mechanism. It’s what lets people see themselves winning.

You see the same logic at ABB under Percy Barnevik, who ran roughly twenty power transformer factories across fifteen countries and compared their monthly performance data against each other, naming a winner every time. No factory, Barnevik found, wanted to end up at the bottom — and every factory got better because of it.

Even John D. Rockefeller, running the closest thing to a true monopoly American business has seen, understood the danger of getting too comfortable. Standard Oil’s committee system circulated performance figures deliberately to stir up rivalry between its partially-owned subsidiaries, with top units competing for records and prizes. The logic, as one biographer put it, mattered enormously —

“monopolies, spared the rod of competition, can easily lapse into sluggish giants.”

John Patterson, founder of National Cash Register, was doing the same thing on an even grander scale before the turn of the last century. He put the sales results of every one of his agents into a company bulletin, The N.C.R., along with whatever they were willing to share of their own methods — turning individual technique into shared company knowledge. A salesman who put up a good number got his photograph printed alongside an account of what he’d done, which Patterson candidly admitted served two purposes —

“partly to reward the man and partly to challenge all the other men to go and do likewise.”

Anyone who hit their full quota became a member of what Patterson called the Hundred Point Club — an honor that came with an invitation to the annual convention in Dayton. The club even had its own hierarchy, with the first people to hit quota assigned honorary leadership positions. The entire mechanism was recognition, rank, and public comparison — and by Patterson’s own account, the club’s conventions only grew more prestigious with each passing year.

Engineering the Instinct

You’ll find it deliberately built into some of the world’s most successful companies — because it’s one more way they get the best out of their people.

Brown & Brown, the insurance brokerage, calls it a “survival of the fittest” culture by design. As J. Hyatt Brown put it, the company’s success can be traced directly to its internal competitive posture — profit center managers are given real autonomy and full responsibility for their results, then measured both against each other and against their own past performance. Andrew Watts doesn’t dress it up —

“We are a performance based culture. It is very competitive. There are leaderboards everywhere. If you like being ranked you will like it here.”

Ken Kirk frames it in athletic terms — even the company’s highest-performing profit centers keep improving because of the rivalry, not despite it, sharing information as they chase the same goals. Just as athletes lift their game with stronger competition, he argues, Brown & Brown’s teams do the same, vying for top positions rather than settling once they’re already ahead of the pack.

Enterprise Rent-A-Car takes the transparency piece further than almost anyone. Frederick Reichheld noted that Enterprise openly shares financial results and customer satisfaction scores for every branch and every region, so employees can see for themselves which offices have stumbled onto a winning practice — a van driver handing out free soft drinks in the summer heat, an assistant manager who started letting customers return cars after hours. Because branch and assistant-branch manager pay is tied directly to branch profit, managers have every incentive to study what their peers are doing and steal it. The rivalry stays friendly — Reichheld describes competing branches wagering a dinner on whose monthly profits come out ahead — but it keeps everyone hunting for small, real ways to build customer loyalty.

David Cote at Honeywell went further still, publicizing internally the top ten and bottom ten performing teams on a key operational metric. Leaders loved landing in the top ten. They hated the bottom ten so much that Cote found the tactic accelerated improvement faster than almost anything else he tried — and he recommends it as a go-to lever whenever you’re trying to change an organization’s behavior.

Perhaps the most literal example comes from 3G Capital’s ownership of the Brazilian railway América Latina Logística. Drivers, it turned out, varied enormously in how efficiently they braked, accelerated, and routed trains — and diesel was the company’s single biggest cost. So the company built onboard computers that tracked every trip and ranked every driver on fuel efficiency and safety. They called it the Diesel Cup. Top performers got badges for their uniforms and had prizes handed to them by famous soccer players. The result: fuel consumption fell 30%, and the railway became the safest in Brazil. The idea, notably, wasn’t invented in-house — it came from an executive who’d spent weeks studying how Anheuser-Busch ran its own internal sales competitions.

The Common Thread

Strip away the industries and the decades, and the pattern is always the same three moves: make the number visible, let people compare themselves to each other, and trust that most people would rather win than be paid to lose quietly. In the best examples, the rivalry stays friendly — a chalk mark, a leaderboard, a wagered dinner, a badge on a uniform. Nobody’s threatened. They’re just being watched, and given the chance to be the one who comes out ahead.

What Investors Should Look For

As investors, we spend a lot of time hunting for competitive advantages — brands, network effects, switching costs, scale. Internal competition rarely makes that list, but it should. It’s one of the few advantages a management team can build using information the company already possesses.

What separates the companies in this piece isn’t the tactic itself — a scoreboard, a bulletin, a badge — it’s the discipline behind it. Branch results, factory output, driver efficiency, sales per store: posted, compared, and left for people to react to on their own. It costs almost nothing, and it’s remarkably hard for a competitor to copy, because it isn’t a system so much as a culture of transparency that has to be built, often over years.

For investors, the tell is usually in how a company talks about its own units. Does management know — and share — which branch, plant, or team is outperforming, and why? Do employees have the data to compare themselves to their peers, or only to a budget set from above? A business that can answer these questions in detail has quietly built its own internal market — capturing the benefits of competition without needing an outside rival to provide them.

Schwab needed no elaborate incentive scheme. He needed a piece of chalk, a floor, and two groups of people who could see the score.​​


Further Reading:
‘The Great Game of Business - The Only Sensible Way to Run a Company’, Jack Stack, 2012


* Visit the
Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
35 Books In.

Top 14 [Ranked Top to Bottom]

By the time I closed the last page of The Invisible Billionaire — Jerry Shields' biography of Daniel Ludwig — I had read thirty-five books this year. A meatpacker from Austin, Minnesota. A five-star general. A Japanese electronics founder. Two advertising brothers who broke every rule in London. A tennis coach. A Dutch-Austrian who bottled an energy drink nobody asked for. A graffiti artist whose work became a hundred-million-dollar market. A shipping magnate who reshaped the global oil tanker industry and then blew a billion dollars in the Amazon jungle.

On the surface, none of this belongs together. But six months and thirty-five books in, I keep closing them with the same sensation I had at the end of eight days on the road earlier this year: different rooms, same conversation.

Here's what that conversation keeps coming back to.

Where The List Comes From

At the start of the year, I didn't know I'd read most of these books. They arrive through serendipity more often than design.

Bill Gurley's Runnin' Down a Dream was picked by a member of our four-person lunch reading club — I've followed Bill for years, and it's become my go-to recommendation for anyone starting a career or weighing a change; I bought copies for both my sons, who are just starting out. Three other books on the list trace back to his recommendations, Carl Sewell's among them — one of the most successful car dealers in America.

Jackson Street Booksellers - Omaha - Est. 1993

Some books I send straight to investee company management teams. Ten copies of The Compounders went out to serial acquirers. David Cote's book landed with a company that stands to gain enormously from managing costs into a revenue tailwind and the operating leverage that comes with it. The Cummins books were ordered after a conversation with MSA Safety, who pointed me toward other businesses worth visiting on the Indianapolis leg of our recent US trip.

I found the Frank Perdue book after a Forbes profile left me wanting more. The Big Store, on the crisis at Sears, has been on the list a while — Bernie Marcus recommended it, and said it had such an effect on him that for years he insisted every Home Depot executive read it. Hopper, Basquiat, and de Kooning kept me moving down the art rabbit hole I've been in for the past few years.

Most of the rest came from secondhand bookstores. The Tragedy of United Fruit caught my eye because I'd loved The Fish That Ate the Whale. Hormel, the Saatchi brothers, Apache Corporation, and the John Lewis story were bookstore finds. The Brattle Book Shop in Boston and Jackson Street Booksellers in Omaha are both worth the detour if you're ever in either city.

Innovation Is Not an Event, It's a Habit

J. Irwin Miller wrote it down in 1956, before most of his competitors had bothered to think about it at all: "It is the Corporation's responsibility to obsolete its own products with new developments. If it doesn't, someone else will." Frank Perdue arrived at the same place selling chickens instead of engines — a business that doesn't change is a business that's going to die — and Carl Sewell put a number on the same idea from the Cadillac showroom floor: customers don't give you points for being first, they leave the moment somebody offers more.

Eli Broad, founder of KB Homes, called it "a permanent revolution": conventional wisdom abhors innovation, and the comfortable case for waiting — return to fundamentals, focus on next quarter, keep doing what you do best — is really just a recipe for stagnation. David Cote ran Honeywell on the same premise turned into operating discipline, "perpetually restructuring" the business to keep fixed costs constant as it grew — restructuring that only worked, he was careful to note, because it was tied to permanent improvement of the underlying processes, not a one-off cut. Bill McDermott's version is the sharpest: no company can ever declare absolute victory. Winning, at SAP, was a process and not a destination — a state of mind that meant looking for the next idea again the day after the last one worked.

What struck me reading Hormel's history alongside Cummins' is how early this instinct shows up, and how little it cares about industry, era, or geography. George Hormel's answer to every problem, repeated to his organization for decades, was a single word: originate. Not compete, not cut costs — originate. Thomas McCann, writing about United Fruit's slow collapse, describes the disease that sets in when a company forgets this: "habit becomes more important than innovation, and how things get done takes precedence over why." Renewal is available to a company in a way it isn't to a person, McCann adds, but only if the people at the top can recognize the senility before it becomes incurable. United Fruit never did.

Xerox PARC takes the same failure a step further — the company didn’t even have the excuse of not seeing it coming. Its own engineers were inventing the future of computing while Xerox squeezed another cycle out of the same tired copiers. Xerox had the future in its own building and stood glumly on the sidelines while everyone else built it.

It's worth noting that the histories of both Hormel and Cummins were written and titled around the same milestone — Dougherty's In Quest of Quality subtitled Hormel's first 75 years, Cruikshank and Sicilia's The Engine That Could the same 75 years at Cummins. Today Hormel is 135. Cummins is 107. Both are reminders that longevity isn't the result of standing still — it's the reward for renewing yourself without losing the original DNA.

Books 15-35 [Ranked Top to Bottom]

No Substitute for Quality

Frank Perdue's whole business rested on a claim he never softened: "There is no substitute for high quality. Quality is the one absolutely necessary ingredient of all the most successful companies in the world." George Hormel said the same thing to his own workforce a half-century earlier, in language with no room for interpretation: "Every last man of us must care enough to make our products the best we know how." Bob Beyster built SAIC on the identical premise from the opposite end of the economy — government contracting — calling it "an uncompromising commitment to quality."

What ties the three together is that none of them treat quality as a department or a slogan. Hormel's version of it was two separate scales at the plant, just to check livestock weight against itself — nobody writes a case study about a second scale, but it's why the company is still standing. Panasonic’s founder, Kōnosuke Matsushita's version was a hard rule: a new product had to be 30 percent better and 30 percent cheaper than what already existed, or it wasn't worth launching.

Who a Company Decides It Exists For

Matsushita said it as early as 1932: "The mission of a manufacturer is to overcome poverty, to relieve society as a whole from the misery of poverty and bring it wealth." J. Irwin Miller ran Cummins on the same conviction, formalized into seven named stakeholders — community, labor, government, vendors, distributors, customers, shareholders. Miller wanted Columbus, Indiana to be not the cheapest place to do business but the best place of its size in the country, and treated that as a competitive advantage, not a cost.

Set that against United Fruit, which earned the nickname “El Pulpo” — the Octopus — for a reason, and against Daniel Ludwig, who treated the Amazon’s ecosystem, his workers, and his tax obligations the same way — costs to be minimized, laws to be evaded. Both companies were as disciplined as Cummins in the parts of the business they cared about.

Miller and Matsushita answered the stakeholder question before anyone asked it of them. United Fruit and Ludwig never asked it at all — and both paid for it twice over: first in how they treated the world outside their walls, then in a culture of fear inside them, where people learned early what happened to those who spoke plainly and stopped taking the risk. Eventually the only voices left were telling them not the truth, but what they wanted to hear.

Nobody Builds Anything Alone

Matsushita called it collective wisdom — not democracy, he was careful to say, but decisions made only after everyone affected has had a say. Jim Perdue's version is more useful to anyone running something today: nobody knows more about a job than the person doing it in their own twenty-five square feet, so go ask them. Lloyd Blankfein's version is sharper and funnier, a joke that's really a confession about how rarely leaders act on what their people already know: "Tell me what you should do, because then I'm going to tell you to do it."

David Cote's Honeywell plants ran their own efficiency drives without a consultant in sight, because people are simply more committed to fixing a problem they diagnosed themselves. Robert Beyster put it as plainly as it can be put — the secret sauce was never a strategy, it was an environment where one person could make a difference and be recognized for it. It's the line that holds up across every biography on this list: success never happens alone.

Delegation Is a Form of Respect, Not the Absence of Control

George Marshall — widely ranked among America's most consequential military leaders, architect of the Marshall Plan, and the only career soldier to win the Nobel Peace Prize — had a rule for his own generals that was almost insultingly simple: "give them the bare tree, let them supply the leaves." He made a point of not questioning a subordinate's method unless it failed.

Bill McDermott, thirty years and an entirely different industry later, arrives at the identical instinct: prescribe too many solutions and you're merely insulting people's intelligence and stifling their potential. Lord Hanson built an entire conglomerate on this formalized into policy — tight financial control from the center, and management "left, and motivated, to get on with that job" everywhere else.

None of them say it outright, but it's there underneath Marshall and Hanson and McDermott alike: delegation only works as a strategy once you've done the harder work of hiring and trusting well in the first place. It isn't a technique you bolt on. It's what's left over when the people question has already been answered.

Say It Again. Then Say It Again.

Terry Leahy, running Tesco, gave the funniest and most honest confession I read all year — fourteen years of speeches on the same values, which "bored me to death," and which worked precisely because he never once stopped repeating them. Bill McDermott's discipline was the same idea stripped to three words: "Customer. Customer. Customer." Carl Sewell reached for church as the analogy — you don't read the Bible once and understand it, and you don't state your values once and expect people to live by them.

Brattle Book Shop - Boston - Est. 1825

Daniel Coyle found the data behind the instinct: when Inc. surveyed executives at six hundred companies, they guessed nearly two-thirds of their workforce could name the company's top three priorities. When Inc. asked the employees, the real number was 2 percent. Coyle's conclusion was that leaders are wired to assume everyone already sees things as they do — which is exactly why the best ones plaster priorities on walls, emails, and speeches until the message becomes, as he put it, "part of the oxygen."

David Cote's Honeywell ran on the identical premise, pushed even further: talk about the culture until you're sick of repeating it, Cote wrote, "and then talk about it some more." Anything worth communicating, as McDermott puts it, is almost always under-communicated.

Nobody on this list discovered a new idea about repetition. They just believed, correctly, that saying it once was never going to be enough.

Optimism Is a Load-Bearing Wall, Not a Personality Trait

Matsushita wrote through the Depression that gloomy assumptions about human potential are crippling if your task is to build something, because "negative philosophies that appeal narrowly to self interest or hate never inspire cooperation over a sustained period of time." Terry Leahy's version trades the philosophy for a plain bet on people — give them confidence and opportunity and they're capable of incredible things — and he's honest enough to call it idealistic and better anyway. Lloyd Blankfein's contribution is the least sentimental and the most useful of the three: we overvalue whatever crisis we're living through because it's still unresolved, and it's hard to fear something that's already been filed away on the shelf of history.

Every crisis in this year's reading — the Depression for Matsushita, Casablanca for Marshall, near-collapse for more than one of these companies — reads as survivable in hindsight. None of them had that hindsight while it was happening. They proceeded anyway.

Blankfein had a second point about how that belief gets carried in the room: "I'm like a flight attendant during turbulence. Smile like you're enjoying yourself. If you look afraid, the passengers will freak out." David Cote's version draws the same line more explicitly — convey confidence in your decisions publicly, because organizations don't handle uncertainty well, but question yourself all you want in private.

Neither is arguing for false optimism. They're arguing that doubt has a time and a place, and the front of the room during a crisis isn't it.

The Unconventional Ones Weren't Trying to Be

Eli Broad put it plainly: "Most successful businesses have to begin by bucking conventional wisdom. Invention and innovation don't happen without it." Alan Kay got laughed out of a room at Xerox PARC for describing a computer you could hold in your hand. Maurice Saatchi made twenty-five cold calls a day to companies that already had agencies, breaking an unwritten rule of the entire industry. Prudent men thought Frank Perdue had flipped — nobody advertised a commodity, and pouring money into chicken, with its razor-thin margins, seemed dumb to just about everyone. He did it anyway.

Broad's own example was more mundane and just as telling: the firm belief in Detroit that nobody would buy a house without a basement. He'd read enough industry magazines to know builders in Indianapolis and Dayton were already selling houses without them — basements had only ever existed to store coal, and gas heating had made that obsolete. Dropping the basement meant building faster and pricing the house for a first-time buyer who wouldn't move out of an apartment unless the mortgage came in under the rent.

None of them set out to be contrarian — they set out to solve the actual problem in front of them, and the fact that nobody had tried it that way before was incidental. Raymond Plank, who founded Apache Corporation, put his finger on why it works: what he didn't know turned out to be an advantage rather than a liability, because he'd never fallen victim to how everyone else had already learned to do things, and it let him "countermand the adage, 'Beaten paths are for beaten men.'"

Reading the Field Is Not Optional

Bill Gurley's writing on reading describes exactly what this list of thirty-five books is trying to be — "external learning," on your own time, outside the walls of whatever you're actually paid to do.

Eli Broad reads for the same reason he interviews for it: his standard question to any candidate is what they learned this past year that they didn't know before, and a blank stare is disqualifying. He put the habit itself in blunter terms elsewhere — four newspapers a day, a discipline he credited as the source of most of his ideas, sharpening over time into something like "a hound dog's sense of smell" for opportunity hidden in plain sight. David Cote ran the same regimen at Honeywell, five newspapers plus a stack of business publications, and treated it as a long-term investment as real as any capital allocation call, even when the daily pressure of the job made the time hard to justify.

George Marshall told a room of Princeton students that nobody could think with full wisdom about the present without first understanding the past — that a grasp of history was what gave conviction its weight. Lloyd Blankfein tells young people heading into finance to study history over math, because an awareness of historical cycles is what keeps you level-headed when things go wrong and keeps you from getting cocky when they go right.

None of these people were reading the same list. But put them all in a room and they'd recognize each other instantly, because each had independently landed on the same conclusion — the field is bigger than the job, and the only way to see the whole of it is to keep reading long after the workday ends.

Thirty-five books, and the through-line was never the industry. It was the temperament. Originate instead of imitate. Give people the bare tree. Say the important things until you're tired of hearing yourself say them. Believe today's crisis won't be the last one humanity survives. Keep reading beyond your own field.

None of those ideas is new. The remarkable thing is how often the people who built enduring businesses arrived at them independently.

That's not a conclusion. It's a discipline.


Further Information - 2026 Reading List


* Visit the Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
Eight Days Searching for the Same Answer

A couple of months ago I spent eight days crossing America — Indianapolis to Cincinnati, Boston, New York, and finally Omaha for the Berkshire Hathaway annual meeting — visiting businesses, investors, ballparks, bookstores and art galleries.

On the surface, the itinerary made little sense. Fire safety equipment, diesel engines, uniform rental, furniture stores, hedge funds, modern art and baseball do not naturally belong together.

But that's part of why I keep doing these trips. The best ideas rarely stay confined to one discipline. A manufacturer can teach you about culture. An artist can teach you originality. A ballplayer can teach you patience. A retailer can teach you customer obsession. A great investor can teach you temperament.

One question ran underneath almost every conversation:

What allows certain people, businesses and organisations to compound for decades?

Indianapolis — fire safety and taking the long view

The first few meetings could hardly have looked more different. MSA Safety first came onto my radar the way some of the best ideas in investing do — not through a screen, but through another investor’s work. Sequoia flagged the business in its 2025 letter. We caught up with the company and management at the world’s largest firefighting conference, held in Indianapolis.

MSA built its position protecting firefighters and industrial workers through a genuine customer obsession — designing alongside the people who actually use the equipment, not just for them. That trust has compounded over decades into the number one or two market share in category after category. The same long-term mindset is evident in the numbers: MSA has increased its dividend for 56 consecutive years. Now the company is using technology to widen that moat further, connecting equipment to central systems that give responders better information in real time and help save more lives.

Spending time with CEO Steve Blanco was genuinely comforting. While the analyst community obsesses over next quarter's earnings, Steve is investing for the decade ahead — new product platforms. It's a reminder that some of the best management teams are quietly ignoring the very audience that's watching them most closely. Meeting not just Steve but several divisional managers, the same pride and passion for the mission showed up at every level — a good sign for a business whose edge depends on genuinely caring about the people who use its equipment, not just selling to them.

Cincinnati / Columbus — Cintas, and a century-old diesel company's town

Cintas is the uniform and workplace supply company that turned into a 750-bagger. It’s tempting to look for a hidden secret behind a number like that — a breakthrough product, a stroke of genius.

Sitting with CEO Todd Schneider and COO Jim Rozarkis, the real answer was far less exciting: culture, execution, measurement, internal competition, and a customer obsession that shows up in the small things — route reliability, uniform improvements and responsiveness — repeated for decades. Both men started at the bottom of the business and worked their way through it, and it shows — the culture emanates out of two people who lived every layer of it themselves.

I asked what people notice most when they join. The answer — "you people are crazy." Cintas is intensely competitive, everything is measured, and the intensity shakes plenty of people out early. It's part of why they like hiring straight out of college and promoting from within — training people into the culture before they've been shaped by anywhere else. For the ones who like being measured and like competing, it becomes the kind of place they stay for good.

What struck me most, though, was how much runway is still ahead of it. The market remains underpenetrated, with plenty of whitespace and a genuine value-add proposition for customers who haven’t yet switched. It’s also highly fragmented — and growth comes as much through courtship as through competition, with M&A built on relationships developed over decades.

Cummins offered a different version of the same idea. Forty six years of 15.5% annual compounded returns through every kind of adversity — oil shocks, emissions regulation, entire technology cycles — but the legacy isn't only in the numbers.

J. Irwin Miller led the diesel engine company for some 40 years and understood that businesses could shape communities, not just serve them. He commissioned some of the twentieth century’s greatest architects to remake Columbus, Indiana — a town of just over 50,000 people that the American Institute of Architects ranks the sixth most architecturally significant city in America, behind only Chicago, New York, Boston, San Francisco and Washington, D.C.

America has a tradition of towns shaped by the companies that built them — Hershey and its chocolate factory, Dayton and National Cash Register, Endicott Johnson and its shoe towns in upstate New York. Each grew out of a founder who genuinely believed the company’s obligations extended past the factory gate — Hershey built schools and a free amusement park; Endicott Johnson’s ‘Square Deal’ offered free healthcare and profit-sharing decades before either was standard. Columbus belongs in that same tradition of care, but Miller’s version was more civic than paternal: rather than provide for workers directly, he invested in architecture and design excellence that made Columbus a place talented people would choose to live, independent of the company itself.

An entire town built on the idea that buildings shape people. The evidence of a truly great company sits not just in its financial statements, but in the streets around it.​​​​​​​​​​​​​​​​

Boston — museums, Fenway, and the limits of theatre

RH Design, the luxury furniture retailer, was its own kind of lesson, and one better learned in person than from a spreadsheet. Walking through their galleries — first at the DeHaan Estate in Indianapolis, then again across four floors of the old Museum of Natural History in Boston — it's impossible not to be impressed: manicured, château-like grounds, restaurant service. This is closer to theatre than retail. But that differentiation comes with a burden competitors don't carry — fit-out and upkeep at that standard, in every gallery, indefinitely. And once you look past the staging, the heritage, quality and differentiation feel a long way from an Hermès or even a Louis Vuitton — brands that pair the theatre with generations of craft underneath it. Beautiful businesses still have to earn their keep.

The Museum of Fine Arts, the Isabella Stewart Gardner, and later MoMA and the Joslyn, all taught some version of the same thing about originality — none of the artists whose work hangs there succeeded by copying consensus, and the crowd rarely recognises that kind of originality on time.

In the last few years I've gone down a rabbit hole reading about some of the greatest artists and art dealers, trying to understand where creativity actually comes from — and why it so often takes the market a long time to recognise genius. Van Gogh, de Kooning, Robert Henri, Pollock, Edward Hopper, among others: standing in front of their paintings with that history front of mind adds an entirely different layer to experiencing the work. De Kooning recoiled from any external demand, as Stevens and Swan describe in their biography of him — no woman, no institution, no club, no philosophy was ever going to give him his marching orders. Hopper put it best on originality itself: "Originality is neither a matter of inventiveness nor method in particular a fashionable method. It is far deeper than that, and it is the essence of personality."

Great businesses and great investors seem to share the same streak of independence. They're willing to challenge conventional wisdom, and they bring something close to a fanatical approach to their craft. Perhaps Hopper's real gift was seeing the simplicity sitting inside the complexity — stripping a scene down until only the essential thing remained. The best investors do something similar with a business. The method looks different. The temperament underneath it doesn't.

At Fenway Park, the 114-year-old home of the Boston Red Sox and the oldest active ballpark in Major League Baseball, the story was Ted Williams — the longest home run ever hit there, 502 feet, in 1946, a record that still stands. Buffett took the lessons of one of America's greatest sportsmen and applied them to investing: he keeps Williams's photo on his office wall, and wrote in 1997 that great investing needs exactly this kind of discipline — waiting for the fat pitch, swinging only at the best of it. Activity feels productive. Selectivity is the actual edge.

Boston / New York — patient capital, and the ideas business

The investors mostly circled back to one theme: temperament and time are the edge, far more often than analysis.

At Abrams Capital, Raja Bobbili described their advantage as behavioural rather than purely analytical — patient capital lets you support management through hard periods and go on the offensive when others are retreating — adding conviction while the market panics, and staying focused on business value instead of the daily price. It's a concentrated approach run by a four-person investment team. Their involvement in the new ContextLogic, built around the old US Salt business, is a structure worth watching — framed on the model of the Swedish compounders, giving management genuine long-term exposure rather than a typical private-equity exit path, and designed to attract the kind of management teams who want long-term partners, not short-term owners.

Seth Klarman made a related point at Baupost: as the market grows more short-term, it may be growing more inefficient for anyone still willing to hold a longer view. A nice paradox — the more impatient the world gets, the more valuable patience becomes.

At Oaktree, Howard Marks talked about building a firm around principles rather than personalities — intelligence, independent thinking, team culture — the same ingredients that let a business, not just a fund, survive beyond its founders. He was emphatic that culture comes first: no matter how successful someone is, if they don't live up to the standards integral to the business, they don't belong at Oaktree.

New York offered its own lesson, at the ballpark rather than the boardroom. The Knicks playoff game at Madison Square Garden was pure electricity — a city that takes its basketball seriously. A night later at Citi Field, the contrast was stark: a Nationals grand slam helped the Mets to their heaviest defeat of the season, and the stands were half empty. Same city, same week, two very different atmospheres. Winning teams fill stadiums.

At Sequoia Fund, Arman and Trevor described their work simply as the ideas business. Research into one company leads to its suppliers, its competitors, its customers, and often the more interesting idea sitting one step away from the one you started with. A company that isn't interesting today might be interesting tomorrow — there's a real cost to closing your mind too early. They were candid about the market's winner bias too: a small number of positions usually drive the bulk of long-run returns. Finding them is hard. Holding them, they said, is harder — this is ultimately a behavioural business.

Michael Baron made the same point from a different angle. Baron Capital's seven-to-eight year average holding period isn't an accident; it's a structure built to give a good business enough time to surprise you. He's understood the idea since he was a kid at the dinner table with his father, Ron: it's the fundamentals, not the macro, that matter — and you still need balance across a portfolio, because being all-in on one position is how you get burnt.

Munib Islam at Saraza Management framed it in the sharpest terms of the trip. He sorts every business into three buckets: great companies that stay great, great companies quietly slipping to good, and good companies becoming great.

It's the middle category that does the damage — a business can look wonderful in the rear-view mirror while its future is already eroding, which is why he treats quality as something that's never stationary, scoring it fresh rather than assuming it holds.

His favourite question for management says most of what needs saying: "What are you doing right now to make your moat wider?" — often revealing simply in how hard it is to answer.

And on the two traits that actually separate investors, he was blunt: temperament — most pod shops have none for volatility — and duration, the willingness to sit through real discomfort. "We don't have to be early," he said. "We just have to be there for the ride."

Omaha — the last lesson

Breakfast with Chris Begg of East Coast Asset Management was a highlight of Omaha. I’ve enjoyed his writing for almost two decades — he’s one of the most thoughtful investors around, and one of the few who genuinely embodies the multidisciplinary thinking Munger used to talk about. He’s now leveraging AI to sharpen his investment process, folding new tools into a mind that’s spent years pulling ideas from philosophy, architecture, and history as readily as from financial statements.

For seven years I've listened to Ron Blumkin and the team at Nebraska Furniture Mart trace the business back to the lessons of Mrs B: sell cheap, tell the truth, look after the customer. Nearly ninety years later, none of it has changed. "We are a learning machine," Ron told us. "I really mean that." Here's a family that built one of America's great retailers, sold it to Berkshire, and still keeps travelling to Harvard for leadership courses — 26 times and counting. Success never convinced them they had the answers. It convinced them to keep looking for better ones.

They remain just as obsessed with the customer end of the business — happy to be comparison shopped, because they believe they'll win, and unwilling to give away the low end of the market the way Sears once did. Sears forgot that lesson. Walmart didn't.

Then came the Berkshire meeting itself — the last lesson of the trip. Buffett sat in the front row this year, watching his own masterpiece from a distance he’d never had to before. A jersey went up to the rafters marking sixty years as CEO. Then he spoke — brief, sharp, the same wit undimmed by age. “Greg is doing everything I did,” he said, “and then some.”

A master doesn’t just build the work — eventually it has to survive someone else’s hands. Greg Abel’s job isn’t to be Buffett. It is to keep Buffett’s creation compounding long after Buffett is no longer in the front row.

Eight days. Completely different industries, completely different people. And yet the same ideas kept resurfacing — in a diesel engine's hundred-year town, in a hedge fund's four-person investment team, in a 1946 home run that's never been beaten, in a family that still hasn't stopped learning after ninety years.

The advantage was rarely some complicated formula.

It was the willingness to keep learning, keep improving, and keep doing the right things for long enough.


* Visit the
Blog Archive *

Learn more with us on Twitter: @mastersinvest

TERMS OF USE: DISCLAIMER
Failure as a Competitive Advantage

Spend enough time studying exceptional organisations and you begin to notice recurring patterns. They recruit differently. They decentralise decision making. They think about capital allocation differently. They stay unusually close to customers. They build cultures that seem to compound over decades.

Another pattern is less obvious, but it appears with remarkable consistency.

The world’s best organisations have an unusually high tolerance for failure.

At first glance, that sounds counterintuitive. Surely the best organisations make fewer mistakes than everyone else. Surely excellence is simply the result of consistently making better decisions.

But after reading hundreds of founder biographies, business histories and studies of successful organisations — from great companies to championship teams and military units — I have gradually come to a different conclusion. Great organisations are not distinguished because they avoid failure. They are distinguished because they have learnt how to convert it into learning.

That does not mean tolerating carelessness or poor execution. Quite the opposite — the best organisations are demanding, with exceptionally high standards. What they have recognised is that innovation requires a culture where people feel safe to experiment. If people become frightened of being wrong, they stop experimenting. Once experimentation stops, learning slows. And once learning slows, innovation rarely survives for long.

Elon Musk explained the mechanism plainly: punish failure too severely, and people respond accordingly — innovation becomes incremental, because nobody is willing to try anything bold. Henry Kravis reached the same conclusion from the other side of the table: a culture that does not admit failure is precarious.

Different leaders, different industries, the same finding — fear changes behaviour. People become cautious, defensive, less willing to challenge accepted thinking. Organisations that once adapted quickly can become prisoners of their own success.

Tom Peters Saw It Forty Years Ago

Tom Peters and Robert Waterman identified this pattern more than forty years ago in In Search of Excellence. One defining characteristic of excellent companies, they observed, was a high tolerance for failure — not for mediocrity, but for experimentation. The best companies, they found, experiment more, encourage more tries, and permit small failures.

As organisations grow, they can become insulated from reality. Planning increases. Analysis expands. Approval processes multiply. Meanwhile, customers change, competitors move, technology advances and the operating environment evolves. What looks like discipline can become disconnection. Small experiments are what keep a business learning.

The Palchinsky Principle

I read Tim Harford’s Adapt more than ten years ago, and one idea from it has stayed with me since. Harford describes the Palchinsky Principle, drawn from the work of Peter Palchinsky, a Russian engineer who studied why grand industrial projects so often failed.

His method was simple: seek out new ideas, test them on a scale where failure is survivable, gather feedback from the people closest to the work, and learn before committing significant resources.

It is a powerful model because it explains how great organisations actually operate. They are not reckless, and they do not celebrate failure for its own sake. They build systems that allow trial and error within sensible limits — testing before they scale, learning before they commit, and taking risk without ever making survival dependent on being right.

Eli Broad captured the risk-management side of this well: never bet the farm, or even half the farm. He believed the entrepreneur’s most common trap was the illusion of invincibility — optimism was essential, but so was a clear-eyed view of the downside. He always wanted to understand the worst case before committing to the best one.

Jim Collins made the same point more simply: the only mistakes you can learn from are the ones you survive. Failure is useful only if it is survivable.

That single idea explains a host of philosophies that otherwise look unrelated. Henry Ford was saying much the same thing more than a century ago: try everything in a little way first. Bruce Flatt, Thomas Bloch, John Malone and Barry Diller — operating decades later, in entirely different industries — arrived independently at the same rule: never risk the whole business on one deal. Halma applies the same logic to its acquisitions, entering unfamiliar markets cautiously through small, reversible bets rather than large ones.

What’s notable isn’t that these leaders knew each other. It’s that they didn’t need to. Progress requires experimentation, but the experiments have to be designed so that being wrong never threatens the survival of the business.

The Acquisition Trap

This is particularly relevant to acquisitions.

I have seen plenty of deals that looked wonderful on paper. The earnings were accretive, the synergies obvious, the strategic narrative compelling. Then reality arrived. The seller knew more than the buyer. The business had been dressed for sale. The customers were not as loyal as they appeared. The promised synergies never materialised, the cultures clashed, the systems didn’t integrate, and the people who made the business special walked out the door once the cheque cleared.

A spreadsheet can make almost any acquisition look sensible. But acquisitions aren’t completed in spreadsheets — they’re completed in factories, branches, sales teams, incentive systems and cultures. That is where the assumptions meet reality.

The best businesses understand this and rarely bet the farm. They prefer bolt-ons and adjacent opportunities over grand transformational deals, and they preserve the ability to change their mind. The danger is magnified when a deal requires issuing a lot of equity, gearing the balance sheet, and relying on a debt paydown plan that assumes the future resembles the model. Often it doesn’t.

The better question is not simply whether a deal adds to earnings. It’s whether the company can digest the loss if the thesis is wrong. In capital allocation, brilliance matters. Survival matters more.

Small Experiments Produce Big Advantages

One of the most consistent traits of outstanding companies is that they rarely rely on one enormous bet. Instead, they build systems that allow hundreds of relatively inexpensive experiments every year.

Tom Peters called this “cheap learning” and quoted 3M’s philosophy approvingly: their people make hundreds of little bets. The same thinking shows up everywhere you look. Aldi runs a three-store test before any wider rollout. Costco trials new products in a handful of warehouses before committing to larger purchases. Chick-fil-A tested menu items across dozens of stores before going national. Raymond James deliberately let managers make mistakes while they were still cheap.

The purpose of these experiments is never to prove management right. It’s to learn something while the cost of being wrong is still modest. Most will never transform the company, but collectively they replace uncertainty with knowledge before meaningful capital is committed.

Jeff Bezos has made the inverse argument at Amazon: if the scale of a company’s failures isn’t increasing as it grows, it probably isn’t inventing at a scale capable of producing real breakthroughs.

Businesses as Organic Systems

Po Chung, co-founder of DHL International, saw DHL as an organic system rather than a machine. The distinction matters. A machine operates in a fixed way. An organic system is constantly adjusting to its environment — and as Chung put it, anything that is constantly adjusting is constantly making mistakes. Mistakes are a byproduct of evolution, not a departure from it.

Jim Collins pushed this further in Built to Last. He argued that visionary companies make some of their best moves through trial and error, opportunism, and — quite literally — accident, and that they “mimic the biological evolution of species.” The comparison is worth sitting with rather than passing over.

In evolution, variation comes first. Organisms try slightly different things, mostly by accident. Selection comes second, deciding which variations survive contact with the environment. Companies that operate the same way generate many small variations — new products, new formats, new approaches — expose them to the real test of customers and competitors, and let the market do the selecting. What looks like brilliant foresight in hindsight is often just this process running for long enough.

A company that tries to remove every mistake can easily remove the variation that allows it to adapt. The goal isn’t to eliminate error — it’s to make errors visible, survivable and useful. The companies that endure aren’t necessarily the ones that make the fewest mistakes. They’re the ones that learn fastest, discard what doesn’t work, and keep moving toward what does.

A Culture Without Blame

Running experiments is only half the challenge. People also have to feel safe admitting when those experiments haven’t worked.

This may be the least appreciated trait of outstanding organisations. Many companies claim to encourage innovation, then respond to failed initiatives by searching for someone to blame — and employees quickly learn to conceal mistakes rather than discuss them.

Captain Michael Abrashoff built the opposite culture aboard the USS Benfold. His focus was never on finding someone to blame, but on making sure the accident never happened again. He also made the sharper point: show him someone who has never made a mistake, and he’ll show you someone who isn’t doing anything to improve the organisation — because organisations too often promote only the people who’ve never been wrong.

The pattern repeats wherever you look for it. Larry Culp describes Danaher’s philosophy as attacking the problem, not the person. Akio Morita wanted Sony to understand what caused a mistake rather than identify who made it. Garry Ridge removed the word “failure” from WD-40’s vocabulary entirely, replacing it with “learning moments,” because he wanted unsuccessful experiments shared rather than hidden.

Frank Perdue ran the same playbook at Perdue Farms — people were free to try something new, and if it didn’t work, the organisation learned from it and moved on. Some ideas were hare-brained. Some paid off wonderfully. That’s the trade-off: a culture that eliminates every bad idea usually eliminates the good ones too.

Marc Rowan makes the point most directly at Apollo. His view isn’t that poor decisions are acceptable — it’s that organisations learn almost nothing when people spend their energy protecting themselves instead of confronting reality. A wrong decision can usually be corrected. A mistake that’s denied or concealed becomes far more expensive. Michael Dell distills the whole idea into one sentence: you want to make mistakes, you just want to make them small, iterate, and fix them quickly.

The common thread isn’t a celebration of failure. It’s a determination to learn from it before it becomes expensive — and that requires honesty, humility, and an environment where people can speak openly about what’s gone wrong.

Make the Mistake Once

The best cultures are permissive, not indulgent.

Vitec’s philosophy was that it’s fine to make a mistake once. Po Chung described the same standard at DHL: anyone could make a mistake, so long as they didn’t repeat it — and the knowledge was then shared with others.

That is the line between tolerance and weakness. A hidden mistake is wasted. A repeated mistake is expensive. A mistake that is analysed, shared and embedded into the system becomes an asset. This is where failure becomes a competitive advantage — not because the company fails more often, but because it learns faster from the failures it has, and the lesson stops being trapped inside one person’s experience and becomes part of the organisation’s memory.

What Investors Should Look For

As investors, we spend enormous amounts of time looking for competitive advantages — brands, network effects, switching costs, economies of scale, reinvestment runways, capital allocation. Yet one of the most durable advantages is cultural.

The companies that keep adapting over decades have built cultures where people feel safe experimenting without threatening the survival of the business. They run small tests, listen closely to customers, remove blame from the learning process, and reallocate quickly away from what doesn’t work.

For investors, the question is never whether a company has made mistakes. Every company has. The better question is what it does with them. Does it hide them, deny them and repeat them — or surface them, learn from them, and adjust? Over long periods, that difference compounds.

In practice, this means being wary of companies that bet the farm on transformational acquisitions. It means listening for whether management talks openly about mistakes or only celebrates success. It means favouring businesses that test, learn and iterate before committing serious capital. An organisation’s error-handling system may matter as much as its strategy.

None of this shows up neatly in a screen or a set of accounts. Philip Fisher called this kind of work “scuttlebutt” — going directly to customers, competitors and former employees rather than relying on what management publishes. It remains one of the few qualitative edges that cannot be automated away, because whether an organisation learns from mistakes is usually revealed in behaviour long before it appears in the numbers.

Failure as an Edge

No organisation has eliminated failure. The ones that compound for decades have simply built a better relationship with it — one where mistakes are made small on purpose, surfaced rather than buried, and converted into something the whole organisation gets to keep.

That conversion, repeated across thousands of small decisions, is what a culture of experimentation actually buys a business: faster innovation, faster adaptation, less bureaucracy and more empowered people. People are more likely to stay because they are trusted. Products get better in small steps rather than rare leaps. Customers feel it before anyone reports it.

The companies that last are not the ones that fail less. They are the ones that evolve faster.


Follow us on Twitter : 
@mastersinvest
* Visit the
Blog Archive *


TERMS OF USE: DISCLAIMER
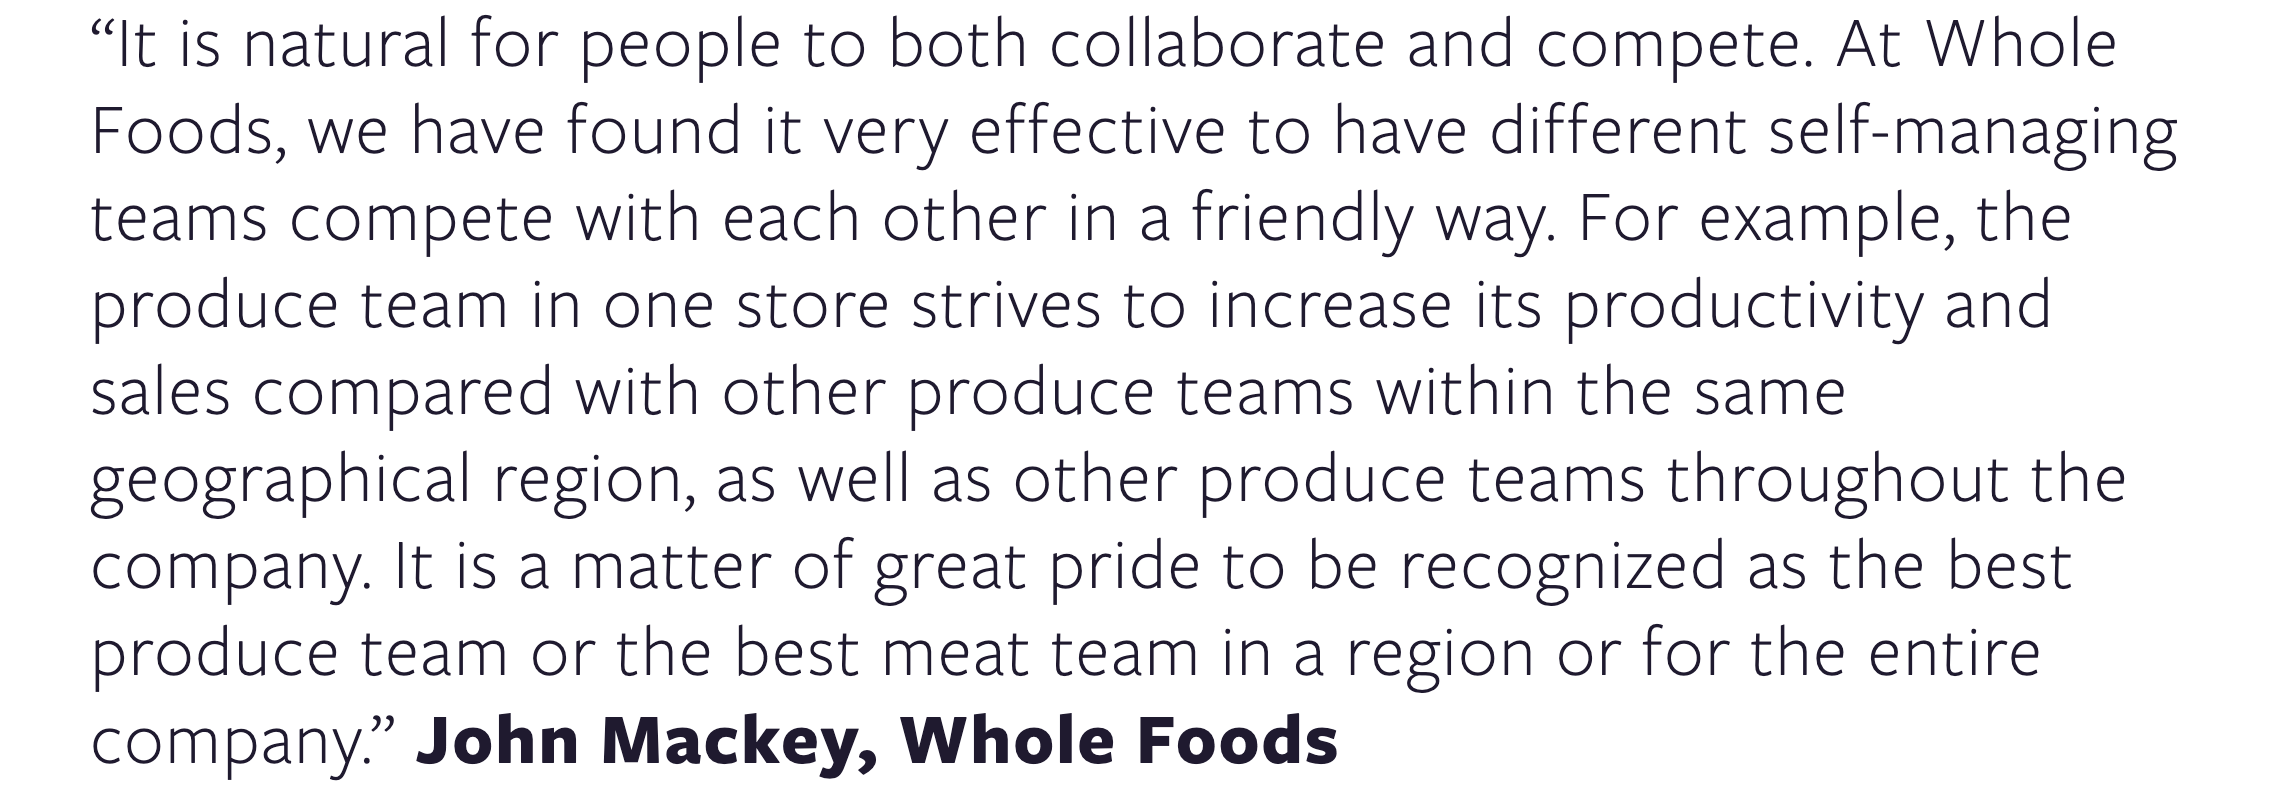
The Answers Are Already In The Building

There's a consulting industry worth hundreds of billions of dollars built on a surprisingly simple arbitrage: companies pay outsiders enormous fees to tell them what their own employees already know.

It's one of the great ironies of organisational life. The person in the corner office, armed with an MBA, a strategic framework and a PowerPoint deck, spends months searching for answers that the warehouse supervisor, the customer service rep, or the factory floor worker could have provided in an afternoon - if only someone had thought to ask.

The People Closest To The Work Know Best

Joe Coulombe, who built Trader Joe's into one of the most successful retail concepts in history, put it simply: in any troubled company, the people at lower levels know what ought to be done. Lloyd Blankfein at Goldman Sachs noticed the same thing from the opposite end of the power structure - people knew the right answer, knew the system was broken, knew what needed fixing. They just hadn't been given permission to say so, let alone act on it. His solution was blunt: ask people what should be done, then tell them to do it.

Sam Walton was equally direct. The people on the front lines - the ones who actually talk to customers - are the ones who really know what's going on. The job of leadership, in his view, was to figure out ways to get them talking, and then actually listen. John H. Patterson at National Cash Register understood it in almost mathematical terms a century ago - why rely on one superintendent's brain scanning for problems when you could harness four thousand brains and eight thousand eyes, all simultaneously alert to mistakes and improvements?

IBM's Thomas Watson Jr ran a suggestion program that attracted more than 100,000 entries a year. Toyota built an entire production philosophy around the principle that only those at the front line can understand problems fast enough to react to them quickly.

Henry Kravis at KKR tells anyone who will listen, from analysts to partners, to wake up each morning asking whether something could be done better. The source of the idea is irrelevant. What matters is that it surfaces.

Get Out of the Ivory Tower

The insight extends beyond internal operations to customers - and critically, to the customers who leave. Frederick Reichheld was unequivocal: there is simply no substitute for having senior executives learn directly from defectors why the company's value proposition is inadequate.

Terry Leahy, who built Tesco from Britain's third-largest grocer into one of the world's most successful retailers, made this viscerally real. He gave himself a challenge - one week every year working as a general assistant in a Tesco store. Checkouts, shelf-filling, back room, pricing, customer queries. Then he asked his three thousand top managers to do the same. Their combined firsthand experience, he noted, amounted to roughly sixty years on the shop floor in a single year. He learnt more in that one week than any other week that year - not from reports or dashboards, but from actually doing the work.

A consistent theme amongst many of the world’s most successful companies is getting management into the field. At Chick-fil-A, every headquarters employee works in a store at least one day each year. ServiceMaster introduced a ‘We Serve’ day, during which every leader participates directly in serving the customer - keeping management in touch with reality. The entire management of the Würth Group, right up to the group directors, is obliged to spend at least one whole day each quarter in the marketplace - in sales, visiting customers.

The best operators make field presence non-negotiable. Ed Stack built Dick's Sporting Goods into a dominant retailer by spending two days a week, three weeks a month, out in the field - walking stores, listening to managers, detecting shifts in customer demand long before anyone at a desk in Pittsburgh could. David O'Reilly at O'Reilly Auto Parts was blunt: you're either plugged in all the way or you're not.

There's no substitute for exposing yourself to your customers, your team members, and your vendors - and far too many executives simply don't do it. Brian Chesky at Airbnb spent six months living in his own company's rentals and found the core problem with his business hiding in plain sight - variability that no report had ever surfaced. Elon Musk slept on the factory floor during Tesla's most critical production crises, reasoning simply: if the team thinks their leader is off somewhere having a good time, it's demoralising. The more senior you are, the more visible your presence must be.

Two Harvard Business School professors who studied how CEOs actually spend their time found that on average, just 6% goes to frontline teams and 3% to customers. They spend 72% in meetings. The gap between those numbers is where organisational blindness is quietly manufactured.

J.W. Marriott said it plainly: companies that get into trouble are ones where the CEO never budges from the executive suite and makes decisions without knowing what's really going on. You can't rely solely on reports or secondhand information. You have to get out there and find out for yourself.

The Paradox of Expertise

Here's the uncomfortable corollary. The more senior and experienced a leader becomes, the more likely they are to stop doing the thing that made them effective in the first place.

Expertise is great, but it has a bad side effect - it tends to create an inability to accept new ideas. William Taylor calls it the paradox of expertise: the more deeply immersed you are in a market or technology, the harder it becomes to open your mind to new models that might reshape it. The people with the most experience, knowledge and resources in a field are often the last to see and seize the opportunities for something dramatically new.

This is why fresh eyes matter. Henry Ford observed that some of his best results came from letting fools rush in where angels fear to tread. The person who doesn't know something is impossible has a structural advantage over the expert who knows exactly why it can't be done.

Chester Cadieux at QuikTrip spent at least two months every year in direct communication with any employee willing to participate - and made a point of reviewing even comments raised by a single person just once, because without fail, each year he learned something important from exactly that source.

Why Most Organisations Don't Actually Do This

So why don't more organisations embrace something so obviously valuable? A few reasons, none of them flattering.

The first is ego. Leaders are selected, promoted and compensated in ways that reinforce the belief that their value lies in having answers. Admitting the answers might exist two levels below them feels like an admission of redundancy.

The second is structure - most organisations are not designed to surface information upward. Suggestion boxes and town halls are often theatrical exercises that give the appearance of listening without the substance of it.

The third is pure inertia - things remain as they are not because anyone thinks they're optimal, but because changing them requires someone to actually decide to change them.

Bill Walsh at the San Francisco 49ers put it starkly: if you're uncomfortable walking around your team's workplace, awkward and out of place, you are a disconnected leader. His coaching staff ate lunch in the locker room with players at least once a week. Tuna sandwiches and Pepsi. Barriers came down. Information flowed.

The Simplest Competitive Advantage Available

David Cote transformed Honeywell's sustainability performance not by importing expensive external expertise, but by asking the people already inside the building where energy was being wasted. Because employees developed the solutions themselves, they were personally invested in seeing them through. Joe Scarlett at Tractor Supply credits the overwhelming majority of the company's best product ideas to decades of continuous conversation with store managers and salespeople. Dick Wood at Wawa said it plainly: company intelligence is in the front line, not in the executive suite.

The answers to most of the problems an organisation faces are already inside it. They live in the person who processes the returns and knows exactly why customers send things back. In the technician who has quietly developed a workaround for the broken process that management doesn't know is broken. In the driver who has figured out a faster route that nobody ever thought to ask about.

As an investor, this is one of the most reliable signals available to you. Steve Mandel of Lone Pine Capital put it simply: you always learn more when you're outside the office than when you're in - body language, how offices are structured, little things that add up. Kelly Granat goes further: arrive early, sit in the lobby, watch who's coming in and whether they're happy to be there. Then go upstairs and notice whether the CEO talks over everyone in the room or creates space for others. All of it tells you something about how decisions are actually made.

We saw this firsthand at HEICO. Walking the floor, it was clear management's interactions with employees weren't a staged performance for visitors. They knew people by name, engaged in genuine dialogue, and asked thoughtful questions about projects and progress. It was a small detail, but a revealing one.

That culture - the one visible in the lobby at 8am, not the one described in the annual report - is ultimately what you're investing in. Companies where information flows freely from the bottom up, where leadership is genuinely curious, consistently present, and humble enough to listen, tend to improve continuously, adapt quickly, and compound reliably over time. Companies where the executive suite is insulated from operational reality tend to be slow, self-deceiving, and eventually blindsided.

The question was never whether the answers exist inside these businesses. The question - the one worth asking before you invest - is whether anyone in a position of authority cares enough to go looking for them.


Follow us on Twitter : 
@mastersinvest
* Visit the
Blog Archive *


TERMS OF USE: DISCLAIMER
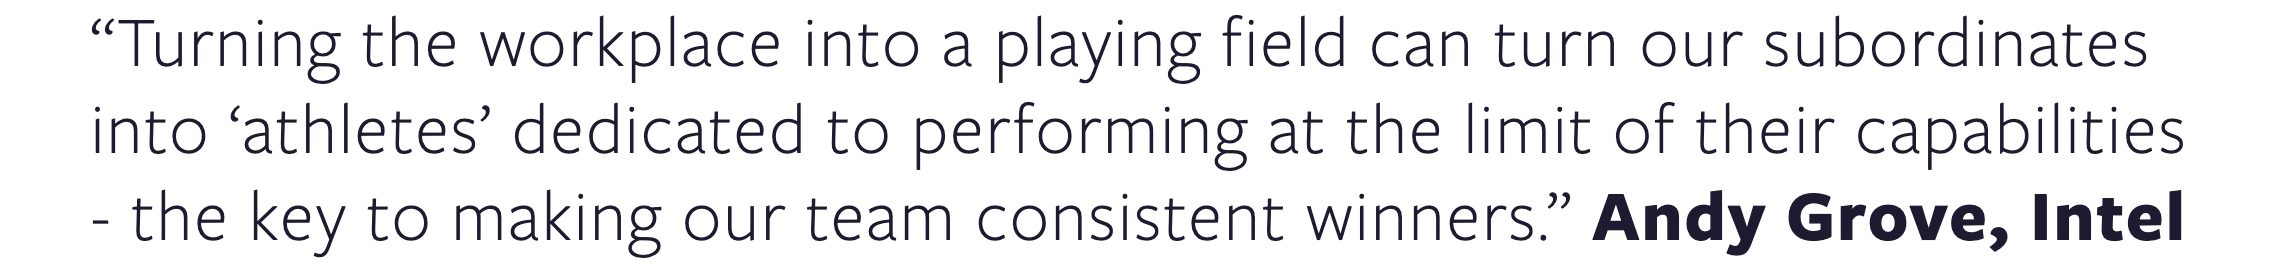
The Family Feeling

There is a word that appears, unbidden, in the writing and speeches of the founders of some of the greatest businesses ever built. It shows up in the memoirs of Ray Kroc, in the annual reports of Old Dominion Freight, in the founding philosophy of IKEA. The word is not "strategy." It is not "execution" or "competitive advantage" or "return on invested capital."

The word is family.

A pattern too consistent to ignore

When a pattern appears once, it's anecdote. When it appears across a hundred companies, spanning a dozen industries, over more than a century, it deserves serious attention.

Researcher Vicki Tenhaken spent years studying what she called the Century Club - companies that had survived and thrived for a hundred years or more. Her conclusion was striking: many of the Century Club companies' employees become lifelong, loyal members of the organisation and often compare their relationship with the company to being part of a family.

This wasn't sentimentality. These were businesses that had survived a century of disruption and competitive onslaughts. The family feeling wasn't incidental to their longevity. It may have been central to it.

Arie de Geus, the former head of strategic planning at Shell who spent decades studying long-lived companies, put it plainly: the feeling of belonging to an organisation and identifying with its achievements is often dismissed as soft. But case histories repeatedly show that a sense of community is essential for long-term survival.

Soft, it turns out, is one of the hardest things to build. John Wooden - the preeminent basketball coach of his era, winner of ten NCAA championships in twelve years including seven consecutive titles and an 88-game winning streak, and a man Charlie Munger held in the highest admiration - compressed the whole idea into a single sentence: "Teams with a sense of family have uncommon strength and resiliency."

He wasn't speaking as a sentimentalist. He was speaking as someone who had proved it, repeatedly, against the best competition in the world.

Tom Peters, whose landmark 1982 study of America's highest-performing companies - In Search of Excellence - remains one of the most influential business books ever written, identified family culture as a defining characteristic of exceptional organisations decades before it became fashionable to say so. What Peters found was not a coincidence of personality or geography. It was a pattern, repeated across industries, embedded in the operating philosophy of the companies that consistently outperformed their peers.

More recently, Daniel Coyle spent years studying some of the world's most cohesive and high-performing groups - among them Google, Pixar, the US Navy SEALs, and the San Antonio Spurs. What he found echoed the same pattern, but from the inside out.

Coyle also noticed something else: many of the most successful organisations had created their own family-esque identifiers. People who work at Pixar are Pixarians. People who work at Google are Googlers. You might add Resmedians, Ikeans, Apaches, Hormelites and Nordies - each a small linguistic signal of something larger, a declaration that working here is not a transaction but a belonging. The name is the symptom. The culture is the cause.

What ‘family’ actually means in business

Before dismissing this as corporate speak - the kind of hollow language that fills employee handbooks nobody reads - it's worth being precise about what the best operators actually mean when they invoke the family metaphor.

They don't mean unconditional love. They don't mean the absence of accountability. Peter Schutz, who ran Porsche through one of its most successful periods, offered one of the clearest definitions: a family consists of a group of people who have made a commitment to each other and to a set of shared values. When there is a problem in a family, no one individual ever has a problem. The family has a problem and will deal with it together.

Commitment that doesn't evaporate when things get hard. That is what separates companies that invoke family as a marketing slogan from those that actually live it.

The family metaphor, when genuine, also extends outward - beyond employees to the full value chain. Peters documented this vividly in his study of Caterpillar. "We have a tremendous regard for our dealers," said the company's former president and chairman. "We will not bypass or undercut them. Some of our competitors do and their dealers quit. Caterpillar dealers don't quit; they die rich." Caterpillar dealers, Peters noted, were treated like members of the family - not as a turn of phrase, but as an operating principle that shaped every commercial relationship the company held.

George Mecherle, founder of State Farm Insurance, cultivated a similar spirit. He saw himself as the benevolent father of a family, inspiring extraordinary loyalty among employees and policyholders alike. Customers proudly displayed State Farm medallions, recommended the company without financial incentive, and regarded membership almost as belonging to a fraternal organisation. Some reportedly sought membership despite not owning a car, simply to feel part of the family.

Jim McLamore, who co-founded Burger King, described the same logic with his franchisees: "We became a very successful company because we were able to help our franchisees do well. [We] viewed their success as our own success. They were a part of our family and we regarded them as such."

Howard Hawkins of Hawkins Chemical took it furthest of all, extending the circle to encompass everyone the company touched - employees, customers, suppliers and the community around them. Family, in his hands, became a way of thinking about the entire business system.

John Deere understood this distinction clearly. A family isn't unconditional - you don't support a crazy uncle who isn't behaving. Standards matter. Accountability matters. The family metaphor works precisely because it combines warmth with expectation.

Paul Ricard, who built one of France's great spirits empires, captured the reciprocal logic at its simplest: he felt clearly that it was important to treat his employees as part of a family. If he took care of their best interests, they would take care of his. There is no more compressed statement of what this philosophy actually is - not paternalism, but a recognition that the relationship between an organisation and its people is, at its best, genuinely mutual.

The science beneath the sentiment

Robert Cialdini, the psychologist who has spent a career studying influence and social behaviour, offers a framework for why this works at a neurological level. When people act in unitary ways, they become unitised. The resultant feeling of group solidarity serves society's interests well, producing degrees of loyalty and self-sacrifice associated usually with much smaller family units.

The neuroscience runs deeper still. Mark Bertolini, who led Aetna through a remarkable period of transformation, drew on research that connects the act of trust-giving to something measurable in the body:

"A neurologist discovered that when individuals were either given trust or they extended trust to others, their pituitary glands released a feel-good hormone called oxytocin. This created a biological virtuous cycle. When you trust someone their brain responds by making more oxytocin, which allows them to trust you in return. Reciprocity - doing unto others as they do unto you - seems to be a biological function; trust begets trust. I believe that to be true, and it's shaped my leadership of Aetna." Mark Bertolini, former CEO of Aetna

This is what Ricard intuited and Bertolini measured: the mutual relationship isn't just good philosophy, it is good biology. The virtuous cycle of trust is not merely a metaphor. It is part of the machinery of human cooperation.

For most of human history, survival depended on small groups that knew, trusted and sacrificed for one another. The family was the original organisation. Great companies do not fight that instinct. They build with it.

The companies that tap into this aren't being naive. They are being, in the deepest sense, strategic. They are building with the grain of human nature, not against it.

The founders who built it in

What's remarkable is how consistently this philosophy was baked in at the founding - not bolted on later as a PR exercise.

Ray Kroc at McDonald's. Howard Schultz at Starbucks. Ingvar Kamprad at IKEA. Yvon Chouinard at Patagonia. S. Truett Cathy at Chick-fil-A. Les Schwab at Les Schwab Tires. Les Schwab put it as plainly as anyone: "Our company is a large family." Seven words that contained an entire management philosophy.

Each built their company culture from the first day around a set of beliefs that prioritised belonging. Each understood, often instinctively, that people who feel ownership - emotional, not just financial - behave differently than those who merely show up for a pay cheque.

Tom Peters saw this pattern clearly among the founders he studied. Watson, Kroc, Marriott and their peers were pathbreakers in treating people as adults - inducing practical innovation and contributions from tens of thousands, providing training and development opportunities for all, and treating everyone as a member of the family. What united them was not industry or era but a shared conviction that the relationship between a company and its people was the thing worth building first.

As Keith Davies wrote of Don Plested and the early days of Mainfreight: Plested set out to make the company a family, a team, in which everyone would have a share in the riches. Join Mainfreight, and you joined a family.

The Snyder family at In-N-Out Burger carried the same conviction. In many ways In-N-Out was an employee-driven company - the Snyders displayed an uncommon respect for their workers, never looking at them as just employees but seeing them as part of their own growing, extended family. In an industry notorious for churn and indifference, that distinction showed up everywhere: in wages well above competitors, in promotion from within, and in a loyalty from staff that customers could feel the moment they walked through the door.

At Patagonia, Yvon Chouinard took it a step further — the family feeling was not merely cultural but literal. "Not only was the company like an extended family," he wrote, "but for many it was family, because we always hired friends, friends of friends, and their relatives." What began as a climbing gear startup built around a tight-knit community never lost that texture, even as it grew into a global brand. The culture didn't have to be constructed. It was simply preserved.

The Hartford brothers at A&P ran the largest retailer in America for decades on a similar premise: the Hartfords treated the company as their family, almost never dismissing employees, creating one of the first company pension plans, and shortening working hours simply because they could afford to do so.

This is the key distinction. Family culture isn't just a philosophy about how you treat people. It's a philosophy about what the company is for. The Hartfords shortened working hours not because consultants told them to. Because they could. Because their workers were family, and family shares in success.

The scaling problem — and how the best solve it

The obvious objection is that family culture doesn't scale. A founding team of ten can feel like a family. A company of ten thousand cannot. Can it?

The evidence suggests otherwise - if you're deliberate about it.

Ralph Roberts, who built Comcast from a small cable franchise into one of the largest media companies in the world, articulated the solution simply: how do you maintain that same culture? You do it by being warm and friendly. And instead of one big family, we have a lot of little families.

This is precisely the insight that explains why decentralised businesses with branch-level autonomy so consistently outperform their centralised competitors. Not just for operational reasons - though those matter - but for cultural ones. When a branch manager has genuine authority and genuine accountability, they can build a genuine family within their team. The thirty people in that branch can know each other, trust each other, cover for each other. They cannot do that if every decision flows up to a regional manager who reports to a national director who reports to a VP who has never visited the branch.

Po Chung, who built DHL into one of the world's great logistics networks, understood this as well as anyone. "Both internal and remote networks become like working with parents, siblings, cousins, uncles, and aunts. As DHL was built and organised like a large, extended family, this provided a model we could keep scaling and growing. In fact, it was the ideal model for building a global service network composed of a competent and caring team of high character." Family culture, in Chung's telling, wasn't the soft alternative to building a great business. It was the mechanism.

Wawa, the extraordinary convenience store chain, has lived this for decades. CEO Howard Stoeckel put it plainly: we're the Cheers of convenience stores, a place where you're known by name, and where the customers and associates all treat each other like family.

Carol Meyrowitz, who ran TJX Companies through years of remarkable performance, traced the company's ability to retain great people directly to its family culture: one reason TJX holds on to its best people is its culture - very family-friendly, encouraging people to balance work and home life. As a result, people tend to stay. Many of them for more than thirty years.

Retention is not a soft metric. It is the compound interest of organisational knowledge. Every person who stays another year carries with them another year of customer relationships, product knowledge, institutional memory. Every person who leaves takes that with them. As Joe Coulombe, founder of Trader Joe's, put it with characteristic directness: "Productivity in part is a product of tenure. That's why I believe that turnover is the most expensive form of labor expense."

When family culture meets financial discipline

The most sophisticated version of this idea recognises that family culture and financial rigour are not in tension. They are, in the best companies, mutually reinforcing.

Henry Kravis at KKR - not an organisation typically associated with warmth - has spoken about it in exactly these terms: it's important to remember that KKR is our family business. We did go public and change our shareholder base in doing so, but George and I remain the largest shareholders to this day and our culture still has that family business mentality.

Marc Rowan, who built Apollo into one of the world's great alternative asset managers, goes further - and gets more specific about what living this philosophy actually requires at scale:

"The business ultimately runs on experience. That only lasts if your partners stay with you for their entire career. If they're going to stay with you for their entire career, we have to recognise they're going to have, outside their careers, a bunch of happy things that happen to them and a bunch of sad things. How we deal with people in these moments that matter — at 4,000 people, 6,000 people — it's really important. It's actually almost more important than anything else we do."— Marc Rowan, CEO of Apollo Global Management

This is the mechanism Bertolini's research describes playing out across a career. Every act of showing up - for a bereavement, an illness, a celebration - deposits a little more trust, extends the relationship a little further. At scale, across thousands of people over decades, that compounding is the business.

Bill Ackman at Pershing Square makes the connection between culture and outcomes explicit: the firm's unique family-oriented culture, the powerful economics of the business, and its widely dispersed economic ownership make it a special place to spend a career. A small scale and long-tenured employee base also reduce risks - particularly important in a regulatorily sensitive industry.

Long tenure. Reduced risk. Powerful economics. These are not accidents. They are the downstream consequences of culture built on belonging.

When the family includes the town

Sometimes the family feeling shows up not in words but in brick and mortar.

J. Irwin Miller ran Cummins Engine in Columbus, Indiana for four decades and used the company's profits to fund architect fees for public buildings - commissioning Eero Saarinen, I.M. Pei, Richard Meier to design schools, churches and civic buildings in a small Midwestern town. A town of 50,000 people with one of the most extraordinary collections of modernist architecture in the world. Not because it was good marketing. Because Miller believed that a company's family extended to the community around it, and that a family takes care of its home.

Implications for investors

So what does this mean for those of us trying to identify businesses worth owning for a decade or more?

Family culture is a moat. Not in the conventional sense of patents or network effects or switching costs. It is a moat because it is genuinely difficult to replicate and, once lost, extraordinarily hard to rebuild. You cannot hire a consulting firm to install it. You cannot acquire it. You cannot mandate it from a head office. It grows slowly, from the values of founders and the experiences of the people who live inside the business every day.

Look for low staff turnover. This is the most reliable observable signal of genuine family culture. Graco's average employee tenure of eleven years. TJX executives with thirty-plus year careers. Old Dominion drivers who retire with the company they joined as young men. These are not HR statistics. They are evidence of something real.

Look for founders or families still involved. The companies in this collection - Chick-fil-A, In-N-Out, Comcast, Wawa, Nebraska Furniture Mart, Cintas, LVMH, ABC Supply - are disproportionately founder-led or family-controlled.

This is not coincidence. Founders and families have a different relationship with the business. It is theirs in a way that a professional manager's company never quite is. They are willing to suffer short-term pain to protect something they intend to pass on.

As Katharine Graham observed, family ownership can also prevent the kind of disruptive takeovers that destroy what took decades to build. Quality, she argued, may be nourished most easily by families whose perspective extends beyond the immediate horizon.

Look also at how the best operators think about shareholders. Buffett's Owner's Manual asked investors to visualise their Berkshire stake the way they might think of a farm held "in partnership with members of your family" - not a piece of paper to be traded, but a permanent commitment. He didn't want a revolving door of shareholders any more than he wanted a revolving door of managers. Building an ownership base with the loyalty and permanence of a family is, it turns out, both a cultural achievement and a competitive one.

Be suspicious of rapid centralisation. When a company that built its strength through distributed, branch-level culture begins consolidating in the name of efficiency, the family feeling is usually the first casualty - and the financial results follow, often with a lag that deceives investors until it's too late. The culture breaks before the numbers do.

Listen to how leaders talk about their people. The language reveals the reality. Howard Stoeckel describing Wawa as the Cheers of convenience stores. Ralph Roberts of Comcast inviting employees to call him directly. David O'Reilly tracing O'Reilly Automotive's philosophy back to its founding family. Marc Rowan describing how showing up for his people in the moments that matter is almost more important than anything else he does. These are not PR statements. They are the visible surface of something much deeper.

Value what you cannot easily quantify. The discounted cash flow model will never capture the value of a culture that causes people to stay thirty years, to bring their children into the business, to feel genuine grief when a colleague leaves. But that culture is compounding, invisibly, every single day. And over a decade, over two decades, over a century - it shows up unmistakably in the numbers.

Paul Ricard's formulation stays with you for its simplicity: take care of their best interests, and they will take care of yours. Mark Bertolini confirmed it in the chemistry of the pituitary gland. It is not a management technique. It is a description of how trust actually works - slowing accumulated, easily destroyed, and worth more than any asset on the balance sheet.

The greatest businesses in history were not merely managed. They were loved. And the investors who recognised that love - not as sentiment, but as a durable economic asset - earned returns no spreadsheet could have predicted.


Follow us on Twitter : 
@mastersinvest
* Visit the
Blog Archive *

TERMS OF USE: DISCLAIMER

Learning from Sir Christopher Hohn

In his third year at a New York hedge fund, Christopher Hohn had a huge year — and they paid him a US$10 million bonus. Most people would call that “making it.” He didn’t.

Hohn says he immediately gave it away — set up a foundation and put the money into it. “I didn’t want it… This isn’t really something I should have.” Then look at what he did next.

When he launched his own firm, he didn’t reach for a predator or fortress name — no Tiger, no Viking, no Citadel. He called it The Children’s Investment Fund. The name wasn’t marketing. It was a statement of intent.

Because to Hohn, money is not identity. Maybe that’s easier to see when you’ve come at the game as an outsider: the son of a car mechanic, raised in a small town — a Jamaican-born father and a legal-secretary mother. It’s not even the endgame. It’s a tool — almost a commodity — and his deeper view is simple: you’re a steward, not an owner. You’re passing capital through your hands. It takes some people a lifetime to see that you can’t take a pin with you.

Chris Hohn’s investing legacy is as striking as his approach to life. Over more than two decades, TCI has compounded at more than 18% a year — roughly nine percentage points ahead of the market. This has been achieved through a holding of around fifteen stocks, with the top ten position sizes generally between 8% and 13%. These aren’t hidden gems — companies nobody has heard of. The majority of the portfolio (c90%) has comprised companies with market capitalisations above $50 billion: names like General Electric, Moody’s, Canadian National, Visa and Microsoft.

With fewer than ten investment professionals, and more than $77b of funds under management, the fund — according to the Financial Times — has generated $68.4bn in cumulative gains for investors after fees since its founding in 2003. In 2025, the fund generated a net return of 27%. According to Forbes, the firm’s latest annual report (as of March 31, 2025) says that for the prior year it donated $797 million to charity, including $637 million to The Children’s Investment Fund Foundation.

What distinguishes Hohn, as an investor, is the severity of his focus: an almost obsessive attention to competition; a quest for multiple, layered barriers to entry; a time horizon measured in decades; and a love of an often underappreciated asset — pricing power. He discards most industries without regret.

Hohn has gravitated toward quality: fewer positions, longer holds, and a hunt for “super-companies” that don’t fade. That persistence is the wrinkle — most models truncate the runway, so the real value in the outer years goes underappreciated. He calls long-termism in a great company a free lunch — the same edge that built the records of Buffett and Munger, Chuck Akre, Nick Sleep, Steve Mandel and David Polen.

He’s also evolved in how he behaves as an owner. There’s a symbiosis with management — constructive, engaged, but not deferential. He cares more about a company’s DNA than any single executive, yet he’s willing to use his position to press for (or block) corporate actions he believes would destroy intrinsic value. Not activism as theatre — ownership as responsibility.

I’ve long admired Hohn. As investors, we can learn plenty from his craft — and maybe even more from his posture: purpose first, money second… capital deployed in service of something that outlasts you.

Having studied many of the world’s greatest investors, his lessons land with the same force whether you’re a newcomer or a veteran. I recently spent a morning revisiting his public interviews and talks, and I’ve collected my favourite extracts [lightly edited for clarity] below.

Risk versus Return

“Investing is all about risk and return — and the vast majority of investors focus on return. You see it with any asset allocator: what’s your return? That’s the only thing. But I focused my career on risk. Return does matter, of course, but to me, risk was always the first thing that mattered.”

“One of the things about our strategy is we actually don’t like risk. We take risk, but we want low-risk businesses that will get our capital back. That’s why we don’t seek the highest return. If we’d invested in Tesla, we’d have been much richer, but it’s a risky company for us. Increasingly, I think of us as a ‘stay rich’ fund because the business models are so strong, and we’re always very focused on valuation as well.”

“Warren Buffett was asked what the definition of risk was. You know what he said? ‘Not knowing what you’re doing.’”

Learning

“Like everyone, we’re always learning.”

“Through engagement, you can learn something. If it’s a one-way conversation — if you’re just speaking at someone — you don’t learn anything. We have to learn.”

Humility

“Be humble. If you become arrogant, that’s a killer in the investing business.”

“We want to hear competing views. We have some members of the team who are inherently bearish, and they’re good for testing the bear case. We always want to hear: how could technology disrupt? Or what could competition do?”

Unconstrained Thinking

“It’s often said that as an immigrant you feel more like an outsider — and outsiders challenge the establishment. Part of my psychological makeup was to think in an unconstrained manner. Harvard Business School taught me there was no reason to assume people were smarter than you.”

Temperament

“Investing isn’t that hard. The hard part of investing is - Warren Buffett said it - temperament. You need the right temperament.”

Keep it Simple

“We keep things very simple. The strategy works.”

Intuition

“Another key point is intuition. We work with intuition. It’s been defined as thinking without thinking, which the Buddhists would call a koan — something that just doesn’t make sense. A lot of people don’t understand what intuition is. It’s sort of the opposite of intellect. Pattern recognition, in a way — you’ve seen it. It’s knowing.

Of course we’ll do analysis, but it’s a higher level of intelligence than just intellect. And it applies to everything: is someone trustworthy or not trustworthy, and the patterns. I wasn’t into intuition so much before the last five to ten years — that’s been a change — but I think I always operated at an intuitive level.”

“Investing’s an industry where you learn from experience—by osmosis—as much as, or more than, from any single mentor.”

Permanent Loss of Capital

“What kills you as an investor is permanent loss of capital.”

What Matters

“It was a spiritual master who once said, very few things matter, and most things don’t matter at all.”

“You need to get out of the noise and just focus on the handful of things that matter.”

Competition and Barriers to Entry

“Competition kills profits. Yep - it’s as simple as that. Substitution eliminates your business.”

“Competition matters because too much competition erodes your profits — and maybe you don’t make any money at all. So I hate competition. Competition makes predictability and valuation impossible. And the interesting thing is: to me, in a sense, competition and disruption are the whole thing.”

“Warren Buffett said most moats aren’t worth a damn — because you think you’ve got a moat, and then it erodes. So the real thing is the sustainability of moats.”

“The fact of the matter is that most investors underestimate the forces of competition and disruption because they underestimate complexity. They look short-term. And so we do two things, really: we look for companies with such high barriers to entry over the long term that we think we can have a reasonable idea they’ll still be around. Okay — we can’t be precise about exactly what they’ll be worth, but they’ll be there not in one, two, or three years, which is the normal time horizon of an investor, but in 20 or 30 years, which is where the value — if you do an NPV model — really is. And so we try to focus all our time on barriers to entry and disruption.”

“It’s all very well to say you’re long-term, but that’s only a good thing if it works. And it only works if you’re right on the first point: the quality of the company and the barriers to entry.”

“We're totally focused on fortress business models, where competition is limited and very difficult and so they have very high barriers to entry. This is the classic Warren Buffet mindset, quality companies.”

“Moats change. We used to love consumer staples, but they became richly priced and offered low returns. We used to like media content companies, but streaming severely weakened their moats. Disruption can happen — you’ve just got to stay alert to it.”

Don’t Sell

“If you’re right — that you’ve found a company that’s going to be a good company long term — then you should hold on to it, because there’s a persistence to the barriers to entry and the things that make it good. So, in simple terms: good companies stay good, and bad companies stay bad.”

“There aren’t that many great companies — the super-companies of the world — and if you find them, you should hold on to them.”

Quality Companies

“Ultimately, the quality of the business trumps everything.”

“We say maybe there's 200 companies that we consider to be high quality and investable.”

“We invest in high quality companies with predictable free cash flow.”

“Here’s the thing: the longer you can look out, if you’ve got a great company, the more value there is.”

“Actually, the compounding of intrinsic value matters more than the stock price. If you have a great company, it will grow intrinsic value. And here’s the thing about multiples: they matter less than the growth when you look at it over a longer period. But most investors are unwilling — or unable — to invest on a long-term time horizon.”

“If you look empirically, it turns out that the very best companies — high ROEs — stay good. They don’t disappear overnight, generally. And bad companies stay bad — low ROEs stay low. There's persistency.”

“The value of [a great] company is only really seen over the long term. They say there’s no free lunch in finance, but I do think long-termism in a great company is a free lunch. Because if you look at any sell-side model, they’ll go out three years — or two years. Why? Because that’s the time horizon of the typical buy-side investor: one or two years. But what if it can keep being good for 30 years? Then you’re completely undervaluing that company. And people don’t look at it because most companies — 95% — are mediocre or bad. They meet their cost of capital, but they’re not super-companies.”

“We’ve become more quality-focused in our choice of companies. When I started, I’d look at anything - banks, miners, steel companies. Over the years I realised there are good companies and bad companies. I became more discerning: good is better. So we’ve become more quality-compounding focused.”

“We’ve gravitated towards quality. We believe what Warren Buffett said: a cheap but questionable business is inferior to a fairly priced, high-quality company -because bad businesses surprise you on the downside, and good businesses on the upside.”

“There are many investors who will buy a company, independent of valuation, as long as it’s a good company, but we won’t.”

Business Focus

“I was always willing to look at the company fundamentals, and not try to guess the stock market - or focus on macro, or trading. I was always fundamental. Most investors are not fundamental. They trade actively. They look at data points. They say, ‘What’s the catalyst?’ They don’t really know what the company does. So I think the fundamental approach has been key.”

Physical assets

“I’ve always liked hard assets — infrastructure — and what comes within that can expand beyond. We’ve owned a lot of airports and toll roads. We found toll roads in Europe, then toll roads in Canada and the U.S., through Ferrovial — and then cell-phone towers, and railroads, and so on.”

“There are many, many moats — and one that most people don’t look at, interestingly, is irreplaceable physical assets. We’re in a world where people just look at earnings. They don’t look at asset value, or physical assets. And so we like quite a bit of infrastructure.”

Network Effects

“We found other barriers to entry, such as network effects. Certain industries — payments is one. We’ve been a shareholder of Visa a long time, where it has this huge, ever-growing network connecting every customer and every bank to the world. And as the network grows, it becomes ever harder to replicate.”

Intellectual Property and Multiple Barriers to Entry

“Aerospace is a sector that we’ve come to learn about and understand, and where the barriers to entry are multiple. Often you would like not just one barrier to entry, but maybe five — intellectual property; brands; hard assets; contracts; network effects. We’ve been big shareholders in aircraft engines, where you have many of those.”

Aircraft Engines and No New Entrants

“One space we like is aircraft engines. It’s a very complicated product because of the materials complexity — the engines run at such high temperatures that metals melt — and so many different things have to come together. Thousands and thousands of complex parts.

So that’s a business where there are only two players in narrow-body engines and two in wide-body, and there’s been no new entrant for more than 50 years. The last new entrant was GE — and that tells you something. It’s a big industry, but it’s so complex, and very hard to enter.”

Installed base

“Installed base is another barrier to entry — where customers can’t switch, because of regulatory switching costs. And so we’ve expanded into other areas: rating agencies is another one.”

Regulatory Risks

“[In a regulated business] regulators may come knocking on your door. Every case is different. And the ideal case is that there is competition but weak competition and apparent competition… An example: you might look at Heathrow Airport and think, ‘Oh, that airport is fully regulated — airports can’t be good.’ But if you look into the detail of AENA, it’s a different animal. It has a piece that’s regulated, and a much bigger piece — 70% of value, maybe more — that’s unregulated. So maybe the regulated business gives you a bond-like return of 7%, but the unregulated piece can give you a much higher return.”

Pricing Power / Under the Radar

“If you really do find one of these super-companies that can dominate their industries, they have something special: pricing power — which is a rare thing. Most companies don’t like to talk about it. And it’s a special thing because it means you can grow more than your volume. It has a leveraged effect: if you can price above inflation — that’s what pricing power is — there’s no cost to that. And if you have a 10% margin, every one point of real pricing power is massive.”

“Growth can come from two forms: price and volume. And most companies don’t have pricing power. They can only price — if they’re lucky — at inflation, and that’s why people don’t focus on it. They don’t even look at where growth comes from; they just assume it’s volume plus inflation. But there is a special group of super-companies that can price above inflation — and that’s, as Buffett taught, the test of whether you have the moat. Real pricing power above inflation can be very valuable, because if you can price 1% above inflation and you have a 20% profit margin, your profits will grow 5% faster than revenue. People don’t go into it or analyze it because there are so few companies that have it — but it’s something a lot of our investments have.”

“How do we know if a business model is really strong? Well, there were some clues given by the investment genius Warren Buffett. He said a really strong business has pricing power. It can raise prices above inflation—meaningfully above inflation.”

Obvious Ideas

“You really want something that’s obvious. Warren Buffett used to talk about this: when it’s not obvious, you probably just leave it alone, because it’s probably not sustainable. So it’s sustainable barriers to entry.”

“If we own an airport, it’s pretty obvious. We own a company that owns all the airports in Spain — we’ve owned it for a decade. I was on the board. No one’s ever going to rebuild those and overbuild you. And 75% is unregulated. Or toll roads where you have 100-year duration, or 60 years. We don’t know whether people will drive electric cars, or which brand of electric car — but it’s pretty clear they’re going to need these roads. So those are obvious things.”

Essential Need

“You need something that’s essential, so you’ve got to be confident of the need. Are people still going to want to fly? We believe that’s a durable need.”

“We don’t like discretionary things. I’ve never been an investor in the handbag business. Lots of people have, and they’ve made lots of money in it. But I’ve never understood what makes one handbag better than another — or why it’s essential. So anyway, it may well be I don’t need to understand everything. Stay within your sphere of competence. That’s what Buffett said.”

“What’s most important for us is something slightly different [than recurring revenue]: an essential product or service. We don’t like things that are discretionary.”

Growth

“Depending on valuation, you don’t necessarily require a fast rate of growth. And growth can come in two forms — volume and price — so you have to break it down.”

“If you have low volume growth but a lot of pricing growth, that’s actually more important because of the leveraged effect — there’s no cost associated with it.”

“A lot of investors get confused and think the thing you want is growth. If you look at industries like airlines, they’ve been growing for 100 years — maybe 5% a year — fantastic growth. But collectively and cumulatively, the industry never made any money because competition was too strong.

So growth per se — growth by itself — is not a guarantee of making money. You need, critically, barriers to entry and protection from competition, and sustainable value-add — high value-add — that you can charge for. It’s really the combination of barriers to entry and high value added. And of course, then growth has value.”

Management

“Does management matter? Somewhat — it’s not the key thing. A great manager in a bad business can’t necessarily do much. So I think focusing on trying to assess management through conversation may miss the point. You may overstate the value of management. And sometimes management won’t even necessarily understand their own pricing power — and their latent pricing power.”

Disruption is Rising

“I think the world is changing so much that some of these apparent moats are being beaten down by AI and other disruptive forces. So the forces of disruption, I would say, are actually rising.”

Company Relationships and Activism

“Today our relationships are generally very, very constructive with companies - but it wasn't always that way.”

“I've learned that actually activism, hardcore activism, is not a great thing.”

“We act as owners. We always act as owners. What does that mean? We’re interested. We’re engaged. We think we have a right to appoint directors — we have a legal right to it. And one thing we’ve learned is: governance does matter.”

Incumbency / Large Companies

“I do think the very best companies in the world are public companies - not every one, but generally. And one of the reasons is, in many industries, scale and scope matter. Small is not beautiful.”

“There’s a lot of power in incumbency. This is another important point. Take a company like Microsoft, which we’ve invested in. One of the barriers to entry is bundling — because it creates customer switching costs.

What do I mean by this? The Office franchise, which we’re all familiar with, has many products in it: word processing, Excel, email, security — different things — and they sell it as a bundle. They don’t disaggregate it. And when a new product, or a potential competitor, enters, they can add it to the bundle.

So Zoom came out with video conferencing, and Microsoft had to respond. They launched Teams, and they were able to distribute it through the bundle — effectively free to everybody. And even though Zoom, some people believe, was a better product — or is a better product — Microsoft won that battle because they had the installed base, the incumbency, and high switching costs. Once people are using their Office software, they don’t want to switch.

And so people started using Teams — something given to you free. Why? Because it was good enough. It didn’t have to be the best if it’s free.”

Industries to Avoid

“We don’t like banks — the low quality of earnings — because they’re very leveraged, and much more than people think. People look at equity to risk-weighted assets, but what matters is equity to total assets. Many banks have been run at 100 times. And, two, they’re opaque. You can’t really look into the balance sheet from the annual accounts.”

“The other reason with banks is very important: sooner or later, you may find someone without a lot of intelligence comes to run them — and then it can be toxic. People go for growth — Anglo Irish Bank, if you remember that one — and they can destroy shareholders. Bonuses, you know. Bear Stearns — you know. Non-alignment of interests, with leverage and opacity.”

“The auto industry is obviously a commodity, retail, insurance, commodities, commodity manufacturing, tobacco, the truth is, anything in most things in manufacturing - most industries.”

“I’ll list you a couple more [bad industries]: traditional asset managers — bad businesses. Fossil fuel. Utilities — bad businesses. Airlines — bad businesses. Wireless, telecom — bad businesses. We think media is bad. Advertising agencies. It’s a very long list. Why? Because it’s competitive — with existing players and new technologies.”

“Certain industries are more prone to disruption than others. Your risk is much higher. So we try to avoid those sectors — because you’re asking for trouble — or limit our exposure. And one of those sectors is technology.”

“We have figured out a lot of industries which have these high and sustainable barriers to entry and we pretty much ignore all other industries. We focus on a limited number of industries that we really understand, that we’ve done decades of work on, and we research them in great depth. Once we’re convinced, we stick with them long term. And so we don’t need hundreds of ideas.”

Shorting

“At a high level, we learned that shorting isn’t a great business — because you can be right, but not be able to hold it, or fund the losses.”

“I’ve never really been a significant short-seller. I don’t think I’ve cumulatively made absolute money in it. And I sort of agree with what Warren Buffett told me one night. I had dinner with him, and I asked him about shorting, and he said he didn’t do it because he and Charlie Munger concluded it was just too hard — too unpredictable.

He thought long and hard about it, because in shorting you need to also understand investor psychology.

When the short goes against you, you have to fund the losses. People think that’s a costless thing, but you have to sell longs to fund the losses on shorts. And you can eventually be right — but can you hold your position? It’s a very hard thing, and you could be squeezed.”

“I never really believed in the long/short model. We’ve been substantively long. We’ve had shorts periodically, but they’ve generally been 0% to 20% in aggregate. They’ve underperformed markets, so they’ve added alpha, if you like, but not absolute dollars. One of the big advantages of being long is you can collect carry. By carry, I mean the natural intrinsic value underlying the security—whatever that number is, 10%, 20%—you’ve got that tailwind. When you’re short, you have to be right on timing, which is a bet on investor psychology, and it’s much more difficult. You also have asymmetrical risk/reward. So the logic of shorting never really made sense. I think a lot of funds do it to justify a high fee structure, or because investors expect it of them.”

Portfolio Concentration and Position Sizes

“Another thing we’ve done is concentration. We’ve owned a few things. We may have 10% type holdings — 10 stocks, 15 stocks. We don’t own 100 things.”

“We’ve used concentration to great advantage. But, of course, it’s a double-edged sword, and you shouldn’t use it if you don’t have that level of conviction. If there are times where you don’t, then be diversified. It only makes sense where you have outsized risk/rewards and conviction. That’s our formula, if you like, for how we size positions. We size them as a function of risk/reward and conviction.”

“We think about concentration as an important way to add value to our process. It was George Soros who said, “It doesn’t matter if you are right or if you’re wrong in investing — all that matters is how big you are when you’re right and how big you are when you’re wrong.” That’s so logical, but most people can’t develop conviction and they have extreme diversification.”

Long term / Portfolio Turnover

“Long termism is key.”

“Taking a long term view gives us a time horizon arbitrage.”

“I think the key for us is to mantain our core philosophy of long-term investing. As long as we still believe in our position, we won't let the markets change our mind."

“Long-termism. You can find a great company, but if your time horizon is very short, you’re at the mercy of the vagaries of what Keynes called the voting machine. He said: in the short term, the market is a voting machine — and only in the long term is it a weighing machine.”

“The average holding period of our current portfolio is eight years. I'm not saying that's the limit. Some we've held for 13 years, but it could be 10. It could be 20.”

“I like things that will just compound long term. I don’t change year to year very much. Things that I feel confident will be around in 30 years, in a dominant position, excite me — because it’s predictable. I value predictability.

Most investors are looking for the next hot thing — the new thing.

And sometimes I’ll say, a bit sarcastically: do you need to change your wife every year? You wouldn’t ask that question because you’re happy with her. It’s not that easy to find the right partner. It’s not that easy to find the right investment. So why do you want to change them immediately?

If you find something good — and it’s going to be good long term — stick with it, and don’t assume newer is always better.

Investors don’t think about sustainability. They want the next hot thing. So many people think in terms of what Benjamin Graham said: in the short term, the market is a voting machine. What’s hot? What’s new? But in the long term, it’s a weighing machine.

In Covid, Peloton was hot. It went to a $50 billion valuation. Everyone was on their Peloton machine. It virtually went to zero.

That’s the most important question. We’re more interested in: what’s going to be around — rather than what’s new?”

“We’re not churning our portfolio on a daily basis like many funds. We might hold a stock five years, ten years. One of the important parts of our strategy is we’re long-termists. We really believe in the power of not trading, low turnover, and just buy and hold - as long as the company is delivering and the business model isn’t at risk of disruption.”

When to Sell

“[Sell] when your view is that the intrinsic value is not as good as other things — not just value, but conviction. So the philosophy has two components, if you like. First: intrinsic value — the price still has to be at or below intrinsic value. But there’s a second point, which isn’t really focused on by many investors: conviction.”

Public versus Private Equity

“Like everything, there are pros and cons with private equity — arguments for and against. But in private equity, you pay a price for control. You pay a premium — and it can be big. Don’t get me wrong: control has value. It has a value. But is it worth 40% — or whatever premium you have to pay in a competitive auction? In public markets, there’s an offer every day. You can take it or leave it. So I just think that point is relevant: entry price matters.”

“If you're wrong in private, there's no way out, in the short term. And if you're wrong in a public you have a chance to get out. You have a chance.”

The Inner Life

“I’m very interested in the spiritual world—that’s another major passion. I’m not religious, but spiritual. I meditate on a regular basis. And I like nature. I like going into nature and stilling the mind. Those are my other passions.”

Reading

“I like reading.”

“I like the biography of Warren Buffett, The Snowball. I think that’s a great book on his life. Books on some of the great icons - Jean-Marie Eveillard from First Eagle. Books on George Soros - The Alchemy of Finance and reflexivity. Seth Klarman’s early work. Outliers is a good book. Joel Greenblatt’s book - there are many. Poor Charlie’s Almanack about Charlie Munger - that’s quite a good one too.”

Purpose Through Philanthropy

“When I was 20 years old, I met children living in extreme poverty for the first time. Like all children, they were precious – but the circumstances around them, the system they had been born into, had taken opportunities away from them. At that moment, I made a commitment: if I ever had the resources, I would work to address the barriers that prevent children from living healthy, happy lives. This commitment has driven every aspect of my career.”

“I don't really care about money, other than its value in helping people.”

“For me, I could never find any purpose or meaning in my life except service. That’s something that comes from within — and that’s the origin of my philanthropy.”

“I always had more pleasure and meaning from philanthropy than from consumption.”

“I know so many wealthy people in my industry—very unhappy. I’ve always found fulfillment and meaning from the service side.”

“My first love was always children because you can see the purity of the soul so much more clearly in a child. But my whole life is to serve humanity in whatever form is needed: health, education, child protection — and also climate change.”

“We have about six and a half billion dollars in the foundation, and I also do philanthropy outside of that. And so between us, we're giving away over $500 million a year two main areas, climate change and children's health in Africa and India on the health side, we focus on foundational issues.”

“This concept that we own things — I’ve always thought, actually, I don’t own anything. I’m just a custodian. It’s money. Mine needs to be given away, and put in service to humanity.

And if you go out of the intellect into intuition — which is what made me give away that money — then, when we’re on our deathbed, I don’t think we think we own things. And why would we? Because, ultimately, everything is a gift.

I didn’t make all this money because I was smart — or lucky. I think it’s because I’m willing to give it away. And I think the most important thing, back to what matters, is consciousness and love. If we connect to that, we’ll find purpose.

And so, for me, in a nutshell: philanthropy has given me purpose.”

Life Lessons

“Follow your passion. Life is too short not to enjoy every day. Find out who you are - discover who you are - self-analysis. People think life is about doing things - what you achieve - but that’s wrong. The real secret of life is who you become. Figure out who you want to become, not what you want to do. At the end of life, nobody focuses on what they did - it’s who they were.”

Summary

In the end, Hohn’s edge isn’t a secret screen or a clever trade. It’s a philosophy — and a filter.

Hohn’s worldview is a set of preferences: simplicity over complexity; risk-first, not return-first; long-term over short-term; business over management; fundamentals over macro; price growth over volume; dominance over competition; essential over discretionary; quality over cheap.

It’s also patience over activity; large companies over small; intuition over intellect — with concentration over diversification, a few industries over many, and multiple moats over a single moat.

From there, the craft follows: own a dozen or so great businesses; demand durable barriers; respect pricing power; hold for years; stay humble; keep learning.

But beneath the craft is something rarer: a view that capital is stewardship, not identity — and that the point isn’t just to compound money, but to compound meaning.

As Hohn put it:

“And there are many paths to connect to it… Through suffering, you eventually come to learn that the spiritual world is not just real, but it’s the whole thing… and that’s the only source of real purpose and meaning and joy… And I think that if you crack that, then everything else is easy.”

Sources:
‘The Children Are Our Future with Sir Chris Hohn,’ FEG Insight Bridge, 2025.
‘
Sir Chris Hohn: The Full Interview,’ Money Maze Podcast, 2021.
‘
Investing & Philanthropy - with Sir Chris Hohn,’ Money Maze Podcast, 2025.
‘Sir Chris Hohn - In Good Company,’ Nicolai Tangen, Norges Bank Investment Management, 2025.
‘
Letter #280: Chris Hohn and Christian Sinding,’ Kevin Gee, 2025.
‘
Sir Chris Hohn Transcript,’ Iceman Capital, 2025.
‘
Founders Message: Sir Christopher Hohn,’ The Children’s Investment Fund Foundation.
‘
Activist Investing Creates Inefficiencies — and Opportunities,’ Institutional Investor, 2014.


Further Reading:
‘
Beyond Investing.’ Investment Masters Class, 2021.


Follow us on Twitter : 
@mastersinvest
* Visit the
Blog Archive *

TERMS OF USE: DISCLAIMER
What I learned from reading in 2025

Reading 2025 - Top 30 [Top to bottom]

Each year I set out to read widely — across business, sport, art, psychology and history — knowing full well that it rarely follows a straight line. One book leads to another, then another rabbit hole opens. A footnote becomes a biography; a passing reference turns into a month-long detour. That wandering is the point. Pattern recognition is the by-product. Over time, ideas begin to rhyme — across centuries, disciplines and personalities — and judgment quietly improves.

This year’s reading spanned founders, operators and creators — from The Wright Brothers to Hugh De Pree’s Business as Unusual, from Bill Walsh’s The Score Takes Care of Itself to Van Gogh: The Life — united by an obsession with craft, culture and the compounding effect of small, daily improvements.

Culture Compounds

One of the clearest themes to emerge from this year’s reading was the power of culture. From ESPN to Herman Miller, the most enduring organisations share invisible foundations — trust, autonomy, ownership and purpose. The best leaders don’t impose control; they design systems where good judgment can spread. Hugh De Pree described it as “a community of accountable contributors.” When done properly, culture becomes an asset that quietly compounds year after year.

The Lessons of History

One of the recurring reminders was how little truly changes. History doesn’t repeat, but it certainly echoes.

The lessons in R.W. McNeel’s book written in 1927 — three years before Warren Buffett was born — mirror much of Buffett’s thinking decades later. The ‘Golden Rule,’ so central to J.C. Penney and the founder of Samsonite, reappears again and again in today’s most successful businesses.

The technological revolution that followed the invention of the microchip in the 1960s and 1970s offers a useful parallel for today’s explosion in artificial intelligence. Bob Noyce, co-inventor of the integrated circuit and co-founder of Intel, understood that the true impact of the microchip would unfold over decades, not quarters. Different eras, same principles.

The Long Game Wins

Another pattern that surfaced repeatedly was the primacy of the long game. The most durable advantages were built by resisting the quick fix and optimising for longevity. Alan Nesbitt of Capital Cities described “doing the right thing” as a roadmap — avoiding short-term solutions in favour of the long-term interests of the organisation and its stakeholders. Ralph Roberts made the same trade-off explicit at Comcast, accepting short-term sacrifice to protect long-term growth in earnings and value. François Michelin went further, arguing that the true capitalist must think like an ecologist — looking far into the future. John Malone captured the idea succinctly, noting that control allows leaders to ignore antsy Wall Street demands and make decisions that compound over decades rather than quarters.

The Unconventional Path

The unconventional path appeared everywhere. Picasso, Pissarro, Gauguin and Pollock were dismissed precisely because they saw differently. Their work looked wrong before it looked inevitable. The same pattern holds in business. Sony began as a small post-war Japanese start-up making rice cookers and tape recorders, ridiculed for betting on consumer electronics when Japan was known for cheap goods. McCain Foods started as a modest family potato operation in rural Canada, choosing frozen food and long-term partnerships over quick profits. Like DHL, ESPN, CNN and Hyundai, these were improbable ideas at inception.

Innovation almost always starts as heresy — a rejection of prevailing logic — before history quietly rewrites it as common sense.

Fanaticism as a Virtue

Across all these stories ran a streak of fanaticism — not excess for its own sake, but devotion. Jimmy Pattison wanted to work and hated holidays. Robert Caro spent years chasing facts with monastic discipline. Dame Stephanie Shirley worked twelve-hour, seven-day weeks. Chung Ju-yung measured life in effort, not years. Barry Diller believed that to stop evolving was to stop living.

Harrison McCain captured the idea with unusual clarity. He believed the first requirement for success was single-mindedness of purpose — the willingness to sacrifice, make difficult choices and persist long after others fall away. Those who endure, he argued, inevitably outperform those who do not. Billy Walters immersed himself for five decades in the craft of finding an edge. Alan McKim devoted four decades of sixty-hour weeks to building Clean Harbors. Ed Stack spent fifty years at Dick’s Sporting Goods, thirty-six as CEO, after starting in the store at thirteen. Properly directed, fanaticism isn’t imbalance — it’s commitment to excellence. It compounds.

Reading 2025 - Books 30-80.

The Weight of Resilience

The deeper I read, the clearer it became that greatness is rarely born from comfort. Daniel Aaron arrived in the US as a thirteen-year-old refugee to escape the Nazis; his parents later took their own lives, and he went on to help build Comcast. Dame Stephanie Shirley was sent alone to England at age five to escape the Nazis and later built a pioneering technology company when women weren’t allowed in boardrooms.

Ted Turner lost his father to suicide at twenty-four and channelled that trauma into building CNN. Barry Diller later reflected that the dysfunction of his early life forged his own tools for success — an “alchemy,” as he described it, turning weaknesses into strengths. Sheila Johnson endured neglect and abuse before co-founding BET and creating opportunity for others. Resilience, it turns out, isn’t toughness; it’s the capacity to absorb adversity, adapt, and continue building despite it.

Business Pivots

Another recurring theme was the role of well-timed pivots in building durable businesses. John Malone shifted from regional signal retransmission to dense urban cable systems, materially improving network economics. Michael Ovitz redefined the Hollywood agent by moving from individual representation to packaging complete films for studios. Intel exited memory chips to focus on CPUs, while NVIDIA evolved from gaming graphics processors into a platform and chip supplier for AI. Birkenstock transitioned from a niche orthopaedic footwear brand into a global lifestyle and fashion business, and Herman Miller moved from designer furniture to integrated office furniture systems.

The Art Spirit

Design emerged as another quiet constant. Charles and Ray Eames refused to talk about “good design.” They asked simpler questions: does it solve a problem, is it serviceable, and will it still matter in ten years? That same mindset defines great investors and great businesses — durability over decoration, substance over style.

Robert Henri’s The Art Spirit may be the best business book never labelled as one. It’s about care, conviction and treating work as if it truly matters. From Rolex to DHL to Herman Miller, the most enduring enterprises see their craft not as a job, but as a calling.

In the End

By the end of the year, the message was unmistakable. Compounding isn’t just financial — it’s cultural, creative and moral. Whether in a studio, on a football field or inside a company, progress is a long obedience in the same direction.

Each book added another beam to the latticework of mental models beneath better judgment. Some books add knowledge. The best expand judgment.

Compounding works on ideas as much as capital — if you stay curious long enough to connect them. Here’s to another year of curiosity, discipline and quietly expanding the toolkit.

Thank you for taking the time to follow the blog posts this year.

Happy holidays, and best wishes for a fruitful New Year.

Follow us on Twitter : @mastersinvest
* Visit the
Blog Archive *

TERMS OF USE: DISCLAIMER
A Century-Old Classic Buffett Would Love

Every so often you stumble across a book so old, so unassuming, that it shouldn’t have any relevance to modern investing… and yet it reads as if it were written yesterday.

That was my experience with R.W. McNeel’s 1927 gem, Beating the Market. Nearly a century old, it feels startlingly contemporary.

You might reasonably ask: How could a hundred-year-old investing book offer anything useful today? Markets have evolved, technology has transformed how we trade, and the world looks nothing like it did in 1927.

The answer lies in one of the greatest truths ever spoken about markets - Jesse Livermore’s immortal line:

“Wall Street never changes. The pockets change, the suckers change, the stocks change, but Wall Street never changes, because human nature never changes.”

McNeel understood that. His observations about behaviour, temperament, and value are as fresh—and as useful—as anything written today.

And here’s where it gets even more interesting.

Although it was published three years before Warren Buffett was born, the lessons in this little volume closely mirror his own philosophy: buy below intrinsic value, bet on America, stay unemotional, seek value, avoid new issues, ignore brokers, be patient, resist the crowd, and focus on businesses with quality management — to name just a few.

You’ll find the similarities striking.

Below, I’ve placed McNeel’s words side-by-side with Buffett’s — not to suggest influence, but to illustrate how enduring principles survive generations.

Bet on America

“One of the first principles of speculative success, the fundamental necessity, if one would be in the frame of mind to buy stocks when they are low - namely, faith in the United States of America, faith in her government, her institutions, and her people.” R.W.McNeel

“Before one starts in to speculate, therefore, he should paste this old creed in his hat: ‘I believe in my country - The United States of America. I believe in the American people, their genius, their brains, and their brawn. I believe in their honesty, and their integrity and dependability. I believe that nothing can stand in the way of their commercial advancement and prosperity.’” R.W. McNeel

‘Bet on America’

“American business, really, has never let investors down as a group, but investors have done themselves in quite frequently.” Warren Buffett

“Charlie and I have always considered a ‘bet’ on ever-rising U.S prosperity to be very close to a sure thing. Indeed, who has ever benefitted during the past 237 years by betting against America? If you compare our country’s present condition to that existing in 1776, you have to rub your eyes in wonder. And the dynamism embedded in our market economy will continue to work it’s magic. America’s best days lie ahead.” Warren Buffett

“America has been a terrific country for investors. All they have needed to do is sit quietly, listening to no one.” Warren Buffett

“In general, the batting average of doomsayers in the U.S. is terrible. Our country has consistently made fools of those who were skeptical about either our economic potential or our resiliency. Many pessimistic seers simply underestimated the dynamism that has allowed us to overcome problems that once seemed ominous. We still have a truly remarkable country and economy.” Warren Buffett

The Power of Retained Earnings

“The real value of securities representing well-managed American industries is increasing all the time. Earnings are constantly being put back into the properties to build them up, and the asset value is steadily being augmented. Stocks usually go well above their real value in bull markets, and they go below their real value in bear markets. But with the real value steadily rising, the tendency is for the extreme low price of any stock in one bear market to be higher than the low level in the bear market preceding.” R.W. McNeel

“[The stock market’s underlying] value gains from year to year. Companies retain earnings. If you own a business and you plow back a good portion of your earnings into building the business you are going to have something more valuable, on average, year after year. Sometimes the market reflects it and sometimes it is crashing for some other reason, but the stock market builds in underlying value from year to year.” Warren Buffett

Emotions and Temperament

“Speculative success depends as much on the character of the speculator as on knowledge of how to win.” R.W. McNeel

“The majority of people who enter the stock-market arena to make money are beaten before they start, because they have a wrong mental attitude towards the speculative game.” R.W. McNeel

“If one is emotional, if he lacks the power of independent thought and the power of will to act on his own knowledge, he should keep out of the stock market. If one is so temperamental that he is carried away by the enthusiasm or depression of the moment, failing to act when he should and acting when he should not, he should keep his money in the savings bank. Otherwise, some one will get it away from him.” R.W. McNeel

“It is a problem of self-mastery and self- discipline as much as one in finance.“ R.W. McNeel

“Rationality is essential when others are making decisions based on short-term greed or fear. That is when the money is made.” Warren Buffett

"It’s an easy game, if you can control your emotions." Warren Buffett

"Beyond a certain basic level, though, of skill .. your emotional make-up’s more important than some super high degree of skill." Warren Buffett

“The proper temperament is far more important in investing than points of intellect. If you’ve got a reasonable intellect and the right temperament you’d get very rich, and if you’ve got the wrong temperament for it, you’ll get done in at some point.” Warren Buffett

Human Nature

“If one will but analyze the fundamental causes of speculative failure, he will discover that the chief blame lies not in the character of the stock market, not in the fact that the ‘game’ is loaded against the average speculator, but in weaknesses inherent in human nature. It is not the stock market which beats speculators. It is their own unreasoning instincts and inborn tendencies which they cannot master, and which given free rein lead on to ruin.” R.W. McNeel

“A great Frenchman once said, ‘There is but one person in a, hundred, nay in a thousand, who thinks.’ If that be true, and it sometimes seems as though it were, it is not surprising that few can curb their instinctive actions in the market and act in accordance with reason.” R.W. McNeel

“Human nature has not changed. People will always behave in a manic-depressive way over time. They will offer great values to you.” Warren Buffett

“Humans will continue to make the same mistakes that they have made in the past.” Warren Buffett

“The better you understand human nature and are able to distinguish between different types of individuals, the better the investor you are going to be.” Warren Buffett

Discount To Intrinsic Value

“Men who make a success of speculation, lay in their lines of stocks when prices are low and the risks are small…. They know from investigation before they buy that at the prices they pay for stocks they are buying into the properties which the stock certificates represent at fifty cents on the dollar of the value of the assets of those corporations.” R.W. McNeel

“On the one side are those who know that stocks ought to be bought when they are low and below the line of real values, and have the courage to buy them at such times. They know, too, that stocks ought to be sold, however attractive they may appear, when they are high and above the line of real values, and have the courage to sell them. On the other side are those who play the game but who do not know, or have not the courage to follow, the principles which lead to speculative success - the sucker public.” R.W. McNeel

“The mere desire to make money should never be the mainspring of speculative action. Knowledge or belief based on intelligent analysis that a speculative opportunity presents itself is the only safe basis for making purchases of stocks. It is in forgetting that principle that so many speculators err. They do not ask when they are preparing to buy stocks, ‘Is the stock cheap, and is it selling below its real value?’ but ‘Is that stock going up?’ The only sound reason for buying any stock is that it can be had cheap. Granted that, and also that it represents ownership in one of our great essential American industries, a speculative profit is practically assured, if one have patience.” R.W. McNeel

“The only reason to lay out money is because you expect to get something in return that is worth at least as much, and hopefully more, than you pay." Warren Buffett

“My game is simply to buy something worth a dollar for 50 cents.” Warren Buffett

“If you buy businesses for less than they’re worth, you’re going to make money.” Warren Buffett

Company Earnings & Value

“Hold firm the principles underlying all successful speculation, that earning power makes values, and values make prices in the long run, and, having in mind the value based on earning power of any particular stock.“ R.W. McNeel

“Put together a portfolio of companies whose aggregate earnings march upward over the years, and so also will the portfolio’s market value.“ Warren Buffett

“Over time, of course, market price and intrinsic value will arrive at about the same destination.  But in the short run the two often diverge in a major way.” Warren Buffett

Good Management

“Good management is at the foundation of all corporate success. If there is one thing on which the investor or speculator should insist above all others, it is on knowing the character of the men behind the enterprise.” R.W. McNeel

“The veteran banker of Boston, the late Henry L. Higginson, asked one day by an investor what stocks he ought to buy with some idle funds replied, ‘Buy character.’ He meant that if one bought into any industry backed by men of experience and of high character and intelligence, one would at least be subject only to the usual risks of business, and chances of success would be excellent. On the other hand, no one could have faith in securities of any corporation operated by men of doubtful character.“ R.W. McNeel

“In management you look for ability, trust & character.” Warren Buffett

“We depend on management.” Warren Buffett

“We do not wish to join with managers who lack admirable qualities, no matter how attractive the prospects of their business. We've never succeeded in making a good deal with a bad person.” Warren Buffett

Independent Thinking

“One of the frequent causes of failure in speculation is the inability of the average speculator to think independently, when people around him are telling him in most definite terms what they are thinking.” R.W. McNeel

“The best way to think about investments is to be in a room with no one else and just think. And if that doesn‘t work, nothing else is going to work.” Warren Buffett

"Independent thinking, emotional stability, and a keen understanding of both human and institutional behaviour are vital to long-term investment success." Warren Buffett

Fear

“One chief reason many fail to buy stocks when they are low is because of fear. Periodically prices of stocks representing ownership in the great productive industries of the United States and her great railroad systems fall so far that ownership in them is selling for 25 to 50 cents on the dollar of the value of the bricks and mortar and working capital which the stocks represent. But the majority of people will not buy them then because they are afraid. If they would analyze the cause of their fear they would discover it to be due to doubt as to the very stability of American institutions, for nothing less fearsome would justify certificates of ownership in the great industries of the nation selling at such ridiculous prices.” R.W. McNeel

“Fear is the oldest human instinct, from the standpoint of biology. It is universal and the most deep-rooted of all. It is the outgrowth of the instinct of self-preservation, through whose effective workings life has been able to survive through the ages. Every man has this instinct developed to an uncomfortable extent. Because of its ancient origin and its great strength, man is at all times exposed to the absolute breaking down of his courage under certain conditions and frequently without cause.” R.W. McNeel

“Fear is the foe of the faddist, but the friend of the fundamentalist.” Warren Buffett

“Be fearful when others are greedy and be greedy when others are fearful.” Warren Buffett

“During such scary periods, you should never forget two things: First, widespread fear is your friend as an investor, because it serves up bargain purchases. Second, personal fear is your enemy.” Warren Buffett

“If you have a temperament that when others are fearful you’re going to get scared yourself, you know, you are not going to make a lot of money in securities over time, in all probability.” Warren Buffett

Patience

“Patience - an indispensable quality. If one were asked to name the quality which as much as any other is essential to success in speculation, the answer would be ‘patience.’” R.W. McNeel

“The biggest thing about making money is time. You don’t have to be particularly smart you just have to be patient.” Warren Buffett

“The stock market is designed to transfer money from the active to the patient.” Warren Buffett

Take a Loss

“One great weakness of the average speculator is his inability to swallow small losses. He can never forget what he paid for a stock. He sees it go below his selling price, and, regardless of the position of the general market in the cycle, declines to sell, always hoping for a rally which will let him out whole.” R.W. McNeel

“I’m quite capable of selling a stock when it goes down. I am quite capable of buying a stock when it goes down. It all depends on the underlying facts.” Warren Buffett

“Should you find yourself in a chronically leaking boat, energy devoted to changing vessels is likely to be more productive than energy devoted to patching leaks.” Warren Buffett

“The stock doesn't know you own it. The stock just sits there; it doesn't care what you paid or the fact that you own it.” Warren Buffett

Buy at Market

“The point is just this - if a stock is cheap at 30, it is cheap at 32. So there is no common sense in running the chance of missing what one believes to be an opportunity to make 100 per cent on a speculative venture, by sparring for an extra point or two on the buying side. Buy ‘at the market.’” R.W McNeel

“There’s a lot of mistakes that I’ve repeated, I can tell you that. The biggest one, probably — or the biggest category over time — is being reluctant to pay up a little for a business I knew was really outstanding, or to continue to buy it at higher prices when I knew it was outstanding. So the cost of that has been many, many billions. And I’ll probably keep making that mistake.” Warren Buffett

Stock Prices

“There is no such thing as ‘can't’ in respect to the stock market. Any stock can do anything.” R.W. McNeel

“In stock markets, it’s an auction market. Crazy things can happen.” Warren Buffett

“It’s crucial to understand that stocks often trade at truly foolish prices, both high and low. ‘Efficient’ markets exist only in textbooks. In truth, marketable stocks and bonds are baffling, their behavior usually understandable only in retrospect.” Warren Buffett

Opinions

“It is a curious fact of finance that any one on the ‘street’ is always willing to express an opinion on the market, and on any particular stock, however little he may know of either.” R.W. McNeel

“We’re not looking for opinions. We’re looking for facts.” Warren Buffett

“You really shouldn’t ask other people their opinion about stocks. Let’s say I give an opinion on the XYZ company. I could change my opinion a week from now and [you won’t know]. You ought to have your own reasons for buying a stock. If you don’t your going to get shaken out by some event, the stock markets goes down a lot or you read some negative comments. You should make you own judgements in stocks.” Warren Buffett

Get Rich Quickly / Hard Work

“Where the public in general does err is in thinking the market is a ‘get rich quick scheme.’ It is not a game which pays something for nothing, or much for little. It is a game which repays liberally careful study of the underlying conditions which cause stock-market fluctuations. But the reward is apt to be more or less commensurate with the effort put forth to master it. It is a game to be beaten, not by disregarding the fundamental law of existence, but by remembering the old law that in order to reap the rewards of this world one must give something of himself, of his time and efforts and abilities, in order to acquire them.” R.W. McNeel

“People would rather be promised a (presumably) winning lottery ticket next week than an opportunity to get rich slowly.” Warren Buffett

“Read 500 pages every week ... That's how knowledge works. It builds up, like compound interest. All of you can do it, but I guarantee not many of you will do it.” Warren Buffett

“Intensity is the price of excellence.” Warren Buffett

The Crowd

“There is comfort in a crowd, in doing what others are doing, even when the support or refuge is purely illusory. It is calculated by war authorities that in an average company of men, 20 per cent possess a certain amount of initiative, 60 per cent will follow the crowd, and 20 per cent are cowards at heart. In speculation it is doubtful if 20 per cent possess the powers of independent thought and action.” R.W. McNeel

“When any one buys a stock merely because he thinks or some one tells him it is going up, regardless of its real value, he is following a speculative plan which is absolutely certain to lead on to ruin. He may make a profit once, twice, or half a dozen times by that method, but sometime he is absolutely certain to be badly hurt.” R.W. McNeel

“Men tend to flock together. Allied to this is the instinct of sympathy and imitation. Men have an inborn tendency to do what they see some one else doing; to run or stop or cheer when others act in that fashion. It is the same instinct which causes sheep to run or stop, or dogs to bark when other sheep run or stop or when other dogs bark, without having any special reason for doing so. By unconscious imitation or sympathy, men catch the feeling of others and act in accordance with it.“ R.W. McNeel

"An ability to detach yourself from the crowd — I don’t know to what extent that’s innate or to what extent that’s learned — but that’s a quality you need." Warren Buffett

“Once a bull market gets under way, and once you reach the point where everybody has made money no matter what system he or she followed, a crowd is attracted into the game that is responding not to interest rates and profits but simply to the fact that it seems a mistake to be out of stocks. In effect, these people superimpose an I-can't-miss-the-party factor on top of the fundamental factors that drive the market. Like Pavlov's dog, these ‘investors’ learn that when the bell rings - in this case, the one that opens the New York Stock Exchange at 9:30 a.m. - they get fed. Through this daily reinforcement, they become convinced that there is a God and that he wants them to get rich.” Warren Buffett

Sleep at Night Test

“‘What shall I do?’ said a trader to a great successful operator. ‘I am loaded with stocks, and the market keeps going down. I can't sleep nights.’ And the operator replied, ‘You sell your stocks down to the sleeping-point.’” R.W. McNeel

“The financial calculus that Charlie and I employ would never permit our trading a good night’s sleep for a shot at a few extra percentage points of return.” Warren Buffett

Checking Stock Quotes

“If one would be successful in speculation, he should keep away from the stock-ticker. It is a fascinating little machine, and any one holding stocks and constantly watching the ticker will have plenty of thrills. But the practice is a deadly one.” R.W. McNeel

‘Checking Stock Quotes’

“The average trader who hangs around the ticker eventually comes to look no farther ahead than the day-to-day fluctuations. His ideas are shaped wholly by the hourly movement of prices, and not by study of fundamental conditions of business on which his market operations should be based.” R.W. McNeel

"You know, I think people’s investment would be more intelligent, you know, if stocks were quoted about once a year." Warren Buffett

“Focusing on the price of a stock is dynamite, because it really means that you think that the stock market knows more than you do. Now if the stock market may know more than you do, but then you shouldn’t be in stocks. The stock market is there to serve you and not to instruct you.” Warren Buffett

“In investing, just as in baseball, to put runs on the scoreboard one must watch the playing field, not the scoreboard.” Warren Buffett

Maintain Focus

“All financial history shows that the old adage ‘Cobbler, stick to your last’ holds good of high and low alike. When one finds an able man sticking to his last, he is usually a safe man to follow. But where he is wandering far afield and engaging in industries in which he has had no training and no past successes, his name should not be considered any guarantee of safety of an investment or speculation in the stock of the concern in which he is interested.” R.W. McNeel

“Loss of focus is what worries Charlie and me when we contemplate investing in businesses that in general look outstanding.” Warren Buffett

“At dinner, Bill Gates Sr. posed the question to the table: ‘What factor did people feel was the most important in getting to where they’d gotten in life?  And I said, ‘Focus,’ and Bill [Gates] said the same thing.” Warren Buffett

Charts

“In speculation, no mechanical device will ever take the place of judgment - not even the chart.” R.W. McNeel

“The chart of the price action doesn’t mean a thing to us, although it may catch our eye, just in terms of businesses that have done very well over time. But price action has nothing to do with any decision we make. Price itself is all-important, but whether a stock has gone up or down, or what the volume is, or any of that sort of thing, that is — as far as we’re concerned, you know, those are chicken tracks, and we pay no attention to them.” Warren Buffett

New Issues

“New flotations - Let someone else have them. In every period of rising stock prices, many new corporate flotations are brought to the attention of speculators by banking houses and so-called banking houses. Under the spell of the enthusiasm engendered by rising corporate profits and rising stock-market prices, these issues are floated, and innumerable speculators buy them hoping for quick profits.

Banking houses are manufacturers of securities. They manufacture not necessarily what people ought to have, but what they will buy. That is sound finance, too, where the manufacture of a security is for the purpose of raising money for the legitimate expansion of sound industries. But the majority of stock flotations in boom times in the stock market are largely for the purpose merely of realizing a promoter’s profit for the sponsors of the new issue.” R.W. McNeel

“When there is a boom in automobile securities on the Stock Exchange, one may expect several new motor stock flotations, not because there is a public need for a new motor concern, but because the public mind has been inflamed by stories of great profits made by those who bought the motor stocks months previously, and the public is in a frame of mind to buy a new motor stock. It is the state of the public mind and the desire for a rake-off on a new issue, rather than the necessity for a new motor concern, which dictate the stock flotations.” R.W. McNeel

“The public usually ‘falls’ for these new flotations. It is argued by false analogy that because an established motor stock is good and the price is advancing, the new stock must be good. In addition, they swallow the customary selling argument that purchase of the stock at the very inception of that concern gives them an opportunity to get in ‘on the ground floor.’

Prospective buyers of the stock are practically always shown figures representing the tremendous profits made by the original subscribers to stocks of the big successful concerns in the industry, the theory being that they will be duplicated by purchasers of the stock of the concern being floated.

In reality, the public ought to argue that the stock of the new flotations is probably much dearer than stocks of the successful concerns already listed on the Stock Exchange, for the price of the new stock includes a big promoter’s profit. Moreover, the older companies are established in their fields and their business is assured as far as any business can be, whereas the future of the new concern instead of being assured is a pure gamble.

That line of reasoning applies to nearly all new flotations of stock. In copper booms, new copper stocks are printed. In zinc booms, new zinc mines are discovered or old ones are polished up. In steel booms, privately owned steel concerns are bought from their owners, recapitalized, and their stocks sold to an enthusiastic public.

Sometimes speculative profits on these things materialize, but it is a good rule to let the new propositions alone. Standard listed stocks which have stood the battledore and shuttlecock of the marketplace for years can usually be had intrinsically cheaper than the new things being floated, and they usually enjoy a more stable market in times of unsettlement. In addition, it is unsound speculation to buy stocks in a boom period in any case, and the new flotations usually make their appearance only in the latter stages of a great bull market.” R.W. McNeel

“I will guarantee you that if you have thousands of opportunities among stocks all over the world and most of them are not being promoted or being sold with special commissions in them or something else, and then some other security is coming to market that day, when the seller picks the time to bring it, as opposed to just this auction market operating otherwise, you know, it just doesn’t make any sense to spend five seconds thinking about new issues, so we don’t think about them.” Warren Buffett

“An intelligent investor in common stocks will do better in the secondary market than he will doing buying new issues. The reason has to do with the way prices are set in each instance.” Warren Buffett

“It’s almost a mathematical impossibility to imagine that, out of the thousands of things for sale on a given day, the most attractively priced is the one being sold by a knowledgeable seller (company insiders) to a less-knowledgeable buyer (investors).” Warren Buffett

“I don’t think buying new offerings during hot periods in the market is anything the average person should think about at all.” Warren Buffett

Brokers

“When it comes to taking a broker’s advice in stock market operations, it is a different proposition. They should probably all be shunned, or at least their advice should be considered very carefully before one acts on it.

There are various reasons for that statement. The majority of brokers are not deep thinkers nor deep students of financial affairs. The very nature of their business makes them shallow. Moreover, while the interests of the broker are supposed to be the same as those of his client, because, theoretically, the more money the client makes the more commissions the broker will receive, in reality their interests are quite different.

It is in the interests of the client to trade very infrequently. The only safe rule of speculative success is to buy when prices are low and wait patiently until they are high. That does not involve many brokerage commissions. The broker, however, can only thrive through having his customers trading in and out of the market every day or every few days. That involves trying to catch the small fluctuations in prices, and not the long swings.

No one knows or can guess consistently what the market will do from day to day, for the small swings are not brought about by any fluctuations in fundamental conditions. They are largely the result of psychological phenomena. They merely reflect the vagaries of the speculative mind. The broker’s guess as to what these may be is no better than that of the street-sweeper, and perhaps not so good, for the street-sweeper would have no preconceived ideas of the fluctuations, while the broker would probably feel it his duty to be bullish most of the time. The majority claim to be optimistic most of the time, though it is obviously impossible to be right on the bull side much more than half the time.

But the average broker figures that for his own best interests he must be bullish for several reasons. First, no one likes a pessimist, while every one likes an optimist for the good cheer he engenders even if he is wrong. A pessimist would drive customers away.

Second, the public seldom sells short, so nearly all the business a broker gets must originate on the buying side. The selling side afterwards will take care of itself. That is, if a man goes into a brokerage house with an idea of doing something in the market and the broker is pessimistic, the chances are the customer will go out without doing anything. He may give his orders to some other broker.” R.W. McNeel

“One fact of financial life should never be forgotten. Wall Street – to use the term in its figurative sense – would like its customers to make money, but what truly causes its denizens’ juices to flow is feverish activity. At such times, whatever foolishness can be marketed will be vigorously marketed – not by everyone but always by someone.” Warren Buffett

“Anytime I see some article that says, you know, these analysts say this or that about some business, it just — it doesn’t mean anything to us. You cannot get rich with a weather vane.” Warren Buffett

"I never talk to brokers or analysts... You have to think for yourself... Wall Street is the only place people ride to in a Rolls-Royce to get advice from people who take the subway." Warren Buffett

Broker Sales

“A popular ex-football player, a golf champion or tennis star is a much more desirable customers’ man or perhaps a more desirable partner in a brokerage house, in the eyes of the broker, than a little known financial genius. He can generally pick up the lingo of the ‘street’ quickly, and conceal his financial ignorance by indulging only in glittering generalities, while his presence there attracts his friends and admirers.” R.W. McNeel

"There’s been far, far, far more money made by people in Wall Street through salesmanship abilities than through investment abilities." Warren Buffett

Broker Incentives

“The salary the customers’ man (the broker) receives and his bonus at the end of the year depend not on the amount of money his clients make, but on the number of times he gets them in and out of the market—that is, on the amount of commissions he brings in.” R.W. McNeel

“[The broker’s] getting paid based on how many pills he sells. He gets paid more for some pills than others. You wouldn’t go to a doctor whose pay was totally contingent on how many pills you took.” Warren Buffett

Broker Reports

“Brokers’ letters, issued daily or weekly, are intended to fill the same purpose, namely, of getting speculators to trade frequently. They are usually bullish. When they are not so they are generally non-committal. The letters are calculated to inspire confidence whether justified or not, and create action among clients. It is just another method of pursuing the elusive commission of $15 on each hundred shares of stock traded in.” R.W. McNeel

“We never look at any analyst reports. If I read one it was because the funny papers weren’t available. I don’t understand why people do it.” Warren Buffett

"You can’t read Wall Street reports and get anything out of them. You have to do it yourself and get your arms around it. I don’t think we’ve ever gotten an idea, you know, in 40 years from a Wall Street report. But we’ve gotten a lot of ideas from annual reports." Warren Buffett

Summary

While Buffett ultimately built a far broader and more sophisticated investing framework than McNeel could ever have imagined, the foundations McNeel laid in 1927 remain remarkably solid. Strip away the technology, the speed, the data, and the noise, and you find the same timeless principles: discipline, patience, rationality, independent thought, and a focus on value anchored in real businesses run by real people.

That is why this nearly century-old book still feels so alive. Markets evolve, but human nature does not. The behaviours that drove booms and busts in McNeel’s era are the same forces we wrestle with today — fear, greed, impatience, imitation, overconfidence, and the lure of the crowd.

Or, as Buffett put it most succinctly:

“Humans behave the way humans behave, and they’re going to continue to behave that way in the next 50 years.”

McNeel understood that in 1927. And for the thoughtful investor, the lesson is clear: if you master yourself, you can master the market — regardless of the century you’re living in.

Source:
McNeel, William W. Beating the Stock Market: A Book of Practical Investment Advice. New York: The Magazine of Wall Street, 1927.

Follow us on Twitter : @mastersinvest
* Visit the
Blog Archive *

TERMS OF USE: DISCLAIMER
In Search of Excellence

If you’ve ever wondered why some companies seem to compound advantage for decades while peers stall, In Search of Excellence - Lessons from America’s Best-Run Companies is still one of the cleanest lenses you can pick up. Tom Peters and Robert Waterman didn’t write a finance book; they wrote a field guide to the systems, habits, and culture that produce outsize performance. Warren Buffett once called it “a landmark book,” and generations of builders—from Domino’s Tom Monaghan to DHL’s Po Chung, Tractor Supply’s Joe Scarlett, Hästens’ Jan Ryde, Grocery store maverick Stew Leonard, Germany’s Reinhold Würth, and Canada’s Jimmy Pattison—credit it with reshaping how they lead.

And it’s worth remembering: Peters and Waterman didn’t invent excellence — they named it. Fully sixty years before the publication of In Search of Excellence, Konosuke Matsushita was already discovering and practising many of the same principles at Panasonic that would later be codified in 1982.

The reason: it shows that excellence is an emergent property—a tornado that forms only when lots of small, mundane air currents swirl in the same direction.

Peter Kaufman’s tornado metaphor and Safi Bahcall’s definition of “emergent properties” capture the heart of the book. Cultures aren’t engineered through a single lever; they emerge when dozens of small choices—tone at the top, customer closeness, decentralization, storytelling, tolerance for small failures—interlock. Charlie Munger calls this the Lollapalooza effect: really big outcomes usually come from the confluence of many smaller forces all acting in the same direction. That’s why the best business moats rarely show up in a single ratio; they hide in how a company behaves.

Peters and Waterman’s eight principles remain startlingly fresh: Bias for Action, Close to the Customer, Autonomy & Entrepreneurship, Productivity Through People, Hands-On Management, Stick to the Knitting, Simple Form/Lean Staff, and Simultaneous Loose-Tight Properties. Put less academically: do lots of small experiments, learn directly from users, push authority to the edge, treat people like adults, be explicit about values, stay within competence, keep HQ tiny, and be rigid on principles but flexible on tactics. Read those alongside Phil Fisher’s 1958 counsel—to watch how management treats rank-and-file, delegates authority, and seeks ideas from below—and you see the same pattern: people and process drive the numbers.

A few themes investors should underline:

  • Customer obsession is the non-negotiable. The excellent firms over-invest in reliability, service, and user intimacy—even when spreadsheets say not to. Caterpillar’s 48-hour parts pledge, Maytag’s “ten years trouble-free,” and Frito-Lay’s “unreasonable” service levels look uneconomic quarter-to-quarter—and indispensable decade-to-decade. Pricing power often follows because the product is a tiny cost, massive consequence input (Raychem, Schlumberger).

  • Small bets → fast learning → big wins. The book exalts doing over debating: prototypes with customers, skunkworks, “lots of tries,” tolerance for small failures, and internal competition that surfaces better approaches. It’s the same loop Amazon later codified and IKEA’s Kamprad preached: never two identical stores; keep moving. Würth built much the same cadence—empowering local branches, testing constantly, and competing internally in a spirit of relentless, practical improvement.

  • Empowerment beats bureaucracy. Excellence lives where decisions sit with the people closest to the action. The best companies push autonomy far down, celebrate non-monetary recognition, run lean headquarters, and practice “management by wandering around.” People given control become owners—emotionally first, financially later. That’s Fisher again: if management can’t accept criticism from below, you won’t get the ideas that compound.

  • Culture is a barrier to entry. The real moat is the 75-year investment in service habits at IBM or the quality reflex at P&G. Stories, slogans, myths, and rituals transmit those values more effectively than manuals. As Peters writes, the top performers are “hands-on, value-driven”; profit is a by-product of doing the important things unusually well and consistently. Jimmy Pattison embodied this philosophy—walking the floor daily, knowing employees by name, and treating customers as partners. His vast, decentralized group runs on the same human principles championed in In Search of Excellence.

  • Stick to the knitting, act small as you get big. The stars keep adjacent moves close to core capability, contain risk with small steps, and—crucially—split before scale becomes sclerosis. Big and fast, yet organized as many small teams with clear scoreboards and friendly rivalry: that’s how you stay inventive without losing coherence.

For operators, the book is a permission slip to simplify and humanize: clarify a few priorities, walk the floor, praise publicly, test constantly, and tell stories that make values vivid. For investors, it’s a reminder to look past the spreadsheet. The signals of a long-term compounder are mostly qualitative: frontline empowerment, customer intimacy, lean HQ, experimentation cadence, leaders who model the culture, and a company that is rigid about principles, loose about methods. As Mark Urquhart notes, margins and returns are the cogwheels of valuation—but the torque comes from the DNA: culture, time horizon, willingness to experiment, and a sense of contribution.

If you manage people, In Search of Excellence will give you a playbook. If you allocate capital, it will give you pattern recognition—the fingerprints of firms that are “brilliant on the basics,” where success is “a collection of lots of little things.” First published in 1982, its lessons remain as relevant today as ever—timeless principles that have powered many of the best-performing companies for 40+ years. That’s why so many enduring companies—and the investors who back them—still keep this book within arm’s reach.

Source:
Tom Peters & Robert H. Waterman Jr., In Search of Excellence: Lessons from America’s Best-Run Companies (Harper & Row, 1982).

Follow us on Twitter : @mastersinvest
* Visit the
Blog Archive *


TERMS OF USE: DISCLAIMER
Learning from Dame Stephanie Shirley

At just five years old, Dame Stephanie Shirley’s parents placed her and her eight-year-old sister on a Kindertransport train from Vienna to England in 1939. The Refugee Children’s Movement gave the two girls a foster home and a chance to escape the Nazis, but their family was left shattered. Her father chose not to rejoin them, and her mother, though she came to England after the war, left Stephanie in the care of foster parents for six years. That experience left her with survivor’s guilt, abandonment wounds, and a profound awareness that tomorrow may look nothing like today. Out of this crucible came a resilience and determination that would define the rest of her life.

Years later, Shirley’s resilience was tested again as she raised her only child, a son with severe autism whose care demands were constant and unrelenting. And when the glass ceiling blocked her advancement in a well-paid job, she walked away. With just £6 of capital, a dining room table, and a shared telephone line, she launched a company that would reshape Britain’s nascent computer software industry. In an era when nobody sold software and most companies wouldn’t employ married women, she built an entirely new kind of enterprise.

To get her business taken seriously, Shirley signed her letters, “Steve.” To win talent, she tapped into a forgotten pool of highly trained female mathematicians who had been forced out of conventional firms by rigid, male-dominated structures. She created an organisation built on trust, flexibility, and empowerment — decades ahead of its time. Her company, Freelance Programmers, thrived and eventually listed on the London Stock Exchange, reaching a market capitalisation of more than £2.5 billion. Along the way, she introduced staff ownership, profit-sharing, and even committed 1% of pre-tax profits to charity — creating seventy millionaires and seeding a culture where “doing the right thing” was embedded in the corporate DNA.

What makes Shirley’s story so compelling for investors is not just her perseverance, but the clarity of her philosophy. Profit was never the goal — it was a by-product. “Making money scarcely featured in my list of motives. What I wanted was not wealth but a workplace where I was not hemmed in by prejudice or by other people's preconceived notions of what I could and could not do,” she wrote. Her focus was always on purpose, empowerment, and quality. She worked twelve-hour days, seven days a week, through holidays, compounding effort when competitors would not. She trusted her people, listened to customers, learned from mistakes, and never accepted defeat.

After handing over the reins of her company, Shirley devoted the rest of her life to giving back. She directed her entire fortune to philanthropy, with a special focus on autism research inspired by her son, and to causes that expanded opportunity for others.

As with so many of the business biographies we study, Shirley’s life distills principles that appear again and again in the stories of outstanding companies and leaders. Seek out tailwinds, empower your people, embed trust, innovate through trial and error, treat profit as fuel not an end, and above all, never give in. Her autobiography, Let It Go, is more than a remarkable human story; it is a blueprint for building resilient organisations that endure.

Below I’ve included some of my favourite quotes from this truly remarkable woman.

Character and Motivation

‘I was only five when my weeping mother put me on a train full of 1,000 children (to escape the Nazis) and 'let go', entrusting me to the kindness of strangers.’

‘Looking back today, from the other end of a life that has been exceptionally rich in nearly every sense, I can see that most of my subsequent achievements can be traced back to that unnatural separation. It marked the beginning of a narrative far more interesting than the one that had originally been scripted for me. But it also taught me, with the ending of my first life, a profound lesson: that few things in life are as solid as they seem; that tomorrow will not always resemble today; and that wholesale change, though often terrifying, is not necessarily synonymous with catastrophe.’

‘I felt rejected by my mother, who had not only sent me away on the Kindertransport but had also chosen to be reunited with Renate (my sister) in preference to me; I felt rejected by my father, who had not only sent me away but had subsequently abandoned me, along with the rest of his family, a second time; and I felt devalued by the chronic sense, going back to my very earliest memories, that I was displeasing to my mother. The fact that the Nazis had wanted to kill me hadn't done wonders for my self-esteem either. I had known all this for years, of course. What I had buried was the pain.’

‘I have, in short, been extraordinarily lucky. I have known failure and heartbreak as well as success, but I have never quite lost sight of two life-defining ideas - both of which I can trace back to my arrival in England all those years ago as a terrified, weeping child refugee. The first is the conviction that even in the blackest moments of despair there is hope, if one can find the courage to pursue it. Sometimes the worst is less overwhelmingly awful than we fear; sometimes the right attitude can create good even from life's most terrible situations.’

‘Even in my early teens, it was always important to me that I should do well in my education - not least because Renate continued to do well and because my mother was never slow to criticise me if she felt I was underachieving. I also knew that we remained fundamentally poor. We couldn't, for example, afford to buy the sweets that we were allowed under rationing, but instead could only give away our sweets points as presents.’

‘We had no desire to remain dependent on charity any longer than was absolutely necessary. And it was clear to me that, if I wanted to escape from the frustrations of poverty, doing well at school was a pretty indispensable start. But I also genuinely loved - and love - learning things. One of my greatest pleasures outside school was to go to Oswestry's wonderful library, where I could borrow any book under the sun without paying a penny. Light, serious, fiction, non-fiction, appropriate or wildly inappropriate - I read everything, voraciously, and learnt much as a result.’

‘My talent is for being an entrepreneur, in the widest sense. I love thinking of new ideas, questioning first principles, sensing new opportunities, starting things, changing things, recruiting new teams, attacking new challenges. That kind of work, for me, is indistinguishable from pleasure.’

‘I had to stop playing a part, to stop playing down those very qualities that made me who I was - my intellect and my curiosity and my restless drive to have an impact on the world.’

Obliquity

‘Becoming rich had never been one of my aims. All I wanted was the freedom to do what I was good at: that is, to explore the potential of information technology for transforming the way people worked. I had never dreamed of fast cars and huge houses. Rather, my ideal was to be part of some kind of high-powered creative commune, full of free, kindred spirits, held together not by rules and conventions but by our shared joy in what we did. It was the business itself, not its potential for generating profits, that I cared about.’

‘Making money scarcely featured in my list of motives. If all went well, I would earn a living; if the worst came to the worst, I had Derek's salary to fall back on while I found another job. What I wanted was not wealth but a workplace where I was not hemmed in by prejudice or by other people's preconceived notions of what I could and could not do - a place where, instead, I could exchange ideas freely with like-minded colleagues. And in 1962 that meant an entirely new kind of workplace.’

‘The fact that it was my company had had little effect on my personal wealth: I paid myself a modest salary, with any profits going back into the company. I had, in any case, little desire to be rich.’

Limited Resources

‘I had £6 of capital, a dining room table, a telephone (with a party line shared with a neighbour who, luckily, rarely used it), and one other mad idea: those who worked for me would all be women, employed on a freelance basis and working from home.’

“One of our accidental strengths was the fact that our lack of resources forced us to be relatively conservative in our use of software. We tried to keep abreast of new programming devel-opments, but we couldn't keep training people in every latest cutting-edge innovation. So our software tended to be tried and tested rather than experimental; and, as a result, we acquired an enviable reputation for reliability.”

“Our lack of financial muscle was, on the whole, an advantage. We had access to a small bank overdraft but there were next to no fixed assets. So we grew only when our market grew. I hired people only as I needed them, to work from home on specific projects.”

Obstacles

‘I had decided to start my own company, selling software. That's an uncontroversial sentence, written nearly 50 years later. At the time, it sounded mad. Drawbacks included the following. I had no capital to speak of. I had no experience of running a company. I had no employees, no office, no customers, and no reason to believe that there were any companies out there with any interest in buying my Product. Nobody sold software in those days. In so far as it existed, it was given away free.’

‘Given my experience with previous employers, it was not unreasonable to speculate that many potential customers, seeing the words ‘Stephanie Shirley' at the bottom of a letter, would refuse to take its proposals seriously, simply because I was a woman. (I) tested this theory by signing a few letters ‘Steve Shirley' instead. I did so, and people began to respond. I have been Steve ever since.’

Competitive Advantages

‘The main point never changed: this was a company that would offer opportunities to the kind of women whom traditional male-dominated companies considered unemployable.’

‘Talented female mathematicians had been passing through the universities in increasing numbers ever since the war, and gaining good degrees. Many of them had worked for a while in Britain's nascent IT industry, only to drop out - of the job and the job market - either on marrying or on having children. And, since most companies were far too rigid and male-dominated to adapt their ways of working to suit such employees convenience, their skills and intellectual energy had been going to waste. By committing my company to making use of this pool of untapped tatent, I gained privileged access to some of the best programmers in the country. (Many came from IBM, where part-time systems engineers were simply not allowed.) Not only were these women good; they were delighted to be working for me and determined to make the most of the opportunity. Perhaps as a result, the company thrived.’

‘It worked in our favour that there was scarcely any other part-time work available in those days that offered the slightest intellectual challenge - and most women, then as now, had at least a stage in their lives when part-time work was the only kind of work they could do. For intelligent, numerate women in mid-196os Britain, Freelance Programmers was a godsend.’

‘I suspect, however, that the most important factor that shaped Freelance Programmers in its early years was, simply, my naivety. Deep down, I still didn't know what I was doing. Not knowing what the rules were, I was free to innovate - as, indeed, was everyone else involved. Our long-term patterns of flexible home-working and remote management came about not just from theoretical idealism but also from practical necessity. They evolved because they were what worked. Paying for work done rather than hours worked made it easier to cost projects in advance; trusting people to manage their own time was not just effective but considerably easier than trying to keep control of every detail of every project remotely. It helped that there were so many high-powered programmers out there, who were available simply because more conventional companies disliked employing women with dependants. It also helped, Ithink, that they were women - who traditionally take responsibility for running family and home and, as a result, tend to develop finely honed self-management skills.’

‘Our competitors were still insisting that their staff worked for fixed hours, in fixed places, clocking in and clocking out and having to account for what they were doing throughout each shift. I trusted mine to manage their own time, as long as the work got done. The result? Not the anarchy and idleness that a traditionalist manager would have predicted but, instead, unrivalled productivity.’

Frugality

“I had always run the company on the basis of minimum cost - spending as little as possible on everything to reduce the danger of our outgoings outstripping our income.”

Promote Ownership / Share the Profits

‘Ultimately, the ideal of staff ownership would become as central to the company's ethos as the empowerment of women. Elsewhere in the industry - and indeed in British business generally - people were still clocking in and out, and having their pay docked if they took too long over their lunch break. We paid people for the work they accomplished rather than the hours they put in. Compared with a conventional company, we were treating our freelancers like adults: trusting them, as intelligent, motivated people, to make the best use of the time available to them in order to achieve the goals they had been set. In modern management-speak, they 'owned' the projects that had been assigned to them - which was a relatively small step from the idea that they should also participate in the ownership of the company. We introduced our first profit-sharing scheme in 1966.’

‘More than a third of the company's shares were owned directly by its workforce - more than 70 of whom would become millionaires within a decade. When you take into account all the others who amassed smaller - but still substantial - windfalls, that is an awful lot of lives dramatically changed by the simple mechanism of being handed a part of the company they worked for.’

‘If employees are treated with respect, and are given a stake in their employer's success, they will usually work better. And if the rewards of ownership are shared, then the responsibilities of ownership will tend to be shared as well.’

‘Employee-owned companies consistently outperform listed companies, according to the UK Employee Ownership Index, which measures the performance of companies that are more than 10 per cent owned by employees. Between 2003 and 2015, companies listed on the Index produced a return to investors that was, on average, 6.2 per cent better each year than companies in the FTSE All-Share Index.’

‘What I cannot demonstrate with figures are the non-material advantages of shared ownership. Yet these are considerable too. It is fairer. It spreads the strains of work as well as its rewards. And when it works well it creates a sense of community that makes the whole business of earning a living more enjoyable and rewarding.’

‘My gradual, painful handover of the company to its workforce and my successors led first to a culture of sustained motivation and ultimately to a great leap in profitability that, paradoxically, generated far more wealth for me after I had let go of it than it ever had before.’

‘My vision of a self-sustaining company was closely tied to my vision of a staff-owned company. Having achieved my initial goal of building a successful, sustainable business, I wanted to be sure that, whatever else happened to it in future, it retained its special character as a flexible, ethical, female-friendly organisation whose staff were listened to and trusted. Transferring ownership to the staff seemed the surest way of achieving this.’

Hard work / Fanaticism

‘Indeed, if I had to offer a single, simple explanation for my company's survival and ultimate success, it would be just this: my hard work. For reasons that I don't entirely understand, but which I imagine are rooted in my childhood, I never slackened off for a single day during that first decade of Freelance Programmers existence.’

‘All those days when I worked for twelve hours rather than eight, all those weeks when I worked seven days rather than five and a half, all those years when I worked through my holidays - if you add them all up over a decade the compounded advantage is considerable. There were, as I say, others who could have succeeded instead of us. If we came out on top, it was because we gave time and energy to the challenge that our rivals were simply not prepared to give.’

‘I have worked hard all my life, and I see little point in changing my habits now.’

‘Even now, when I can look back on the highs and lows of my life with slightly more equanimity, I see little attraction in just waiting limply for the clock of my life to run down. I would rather be doing my best to achieve something, trying to make a difference.’

Resilience

‘I resolved that, no matter how bad things got, I was not going to accept defeat. In my mind, my fight for business survival had become part of a much wider fight to defend everything that I held dear: my business dream, my family, my gender, my values. 'Never give in,' Winston Churchill had said, in a much-quoted speech in 1941 - never, never, never, never, in nothing great or small, large or petty; never give in except to convictions of honour and good sense... It had worked for him. It might just work for me.’

Optimism

‘Morale seemed to me to be a crucial issue. In business, as in life, good things rarely come to those who appear desperate. I was determined to put everything in a positive light.’

Mistakes

‘My view was, and is, that people should be allowed to make big mistakes - or one big mistake at least. Few of us are infallible, and the brightest people learn their most important lessons from the things they get wrong.’

Continuous Improvement

‘Resting on one's laurels is the surest route to stagnation. Instead, I would keep aiming higher and higher, giving free rein to my instinct to ask, restlessly, 'Is that all there is?' If I failed, so be it; but I would never allow myself to get into a position where I would curse myself for not having tried. I have not always succeeded in sticking to these resolutions. But, more than half a century later, I am tempted to say that they have defined my life.’

‘Every company needs the kind of firm, confident, hands-on management that ensures that it carries on performing its core functions well. Equally, no company can thrive for long without innovation, inspiration and strategic vision.’

Listen to the Customer / Learning Organisation

‘Our (client) contracts had insisted on a formal post-project review to get feedback from the client after our (software) system had been up-and-running for a while. (This was intended partly as a means of getting us back inside the door to tout for new work.) So the idea that there is always scope for learning to do things better was central to our culture, as was the idea of listening to the customer.’

‘Whereas employees in traditional companies tended to resent being monitored or criticised - and could barely comprehend the American notion that 'the customer is always right' - collective self-criticism was part of our way of life. We were a learning organisation.’

‘Individually and collectively, everyone was always looking for ways of adding value to their work. We encouraged staff to keep their skills up-to-date - but usually they came to us first, pressing us to give them more training and often paying for courses themselves.’

Multi-Disciplinary Learning

‘Above all, it was by mixing with business heavyweights outside the narrow context of my day-job that I learnt about such unfamiliar subjects as corporate governance, patents, company law, lobbying, demography, long-term strategic thinking, and so on; or simply what the next big thing in computing or regulation was likely to be, a few years down the line. Nobody teaches you these things, when you start your own business from scratch; nobody else is responsible for making sure that you are kept in the loop. But if you do not learn these things at some point it is hard to make the leap from cottage industry to substantial, established business; or, indeed, to keep your enterprise going at all.’

Trust and Empowerment

‘(The business) was thriving because of strengths that over a decade and a half had become embedded in its corporate DNA. Unlike its competitors, it was an enterprise founded on trust. Its workforce were not sullen, submissive employees. They were self-motivated self-starters who loved and understood what they did and took pride in and responsibility for their work.’

‘A feudal grandee can be as generous as he likes with his wealth and property, but as long as he remains the grandee then his dependants are not empowered: they are merely well fed. Empowering them means letting go: in other words, ceasing to be the grandee. I have struggled all my life with an instinct to hang on to the things that matter most to me, to control and protect them myself. Yet the art of surrender is, I am convinced, a key to many kinds of success - and fulfilment. And many lives are limited by a failure to master it.’

‘The older I get, the clearer it becomes to me that empowerment is the key to business success: not the blind surrender of power and responsibility to whoever wants it, but targeted empowerment, where those to whom power and responsibility are given have been painstakingly selected and, where appropriate, nurtured.’

‘So many of my landmark breakthroughs seem to have involved some form of counter-instinctive loosening of my grip on something.’

‘I don't think I have ever achieved anything of note that did not at some point require me to make a leap of faith in some other human being. If I have a talent, it is that: the ability to believe in what others can achieve. I recommend it. Trusting others is also about respecting yourself. The assumption that people will betray you or cheat you or let you down can all too often be self-fulfilling.’

‘Our people tended to be working not just to earn a living but to escape from the domestic obscurity and impotence that society had ordained for them. They knew that the company trusted them to make sensible use of their time: they were paid according to the work they accomplished, not the hours they clocked up.’

Business is People

‘It is people, not assets, that make the modern business world go round. It is their creative drive that sparks new enterprise and innovation, their professionalism and dedication that ensures quality, their energy that makes things happen - and, always, it is teamwork that carries forward the vision. Yes, by all means lead from the front, if that is your style, but always remember that leadership is nothing unless those who are led give the best of themselves.’

‘People are vital to any knowledge-intensive industry. The skills and loyalty of our workforce are our main asset. Equally important is the knowledge which comes from the exchange of ideas with our clients and their personnel.’

Community Support

‘I took the significant step of persuading the board to agree that from now on 1 per cent of all pre-tax profits would be given to charity. This decision was little noticed at the time, but over subsequent decades it would do an enormous amount of good, both to the beneficiaries and, I think, to the culture of the company.’

Win-Win

‘An extension of our ethical view is a belief in the goodwill of others: colleagues, clients and vendors. We also believe that goodwill results in positive, long-term relationships.’

Overseas Expansion Lessons

‘In each case (though in different ways), the market was inappropriate: too saturated in Denmark, too inflexible in the Netherlands, too mature in the US. Perhaps we should have worked that out in advance. Yet without those early experiments in overseas expansion we would never have been as well prepared to grow rapidly and effectively when the opportunity to become truly international arose in the 1990s.’

Word of Mouth

‘As with any business that thrives, success created its own momentum. Word spread through the small world of the computer-literate that there was a company in Buckingham-shire that offered interesting, flexible, rewarding employment to women working from home. Highly qualified people began to seek us out.’

Philanthropy

‘I knew that I wanted to give away all that remained of my wealth before I died.’

‘There is a limit to the number of possessions you can enjoy, or to the number of fine dinners you can eat or exotic holidays you can take; and there are drawbacks to extreme wealth (such as insincere, would-be 'friends') as well as advantages. On balance, I have no doubt at all: the money I have let go has brought me infinitely more joy than the money I have hung on to.’

‘The advantage of being rich was not the possessions it could provide but the security and freedom. That was all that really mattered to me: to know that (my son) Giles's future was assured, and to be free, otherwise, to spend my time as I chose. Once those two things were secure, it seemed ridiculous not to do something useful with whatever millions were left.’

Summary

Dame Stephanie Shirley’s life is both an extraordinary personal journey and a blueprint for enduring business success. From child refugee to pioneering entrepreneur, she embodied resilience, purpose, and the courage to challenge convention. Those experiences shaped not only her character but also the organisation she built — decades ahead of its time in flexible work, employee ownership, and values-driven leadership.

She understood a timeless truth: business is people. Her company thrived because it empowered individuals, trusted them with ownership, and placed purpose ahead of profit. For Shirley, financial success was never the target — it was the outcome of building a culture anchored in trust, empowerment, and giving back.

The fingerprints she left — resilience, discipline, innovation born of necessity, and generosity — are the same cultural markers we see in many of the world’s great compounders. Her story reminds us that enduring businesses are not built on balance sheets, but on the character and culture of their people.

For investors, the lesson is clear: seek leaders who view profit as a consequence, not a pursuit; who build organisations where values and people compound as powerfully as capital.

Source:
Shirley, Stephanie. Let It Go: My Extraordinary Story. London: Penguin Books, 2012.

Follow us on Twitter : @mastersinvest
* Visit the
Blog Archive *


TERMS OF USE: DISCLAIMER